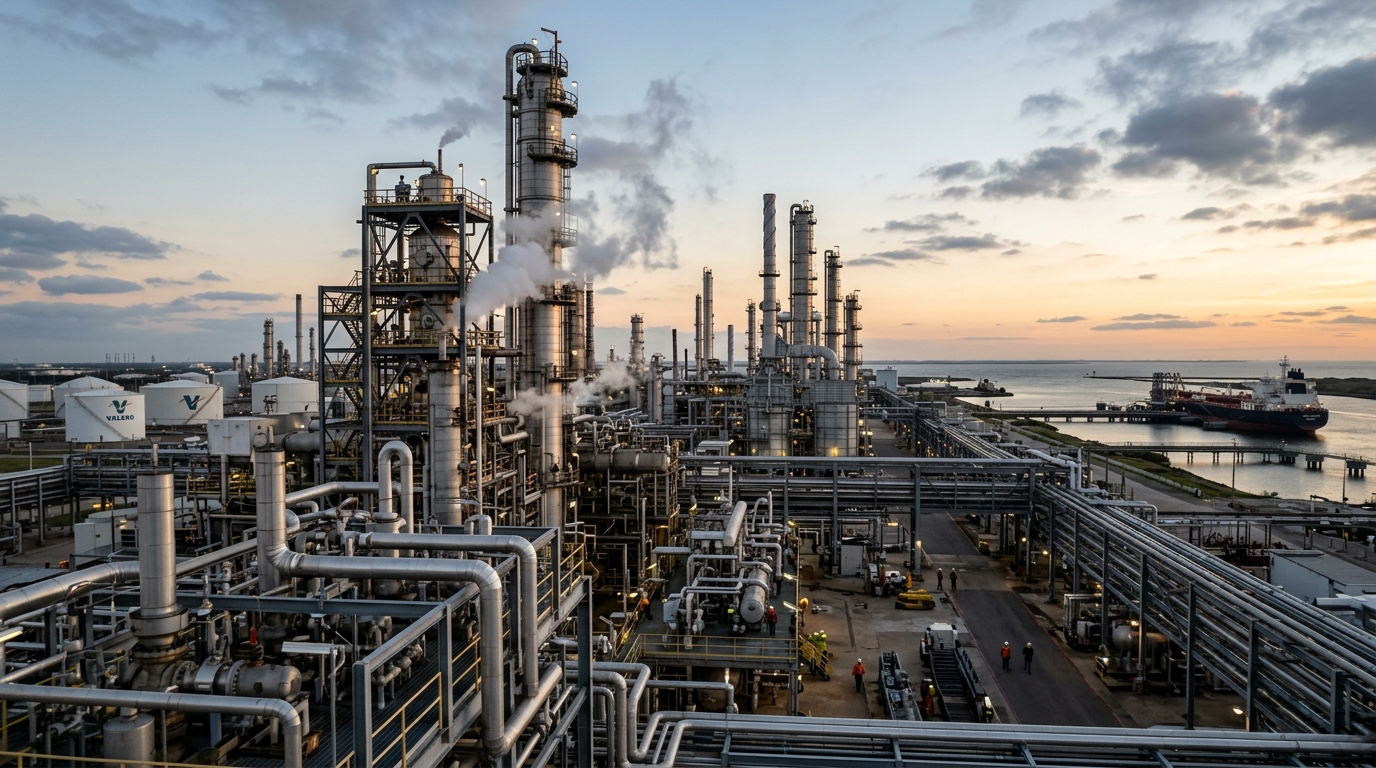
The trade is simple to describe and treacherous to hold. Strait of Hormuz disruptions have rerouted global fuel flows toward the United States, turning domestic refiners into the world’s swing suppliers for diesel and jet fuel. The margin expansion is real, the numbers are large, and the question every active trader should be asking right now is how much of it survives a single diplomatic headline.
How Large the Premium Has Gotten
The WTI 3-2-1 crack spread has been trading in the high-$50s to mid-$60s per barrel in recent sessions. That figure is not a rounding error. The driver is not domestic demand alone. Disruptions to crude and product flows through the Strait of Hormuz pushed international buyers toward alternative sources, driving up U.S. refinery margins, production, and exports.
Crack spreads have been especially elevated for distillate and jet fuel as the market has repriced product availability around conflict-related disruptions and route risk. U.S. jet fuel production has been running at historically high levels as global aviation supply adjusts to Middle East disruptions.
Who Captured the Margin
Marathon Petroleum delivered an exceptional Q2: net income rose to $5.1 billion, or $17.73 per share, from $1.2 billion a year earlier, with adjusted EBITDA rising to $8.5 billion from $3.3 billion.
Marathon’s Refining and Marketing segment adjusted EBITDA reached $24.84 per barrel in Q2 2026, against $6.79 per barrel in Q2 2025, with margin per barrel at $36.33 versus $17.58.
PBF Energy’s consolidated gross margin totaled $1.1468 billion for Q2 2026, compared to negative $58 million a year earlier, with gross refining margin at $23.40 per barrel versus $8.38 per barrel. Marathon shares have been up more than 150% at points in 2026, but the exact year-to-date gain depends on the measurement date and method. Valero has also rallied sharply in 2026, but it has not been consistently up more than 150% on a year-to-date basis.
The Structural Floor and the Geopolitical Ceiling
Refining margins have become increasingly volatile in 2026 because the short-term supply curve for refined products is exceptionally steep: refineries cannot quickly add capacity or increase output once utilization is already high, meaning even a modest supply disruption sharply lifts crack spreads. That structural tightness has a floor. Since 2019, multiple U.S. refinery closures and conversions have removed on the order of 1.2 million barrels per day of crude processing capacity, roughly 6% to 7% of U.S. operable capacity.
The ceiling is geopolitical. The crack spread blowout has been tied to conflict-driven disruptions and transport risk, and geopolitical premiums are reversible. That layering of chokepoints has kept the premium alive into October, but it also means any single de-escalation event could compress spreads faster than positions can be adjusted.
Scenario Modeling
Bull case: Disruptions persist through Q4, EU storage at roughly 73% proves insufficient for a cold winter, and jet fuel export arbitrage to Europe remains open. Crack spreads hold above $50 per barrel on the Gulf Coast.
Base case: Hormuz flows partially normalize, crack spreads compress toward $35 to $40 per barrel by year-end, refiners still beat 2025 comparisons by wide margins, and Valero’s October 22 earnings report shows Q3 above consensus but guides conservatively for Q4.
Bear case: A U.S.-Iran diplomatic framework restores meaningful Hormuz throughput before November. The crack collapses toward the $20 to $25 mid-cycle range. Analysts already warn that current gains reflect peak earnings with expected profit declines in 2027. Stocks priced for continuity of the geopolitical premium face the steepest drawdown.
Active Trader Framework
The positioning logic cuts two ways. Long refiner exposure has been one of 2026’s best risk-adjusted trades. Holding it into October 22 means accepting binary event risk: Valero’s Q3 results and Q4 guidance will either validate the premium or begin the multiple compression. Traders with existing positions should define the level at which geopolitical premium erosion changes the thesis, because the structural floor from capacity removals does not support current spreads on its own. Watch distillate export volumes in this week’s EIA data for early confirmation of whether the international bid is softening. The numbers will speak before the diplomats do.