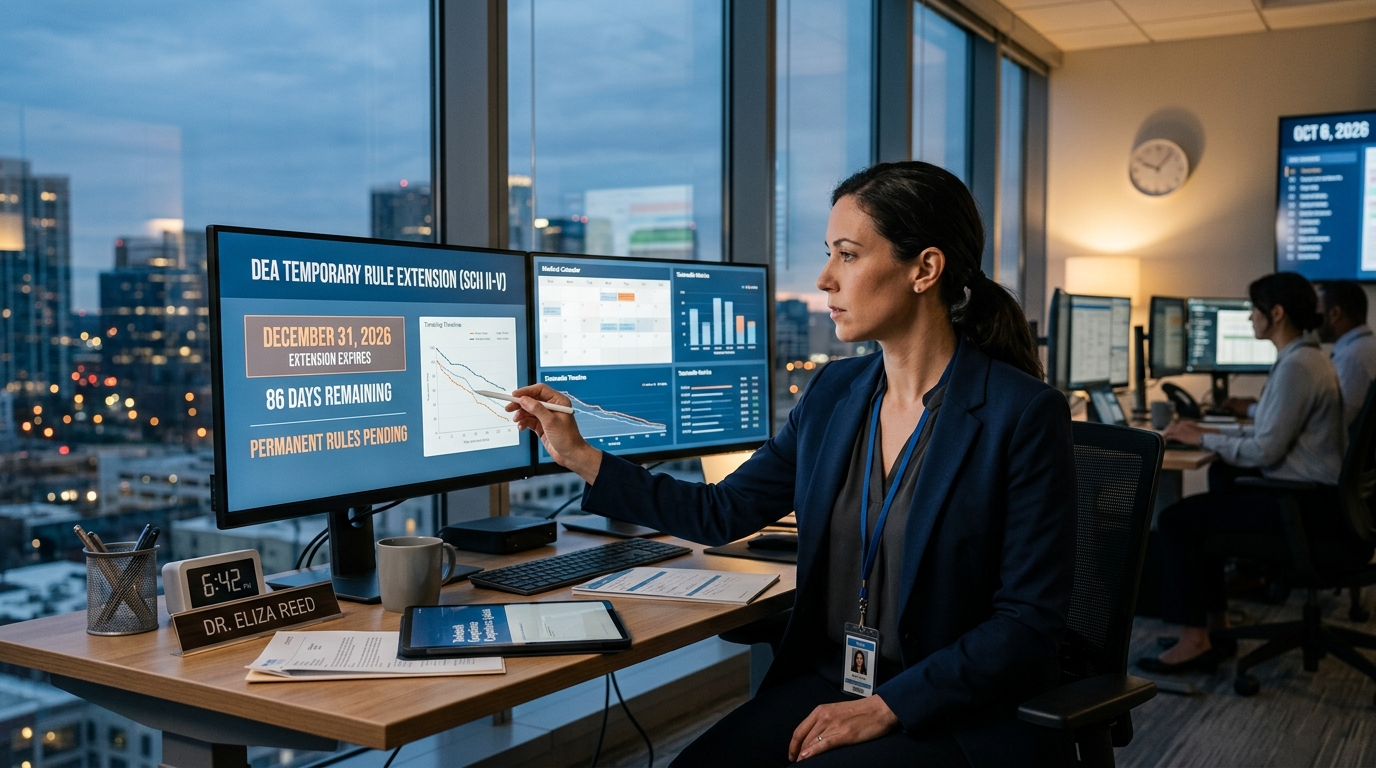
Every digital health operator in America is running on borrowed time. The DEA’s fourth temporary rule, published December 31, 2025, authorizes DEA-registered practitioners to remotely prescribe Schedule II-V controlled substances without an in-person evaluation through December 31, 2026. As of October 6, 2026, that date is 86 days away. The market has treated each annual extension as a routine formality. The fourth one should not be read that way.
- This is the fourth short-term extension since 2023, and the permanent framework, including a promised special registration for telemedicine prescribers, remains unfinished.
- Hims revenue grew from $527M in 2022 to $2.35B in 2025. Gross margin slipped from 82.0% (2023) to 73.8% (2025) as product mix shifted.
- Hims Q2 2026 revenue came in at $753M, up 38% year-over-year, with subscribers reaching nearly 2.9 million.
- Teladoc net profit margin as of June 30, 2026 stands at -7.13%.
- Teladoc’s full-year 2026 revenue guidance is $2.36 to $2.45 billion, with net loss per share projected at ($0.75) to ($1.00).
- Health systems and industry groups have pushed Congress for permanent telehealth policy, arguing that relying on repeated short-term extensions creates recurring uncertainty and operational disruption.
The Cost Embedded in the Current Model
The prescribing flexibility is not a side feature. For operators like Hims and mental health platforms built on behavioral telehealth, it is the product. In its announcement of the extension, HHS said the extension is intended to avoid a cliff that could disrupt care for patients who rely on remote prescribing while permanent rules are finalized. But disruption risk flows both ways. If permanent rules impose a special registration requirement with new documentation, technology, or visit-frequency standards, compliance overhead rises directly into already-compressed operating margins.
Separately from the DEA timeline, Medicare telehealth policy has also remained dependent on periodic legislative extensions, keeping reimbursement planning fluid for providers and platforms. Hims absorbed a Q1 2026 net loss of $92.1 million even while posting revenue growth, a signal that scaling into tighter regulatory conditions is not margin-neutral. Teladoc’s BetterHelp division tells a starker story: in Teladoc’s Q2 2026 results, BetterHelp adjusted EBITDA margin fell to 0.2%, down from 4.9% a year earlier.
Scenario Modeling
Bull Case: Congress passes the CONNECT for Health Act or the Telehealth Modernization Act before year-end, making a broader suite of telehealth flexibilities permanent and reducing the recurring uncertainty created by attaching critical coverage to must-pass funding bills. Operators avoid compliance restructuring costs. Hims trades toward the high end of its 2026 Adjusted EBITDA guidance of $275 to $325 million.
Base Case: A fifth short-term extension repeats the cycle. The permanent framework remains unfinished, and last-minute extensions become the status quo. Operators carry compliance uncertainty as a permanent cost of capital. Margin recovery stalls but no acute disruption forces patient volume offline. Teladoc holds its Integrated Care adjusted EBITDA margin in the 15-16% corridor.
Bear Case: The telemedicine cliff materializes as a sudden snapback to pre-pandemic restrictions imposed by the Controlled Substances Act, requiring in most cases at least one in-person medical evaluation before a provider can remotely prescribe controlled substances. Platforms built around asynchronous prescription flows face immediate revenue disruption. Gross margins compress 500 to 800 basis points as in-person visit overhead is absorbed or patient volumes fall.
Active Trader Framework
The key date is December 31. Watch for DEA rulemaking signals in November, any Congressional action on the CONNECT for Health Act, and Hims Q3 earnings for margin trajectory data. Federal guidance continues to emphasize that facilities relying on telemedicine for controlled-substance prescribing should track DEA rulemaking closely because the regulatory landscape is still evolving. For traders, that uncertainty is a pricing gap. The market is valuing Hims at 3.5x sales and Teladoc at 0.7x. The divergence reflects growth expectations, not regulatory risk differentiation. If permanent rules add compliance friction, the operator with the tighter cost structure wins. Preparation over prediction. Know the December 31 deadline before the market does.