October 6, 2026
Bonus Content: Insurance Claims Adjusters Are Disappearing. One Stock Gains.
If you still haven’t downloaded my “Simple Options Trading For Beginners” book…
…please take a few seconds and download it right now before your new temporary download link expires.
I eventually plan to charge for this book, so do yourself a favor and download it now…
That way, no matter how much it is in the future, you’ll have a copy on your computer already.
Make sense?
FREE: Simple Options Trading For Beginners << Download Now
Good Trading,
Bill Poulos
P.S. Go here to save a copy of my “Simple Options Trading For Beginners” book to your computer before I start charging for it.
Insurance Claims Adjusters Are Disappearing. One Stock Gains.
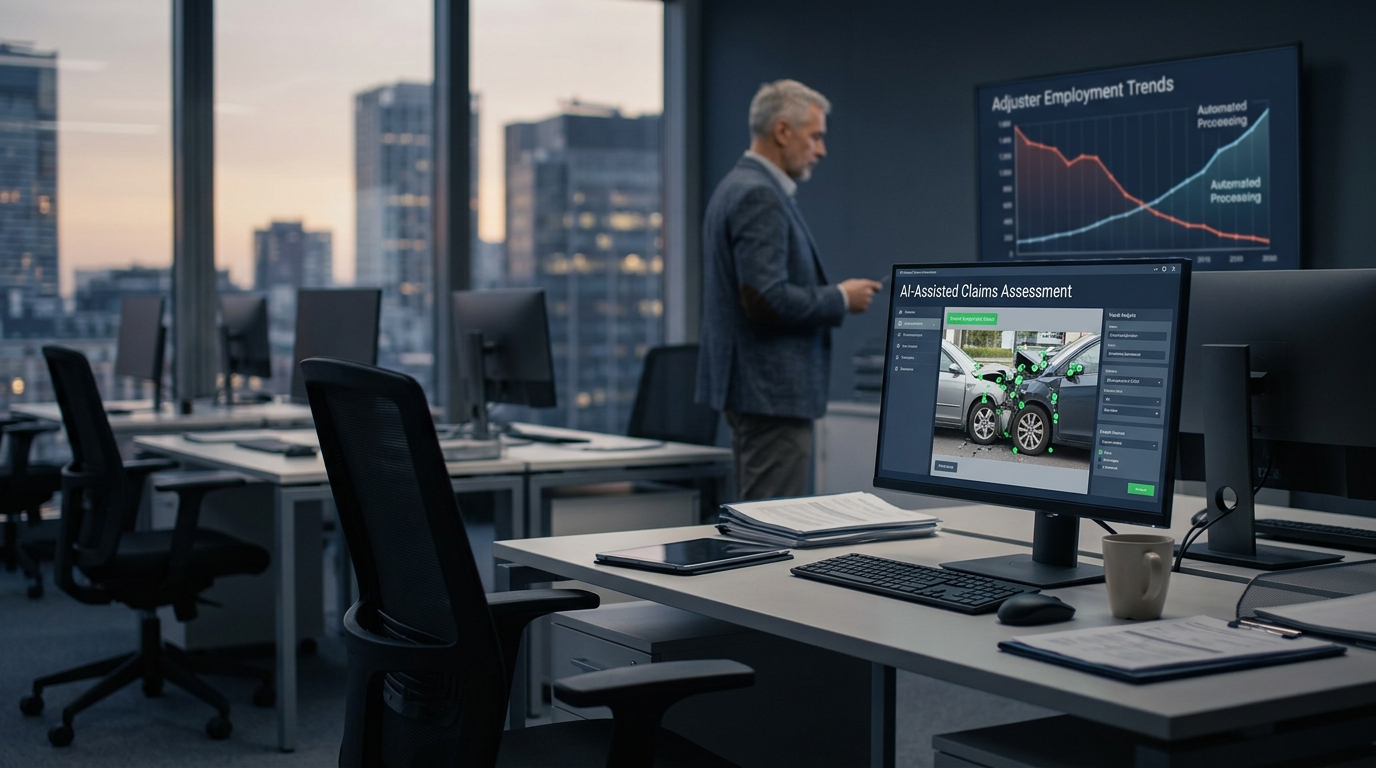
The data coming out of the insurance labor market is stark. Entry-level claims adjuster job postings have fallen close to 50% since early 2024, and overall adjuster employment dropped about 21% year-over-year through May 2026, according to Glassdoor and Indeed research. Insurance job postings for claims adjusters overall are down around 55% from their post-pandemic peak. Senior-level postings remain around 80% above 2017 levels, suggesting demand for experienced adjusters is holding. But that senior cohort is not being replenished.
That is not a recession statistic. It is a structural one, and the beneficiary is already publicly traded.
Where the Margin Is Going
CCC Intelligent Solutions (NASDAQ: CCC) is the clearest financial proxy for this automation wave. Q2 2026 revenue came in at $285.9 million, up 9.8% year-over-year, with a 74% gross margin. Full-year 2026 guidance sits at $1.158 billion to $1.164 billion. The more telling number: AI-based solutions now account for about 11% of revenue and are growing at roughly 45% year-over-year, far outpacing the core platform. Annualized AI revenue has crossed $120 million, and the company has said deployments are increasingly backed by multiyear commitments rather than pilots.
The underlying technology is computer vision applied to auto and property damage. A policyholder submits photos; the model returns a line-item repair estimate in seconds, no field adjuster required. CCC says its AI models are in use across more than 125 insurers and more than 15,000 repair facilities. Tractable, a private competitor, has said its AI processes more than $2 billion in vehicle repairs and purchases annually. Claims automation can push straight-through processing higher, but the exact rate and accuracy ranges vary by book of business and carrier implementation.
The Compensa Signal
The cost math is severe for traditional operations. Compensa Poland has been cited in an Accenture case study as achieving as much as a 73% increase in claims process cost efficiency after deploying an AI-based self-service claims solution. McKinsey has argued that automation and AI can reduce adjustment expenses, but it does not present a universal 25% to 30% figure for loss adjustment expenses tied specifically to reserve modeling plus computer vision across carriers. Those are not incremental improvements; they restructure the combined ratio.
The Hidden Risk in the Workforce Data
There is a structural tail risk the vendor slide decks ignore. Junior adjuster roles are the training pipeline for experienced ones. With entry-level postings down close to 50%, the industry is not just cutting costs; it is thinning the bench that handles catastrophe surges, complex multi-party liability, and fraud investigations requiring human judgment.
Three Scenarios
Bull Case: CCC’s AI revenue sustains 40%-plus growth into 2027 as carriers accelerate production rollouts. Gross margins trend toward the company’s stated 80% long-term target. The stock re-rates on a software-like multiple.
Base Case: AI revenue grows 35% to 40% in 2026, contributing 13% to 15% of total revenue by year-end. Core platform growth holds near 8% to 9%. CCC’s adjusted EBITDA margin expands modestly toward 42% as guided. The pipeline of insurer automation conversions remains the primary revenue catalyst.
Bear Case: Large carrier customer concentration becomes the pressure point. CCC has pointed to an approximately one-point revenue headwind in the second half of 2026 as an insurance carrier transitions away its legacy first-party casualty business. If a second major insurer builds competing in-house tooling or consolidates vendors, pricing leverage narrows and the 45% AI growth rate slows sharply.
What Traders Should Watch
The adoption rate is the leading indicator. CCC has said AI-enabled claim volume currently ranges from low single-digits to low double-digits of total claims processed, depending on the product. The move from 5% to 15% touchless processing is where revenue inflects. Monitor Q3 results, expected in late October 2026, for whether AI revenue holds its roughly 45% growth pace. Any compression in that figure changes the valuation math on a stock trading at a premium to legacy insurance technology peers. The workforce displacement data confirms the shift is real. The question is how fast the remaining claims enter the automated pipeline.