The story being told in the gilt market this week is not a British one. It is a global one that happens to be loudest in London.
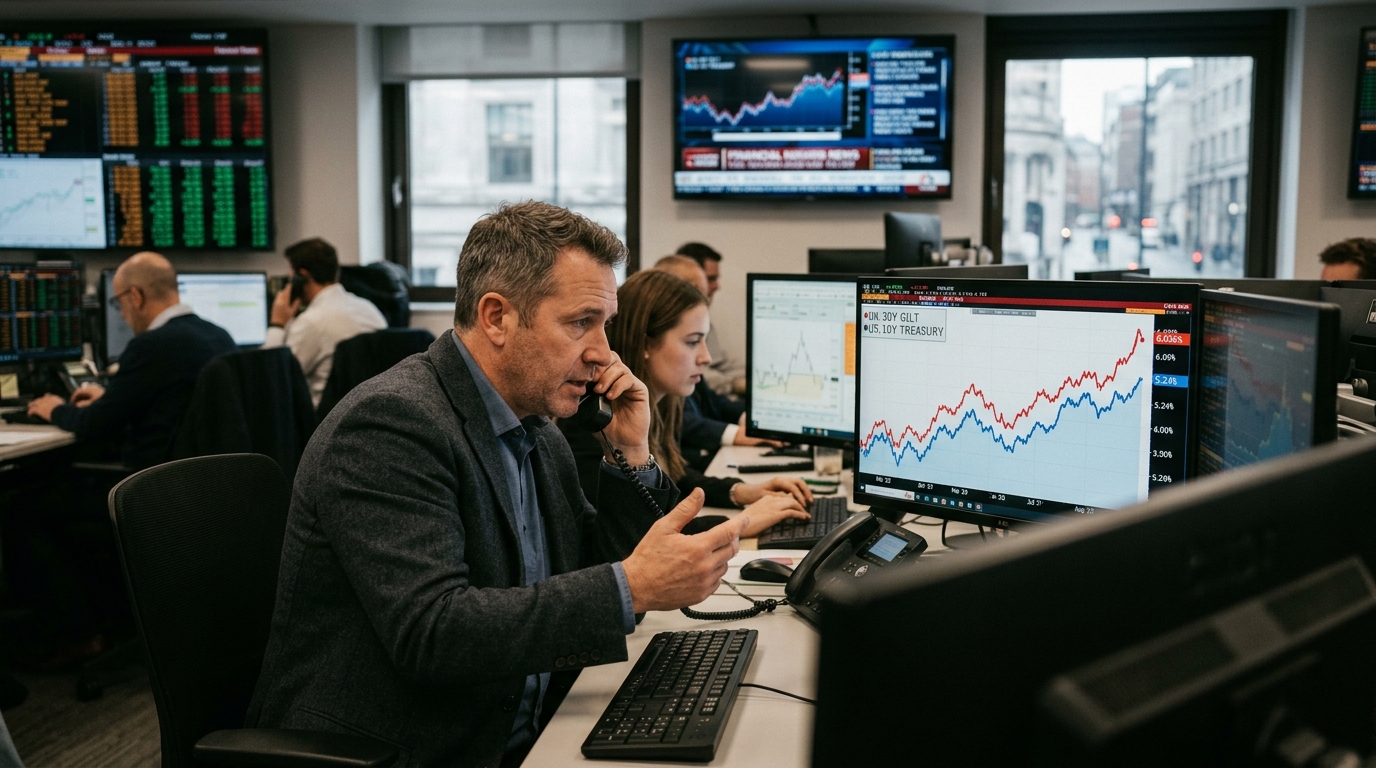
British 30-year bond yields rose to a 28-year high on Wednesday as a global bond selloff pushed equivalent US borrowing costs to their highest since 2002. Yields on 30-year gilts jumped 13 basis points on the day to peak at 6.036%, their highest since January 1998 and pushing past a previous record set on October 1. Thirty-year Treasury yields were 7 basis points up on the same day while 10-year Treasuries were 6 basis points higher, compared with a 10 basis point rise in Britain’s 10-year gilt to 5.48%. The US 10-year is now sitting at 5.24%. These are not separate national situations. They are one move.
What Is Actually Driving This
Inflation and high levels of government borrowing remain a big worry for bond investors globally, exacerbated as oil prices rose further above $100 a barrel amid the war involving the United States, Israel and Iran. That is the surface reading. The deeper one is a systematic reset of how much compensation long-duration holders require for locking in for 20 or 30 years when fiscal credibility is in doubt almost everywhere.
Ten-year gilt yields are more representative of the cost of new government borrowing and are just short of their highest since 2007. For investors used to thinking of the long end as a relatively stable anchor, the past two weeks have been a sharp correction to that assumption.
What the Market May Be Missing
The Bank of England’s revised quantitative tightening plan, announced last month, was supposed to offer relief. The Bank will focus on selling shorter and medium-maturity bonds as it unwinds its £368 billion gilt portfolio, with an average annual reduction target of £46 billion: £20 billion per year in active sales and the remaining £26 billion arriving passively as bonds mature. Long-dated gilt sales are halted entirely. In September that news pushed 30-year yields down sharply for a day. Six weeks later, yields are at levels that make that relief look temporary.
The more important pressure is structural, not cyclical. Analysts at Pantheon Macroeconomics calculate that the bond market rout has already slashed Chancellor Healey’s fiscal cushion from £23.6 billion at the Spring Statement to roughly £13 billion. Every 0.25 percentage point rise in UK gilt yields adds approximately £2.5 billion to the government’s annual debt-servicing costs. That arithmetic has been running against Healey all autumn, and it is still running.
Where It Shows Up
British stocks fell on Wednesday as the gilt selloff pushed 30-year yields above 6%, hitting banks in particular. Standard Chartered fell 3.82%, HSBC 3.81%, Barclays 3.51%, Lloyds 3.37%, and NatWest 3.26%. UK lenders were the main drag through the week: Lloyds, NatWest and Barclays were among the biggest decliners in index points, hurt by the gilt selloff and by speculation that the October 28 Budget could raise the bank surcharge.
The mechanism is direct. Higher long-end yields widen the gap between what banks borrow at and what they can prudently lend at in fixed-rate mortgages, compressing margins and weakening the outlook for domestic loan books. For Lloyds and NatWest, both heavily exposed to UK household credit, that is not a peripheral risk.
Risks and Counterpoints
The bull case for gilts rests on the Budget itself. The gilt move on Wednesday followed a meeting between Healey and economists working for primary dealers, assessing market sentiment before the budget. Britain’s finance ministry reaffirmed the government’s commitment to its fiscal rules. If Healey delivers a credible consolidation on October 28, with enough revenue measures to demonstrably narrow borrowing, the long end could rally hard on relief, much as it did briefly after the Bank of England’s QT overhaul.
Economists at Bank of America forecast that Healey’s budget would lead to £15 billion increases in public borrowing in both the current financial year and 2027/28, and to less leeway to hit longer-term budget goals. If that projection proves accurate, the selloff has further to run regardless of what happens globally.
What to Watch Next
The October 28 Budget is the clearest near-term catalyst for gilts. Watch whether Healey’s fiscal statement narrows or widens the gap between spending commitments and credible revenue. The UK 10-year yield trading above 5.50% for any sustained period would signal the market is no longer willing to wait for that answer. The FTSE 100’s financial sector, and sterling’s position against the dollar, will confirm or contradict the gilt market’s read within hours of Healey sitting down.