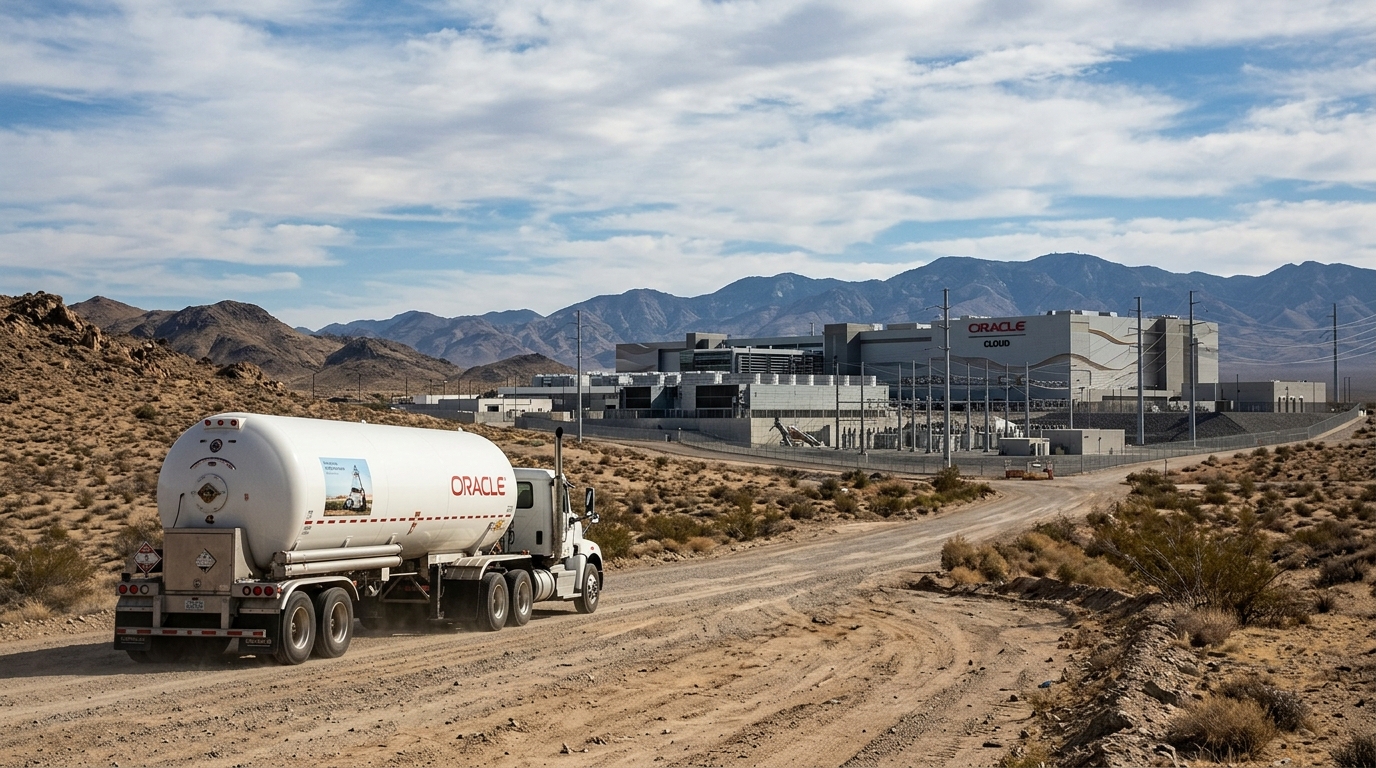
Oracle is sitting on the largest contracted backlog in enterprise software history. It is also trucking natural gas through the desert. Both things are true right now, and the gap between them is where the trade lives.
- Q1 FY27 revenue hit $19.3 billion, up 30% year over year, with 850MW of additional data center capacity delivered in the quarter.
- Cloud infrastructure (IaaS) revenue surged 121% to $7.4 billion, driven by record new megawatt capacity coming online.
- Oracle booked more than $30 billion of additional AI cloud contracts in Q1 FY27, pushing remaining performance obligations to $664 billion.
- On October 8, Bloomberg reported Oracle is weighing trucked gas for Project Jupiter in New Mexico. ORCL fell about 5.5% that session.
- A Financial Times report then said OpenAI’s annualized revenue pace was approaching $50 billion at the end of September, roughly $20 billion below the widely reported ~$70 billion figure from last month.
- Wall Street still rates ORCL a Strong Buy, with an average price target around $242.62.
- Oracle plans to raise approximately $40 billion through debt and equity during fiscal 2027 to fund its AI expansion.
The Infrastructure Execution Risk
Project Jupiter is a flagship element of the Stargate AI program involving Oracle, OpenAI, and SoftBank. New Mexico’s State Land Office has twice denied Energy Transfer’s request for rights-of-way on a 17-mile natural-gas pipeline needed to supply the site.
Oracle sent a force majeure notice to Project Jupiter’s developer, a unit of Blue Owl Capital, formally asserting that events beyond its control could stall the 2.45-gigawatt campus. The financial mechanism matters: press reports said the notice is tied to lease-payment timing, potentially allowing Oracle to delay the start of rent payments if the site is not available, while not reducing the total commitment.
Trucked natural gas can cost roughly four times as much as pipeline gas, and even 100MW of capacity requires dozens of daily deliveries. For a 2.45GW campus, the cost delta is not rounding error. Analysts have generally framed Jupiter as a timing issue rather than an immediate fiscal 2027 revenue driver, but the market is pricing execution uncertainty, not this quarter’s income statement.
The $18 billion in project loans are described in press reports as trading at distressed levels, and broader legal challenges continue even after the New Mexico Supreme Court denied an emergency request to partially resume an air permit proceeding in September. Even if the force majeure provision is invoked, the total payment obligation may not decrease. The delayed timing alone could affect loan repayment schedules and investor returns.
The OpenAI Revenue Revision
The Jupiter headline landed on top of a second pressure point. OpenAI’s annualized revenue pace was described by the Financial Times as approaching $50 billion, below the roughly $68 billion to $70 billion figure that circulated last month. For Oracle specifically, the revision matters because OpenAI is the anchor tenant at Jupiter and a central counterparty in the Stargate framework. If operations at the New Mexico facility are delayed by more than a year, Oracle’s revenue recognition timeline will slip, potentially disrupting service delivery schedules to OpenAI.
Technical and Scenario Framework
ORCL is trading near the bottom of its 52-week range and below its 200-day simple moving average. The stock has bounced off early-week lows but remains structurally vulnerable. Key levels to monitor: the September post-earnings range high near $175, the current consolidation band around $138 to $142, and the Q1 FY27 earnings gap-fill zone near $130.
Bull Case: Oracle has said roughly half of the $664 billion in remaining performance obligations is expected to be recognized as revenue within 36 months. If capacity comes online ahead of schedule via a trucked-gas bridge and the pipeline clears approvals in H1 2027, fiscal 2027 revenue of at least $90 billion is achievable. ORCL moves toward analyst targets above $240.
Base Case: Jupiter opens in phases starting late 2027. Fiscal 2027 guidance of at least $90 billion in revenue holds, but investors apply a higher execution discount. The stock consolidates between $135 and $160 through the next earnings report in December.
Bear Case: Pipeline litigation extends into 2028. A Jupiter schedule slip escalates into execution risk for the broader Stargate buildout SoftBank is backing. Combined with any further OpenAI revenue revisions, ORCL tests the $120 to $125 zone, where trailing twelve-month cloud revenue multiples begin to compress toward peers.
Active Trader Framework
The Q2 FY27 earnings call in December is the next hard catalyst. Traders should watch Blue Owl Capital (OWL) for any formal response to the force majeure notice and Energy Transfer (ET) for permit news out of New Mexico. A pipeline right-of-way approval is a binary upside event; another legal setback is not priced in at current levels.
Position sizing should account for headline sensitivity on both the OpenAI and Jupiter fronts. Volatility around ORCL has been asymmetric to the downside on infrastructure news. Disciplined risk management means defining loss limits before the next regulatory decision, not after.
Oracle’s backlog is real. The question is whether the physical infrastructure needed to monetize it can clear a permitting regime that has already said no twice. Preparation for both outcomes is the only trade worth making here.