October 12, 2026
Bonus Content: Diesel Hit a Record $117.92 Crack While Crude Barely Moved. Here Is the Trade.
You’ve heard of a bail-out – taxpayers rescue a failing bank. A bail-in flips where the rescue money comes from.
Instead of reaching into the public treasury, a troubled bank can be propped up using the funds already sitting inside it – depositor funds. That pathway was written into U.S. law through the 2010 financial-reform legislation passed after the 2008 collapse.
Translation: a bank on the edge may have a legal route to use a portion of customer deposits to stabilize itself.
With recession risk back in the conversation and inflation eating purchasing power, this is no longer purely hypothetical. Reagan Gold Group’s free guide shows how to reposition part of your retirement into metals without triggering taxes or penalties.
Diesel Hit a Record $117.92 Crack While Crude Barely Moved. Here Is the Trade.
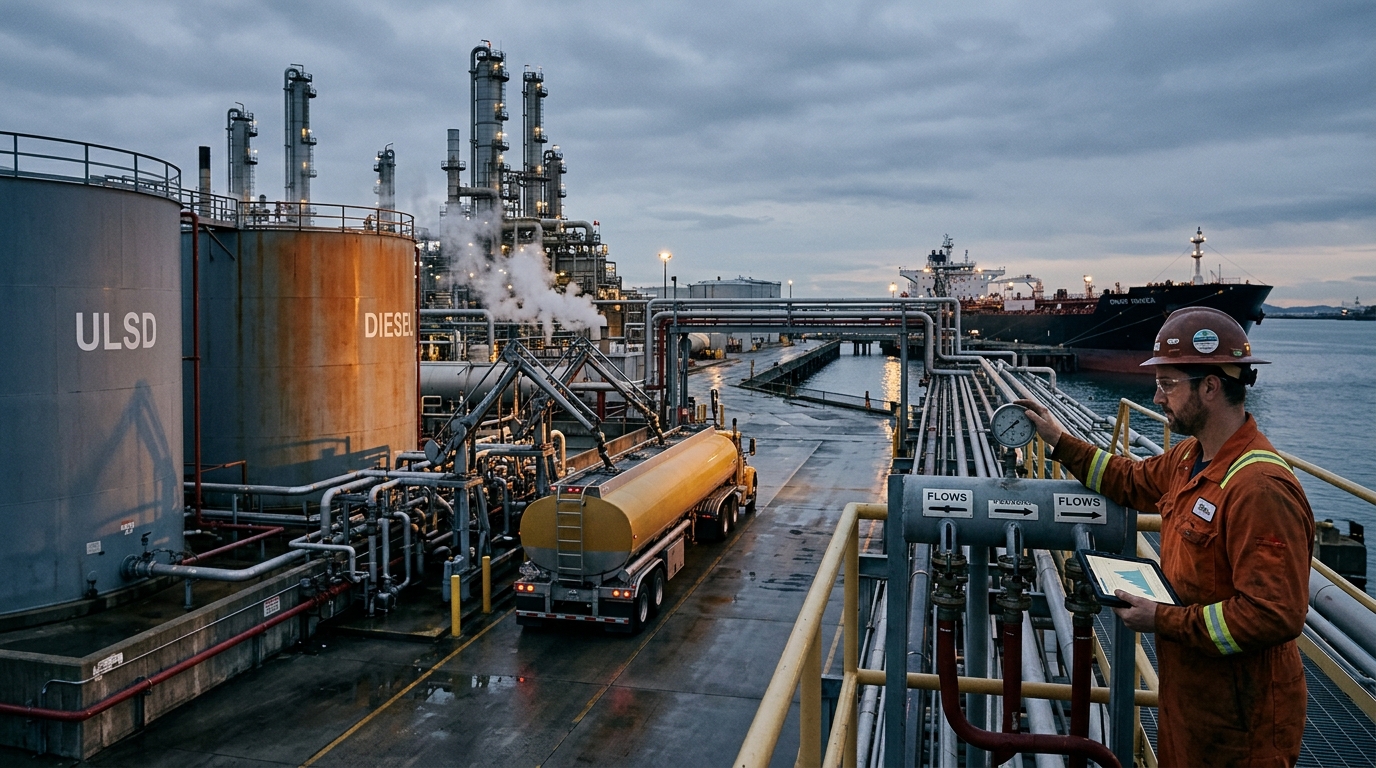
Crude oil spent October oscillating inside a roughly $98-$105 band, fell again Monday on ceasefire headlines, and drew barely a shoulder-shrug from the energy desk. The real action is one product downstream. The U.S. ULSD crack spread hit a record $117.92 per barrel on September 16, and even after a modest pullback it still measured $107.15 versus WTI as of October 9. Pre-crisis norms sat between $15 and $25 a barrel. The market has not simply widened; it has structurally reset.
That reset is a distillate supply problem, not a crude problem. New York Harbor distillate inventories were unusually tight in late September, but this draft’s specific New York stock numbers could not be verified from EIA’s standard weekly regional stock tables. The EIA’s October Short-Term Energy Outlook said East Coast distillate inventories fell 32% below their five-year seasonal average in September and expects them to remain around 20% below that average through the upcoming winter heating season. U.S. diesel exports, drawing down domestic supply further, have remained elevated. Retail diesel averaged $6.199 per gallon the week of October 5, about $2.45 above year-ago levels, even as crude trades well below its 2022 highs.
Why the G7 Release Changes the Calculus, Not the Trade
On October 2, the G7 agreed to release 100 million barrels of oil and fuel products over four months, with a front-loaded diesel tranche within the first 20 days. The EIA noted in its October outlook that its price forecast does not account for any additional crude oil or petroleum products on the market as a result of the G7’s October 2 announcement. The EIA’s October outlook sees retail diesel averaging $5.81 in Q4 2026 and $4.49 in 2027. The G7 announcement softened crude somewhat; it has not closed the crack.
That asymmetry is the trade. Long refining margin, flat crude. An independent refiner earns the spread between what it pays for crude and what it sells diesel for; when product prices outrun crude, earnings leverage is enormous for companies without upstream production to weigh against it.
What the Numbers Imply for Q3 Earnings
Benchmark U.S. crack spreads averaged approximately $63 per barrel in Q3 2026, up 26% from Q2’s $50 average and roughly 2.4 times the year-earlier level. For Valero’s Gulf Coast operations, the realized crude-to-product spread reached $47.11 per barrel in Q3, against $30.28 in Q2. VLO reports October 22; the consensus Q3 EPS estimate has been revised up nearly 36% over the past month to roughly $16.58-$17.66 per share. Even at $440, VLO trades at a forward multiple of approximately 7.7 times 2026 consensus earnings. In Q2, VLO’s refining segment reported operating income of about $4.5 billion, up from about $1.3 billion a year earlier.
Marathon Petroleum posted Q2 net income of $5.1 billion, with adjusted diluted EPS of $17.73, and R&M margin capture ran at 112% in Q2. MPC guided Q3 throughput at 3 million barrels per day with Gulf Coast at 100% utilization. MPC’s 2026 EPS consensus was revised 37% higher over the prior 60 days. Phillips 66 generated $3.8 billion of net income in Q2, with realized refining margins of $24.08 per barrel. PSX expects mid-90% crude utilization in Q3.
Technical Framework
The ULSD crack versus WTI has held above $94 on closes since mid-August, with the September high at $117.92 acting as a reference ceiling. The critical structural support level for the thesis is roughly $60 a barrel on the ULSD crack: three consecutive weekly national distillate builds in which PADD 1 also builds, combined with a crack move below that threshold, would functionally invalidate the long-margin position. That trigger has not come close to firing. VLO’s 52-week range runs $155 to $447, with the stock near the top of that range.
Scenario Modeling
Bull Case
Hormuz disruptions persist, Russian export restrictions extend beyond October, and East Coast stocks stay 25%+ below the seasonal norm through December. The ULSD crack holds above $100, Q3 earnings for VLO, MPC, and PSX print 20-30% above current elevated estimates, and forward earnings estimates are revised sharply higher. Refiner multiples expand as investors price at least two more quarters of structurally wide margins.
Base Case
The G7 diesel release partially replenishes coastal inventories through November, the crack eases toward $80-$90 but remains well above historical norms, and Q3 reports confirm record quarterly profits without further upside revision. Refiner stocks consolidate near current levels with sustained buyback support. MPC returned $2.8 billion in Q2 alone.
Bear Case
A Trump-Putin ceasefire arrangement restores Russian diesel exports materially, the Hormuz situation de-escalates faster than priced, and the ULSD crack collapses toward $50-$60. Q4 estimates face sharp downward revision. At that point the low trailing P/E multiples, which reflect peak earnings, become a warning rather than a value signal.
Active Trader Considerations
The cleanest expression is long crack spread exposure via refiner equity rather than outright product futures. VLO and MPC carry the greatest pure-refining leverage. Watch the weekly EIA distillate inventory report every Thursday as the primary trigger: a sustained PADD 1 build is the single most credible crack-narrowing signal available in near-real-time data. Volatility around earnings dates, October 22 for VLO and November 3 for MPC, will be elevated. Size accordingly, and define your crack-spread exit level before the trade, not after.
The data here is clear: diesel is not trading like crude, and crude releases cannot fix a refining margin problem. Preparation means knowing precisely which inventory number changes the structural case, and having an exit framework before that number prints.