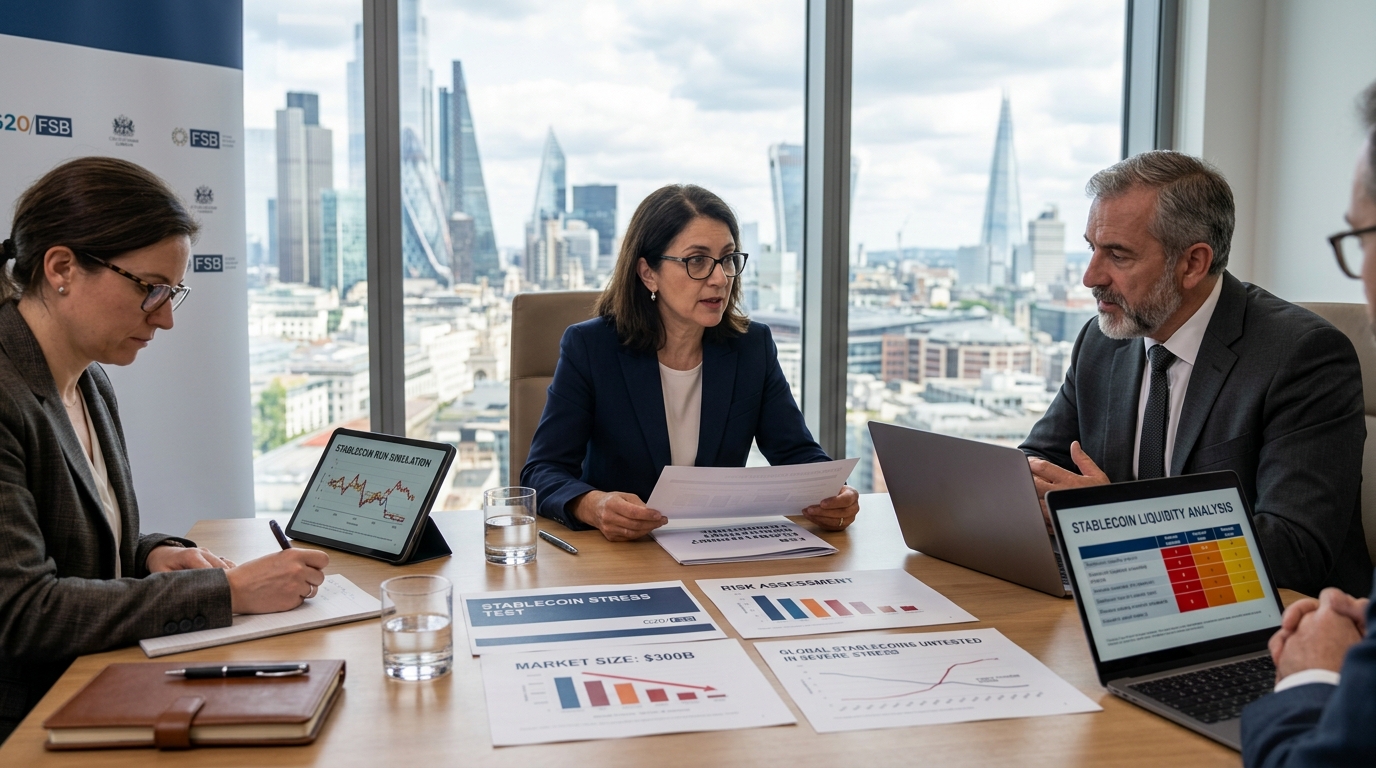
On October 12, global financial regulators handed the G20 a finding that deserves more attention than it has received: the stablecoin market has grown to roughly $300 billion, and nobody actually knows what happens when a large issuer fails.
The FSB’s central finding is an uncomfortable one: “Global stablecoins and national regulatory frameworks remain untested in severe stress and insolvency.” That is not a description of a problem that already happened. It is a description of an open flank. Nobody knows what happens when a large issuer fails and holders in dozens of countries want their money back at the same time.
The stablecoin market stands at approximately $300 billion in mid-2026, with about 99% of fiat-backed stablecoins by value pegged to the US dollar. For most investors, these instruments serve as the parking lot of crypto portfolios: a place to hold value between trades, lock in gains, or earn yield. They feel like cash. The FSB’s point is that during a genuine panic, they may not behave like it.
Where the Risk Actually Lives
The core danger is not that reserves are missing. The FSB cautioned that stablecoins could face runs if, during periods of market stress, their reserves become inaccessible across borders. Stablecoin issuers operating through affiliated entities in different countries may struggle to meet concentrated redemption demands when their reserve assets are held elsewhere.
Digital tokens can move across borders and trade 24 hours a day, while the Treasury securities, bank deposits, and other traditional assets backing them remain subject to local financial market operating hours and payment arrangements. That gap, between a token that never sleeps and a reserve that does, is where a crisis would erupt. Delays in meeting redemptions could push holders to sell stablecoins at discounts on secondary markets, potentially destabilizing their dollar pegs.
The Two Issuers That Dominate the Market
Tether’s USDT is the market’s dominant coin. It stood at about $184 billion in 2026 and has ranked among the largest cryptocurrencies by market value. Tether historically published regular BDO Italia attestations, and in August 2026 the company said it had completed a full independent audit of its 2025 financial statements by KPMG US. For holders, that means the disclosure story is no longer just point-in-time attestations, though the practical question remains the same: how quickly, and under what legal and operational constraints, redemptions can be met in a real panic.
Circle’s USDC operates differently. Circle reports that USDC reserves are held in cash and short-dated U.S. government assets, and it points holders to transparency reporting that includes details on the Circle Reserve Fund (USDXX), with holdings information updated on BlackRock’s website. Circle has been a public company since its June 2025 NYSE listing and publishes audited financials. That raises the disclosure floor meaningfully, though USDC did depeg as low as about $0.87 in March 2023 during the Silicon Valley Bank crisis, when Circle disclosed that $3.3 billion of USDC reserves were held at SVB.
The Regulatory Window Closing This Week
One US comment period closes this week: the SEC’s proposed Regulation Crypto Assets closes on October 20, 2026. That deadline does not change what is currently legal, but it shapes the rules that will. Separately, the GENIUS Act’s core framework is scheduled to take effect on January 18, 2027 unless the primary federal payment stablecoin regulators finalize implementing rules sooner, which would start a 120-day clock.
The SEC’s proposal creates two exemptions from Securities Act registration for certain crypto asset investment contracts: offerings of up to $5 million over four years, and up to $75 million in any 12 months. After October 20, the SEC will consider comments before deciding whether to adopt a final rule.
What to Ask Before You Park Money in a Stablecoin
The FSB’s warning is not an instruction to sell. It is an instruction to ask better questions. Four matter most.
How often are reserves independently verified, and by whom? More frequent, more granular reserve reporting is more protective than occasional category summaries. The gap between those two standards is not small.
Where are the reserves held, and across how many jurisdictions? The FSB warns that stablecoins could face redemption crises even when their total reserves are sufficient but spread across different countries. A coin whose reserves sit in one jurisdiction under a single regulatory regime carries less cross-border risk than one dispersed across affiliates.
What are your redemption rights if the issuer becomes insolvent? Under the GENIUS Act framework, the law is designed to give holders stronger protections in insolvency than a typical unsecured claim. Not every coin offers comparable protections today.
Is the issuer subject to meaningful regulatory oversight? The January 18, 2027 GENIUS Act effective date will draw a clearer line. Until then, oversight varies enormously by issuer.
The wealth-building lesson here is not that stablecoins are inherently dangerous. It is that size and familiarity are not the same thing as safety, and that the difference between issuers is large enough to matter when conditions turn.