Intuitive Surgical trades at $426 heading into Tuesday’s after-close earnings release, sitting 29% below its 52-week high of $603.88. The stock has gained nearly 12% over the past month as institutional buyers returned, and the business behind the recovery is not hard to explain.
The consensus calls for Q3 EPS of roughly $2.61 to $2.65, an increase of approximately 9% from a year ago, on revenue of $2.88 billion, which would represent growth of about 15% year over year. Those are the targets. The more interesting question is whether ISRG beats them again, as it has in each of the past four quarters.
What Is Actually Driving This Business
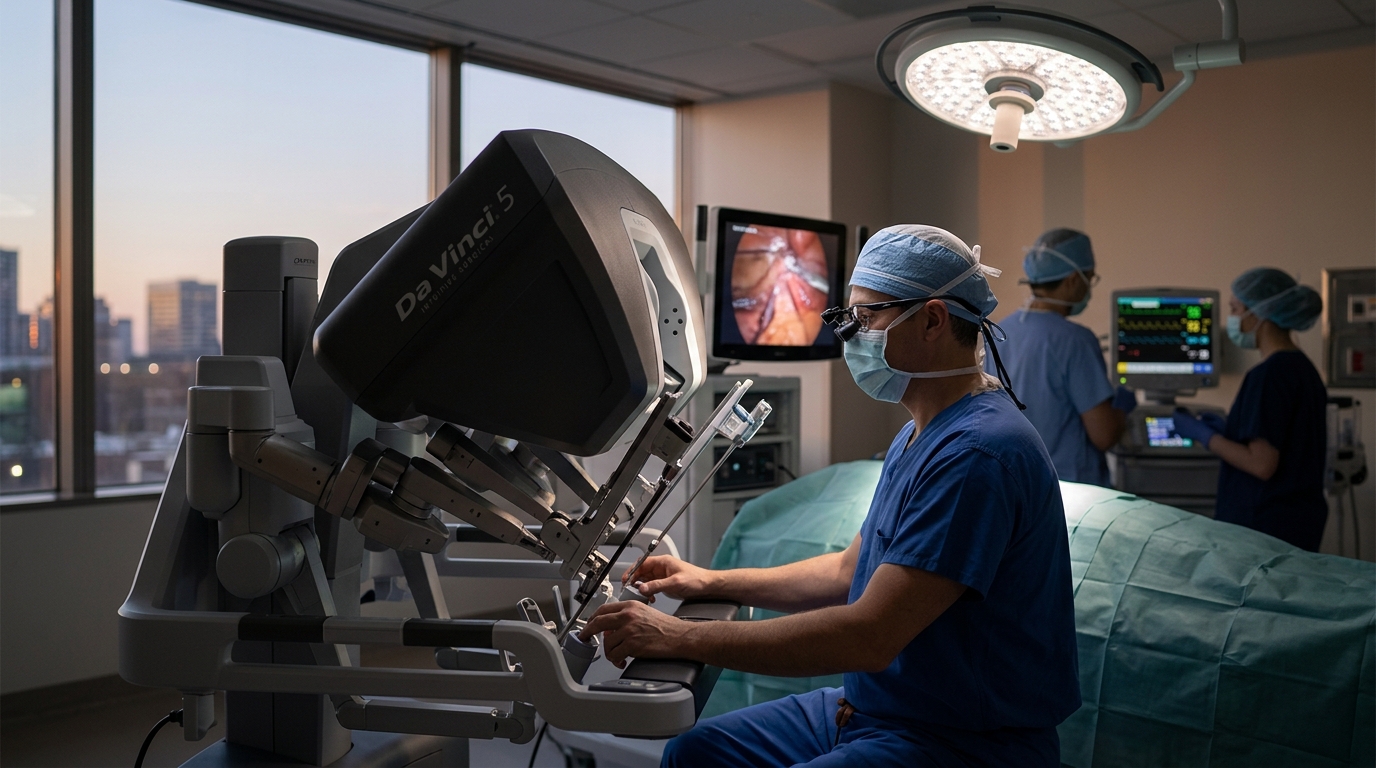
Procedure volume is the engine. Combined da Vinci and Ion procedures grew 17% in Q1 and 16% in Q2. For the first half, revenues rose approximately 21% to $5.66 billion. Da Vinci 5, the latest generation system, accounted for 246 of the 468 da Vinci systems placed in Q2, up from 180 a year earlier. The installed base now exceeds 11,700 da Vinci systems globally.
Ion, the lung biopsy platform, is growing even faster. CEO Dave Rosa has described gastrointestinal robotics as a natural extension of the company’s mission, and the Ion platform has now been installed across 12 countries outside the United States. International da Vinci procedure growth ran at 19% in Q1, and management said Q2 procedure growth outside the U.S. was driven primarily by general surgery.
Why the Stock Has Been Frustrating
Despite procedure growth running well ahead of the 13.5% to 15.5% guidance Intuitive gave for 2026, the stock is still deeply below its highs. The valuation premium is real: ISRG trades at roughly 49x trailing earnings. That multiple leaves limited margin for disappointment and is a main reason a Q2 beat still sent the stock sharply lower right after the report.
Competitive pressure in China is a genuine risk. Domestic robotic surgery companies have been gaining share in a market where Intuitive was once unchallenged. Premium valuation in a market that just handed the Philadelphia Semiconductor Index its worst eight-day streak since 2008 adds to the vulnerability.
What Would Change the Picture
The key number to watch is procedure volume growth, specifically whether Q3 maintained anything close to the 16% pace of Q2. System placements matter second. And then gross margin: management kept full-year 2026 non-GAAP gross margin guidance at 68% to 69% after Q2, with the company noting tariffs as an ongoing factor. Holding that range in Q3 would help confirm the operating leverage the bull case requires.
UBS maintains a Buy rating with a $500 target. The consensus average across 22 analysts sits near $499. At $426, the implied upside is roughly 17%.
The Bottom Line
Intuitive Surgical is not cheap. It never has been. But the procedure flywheel, da Vinci 5 adoption, and Ion expansion represent a compounding growth engine that few medical device companies can match. Tuesday’s report is the next test of whether the business momentum can outrun a 49x multiple.