November 1, 2026
Bonus Content: CoreWeave’s Bonds Are Pricing Distress. Its Stock Hasn’t Caught Up.
Hey Trader,
There’s a 1-hour trade strategy that’s quietly grown into a revolution over the past few years…
Spreading from coast to coast.
Retirees are using it.
Active traders are using it.
And once people see how fast it works, they don’t shut up about it.
It’s the brainchild of our top trader, Dave Aquino.
And in about 60 minutes, Dave’s trading strategy delivers potential payouts like:
$500.
$563.
$625.
No marathon trading days.
No reckless bets.
No complex charts.
Just a focused window of opportunity… and a smart way to trade it.
See how this 1-Hour trade works right here.
Don’t work harder – trade smarter,
Drew Day
Founder & CEO
Base Camp Trading
CoreWeave’s Bonds Are Pricing Distress. Its Stock Hasn’t Caught Up.
The credit market moved first. Equity investors are still negotiating the implications.
The Wall Street Journal reported Friday that CoreWeave (CRWV), Nebius Group (NBIS), and Nscale have effectively been shut out of the bond market in recent weeks as lenders demand stricter terms. Neoclouds that rely on debt to build computing power have been barred from new issuance, while even strong companies like Broadcom have had to offer better terms to secure loans. That is not a single-name credit event. It is a structural shift in how investors are willing to finance the GPU-leasing model.
The Numbers Behind the Shutdown
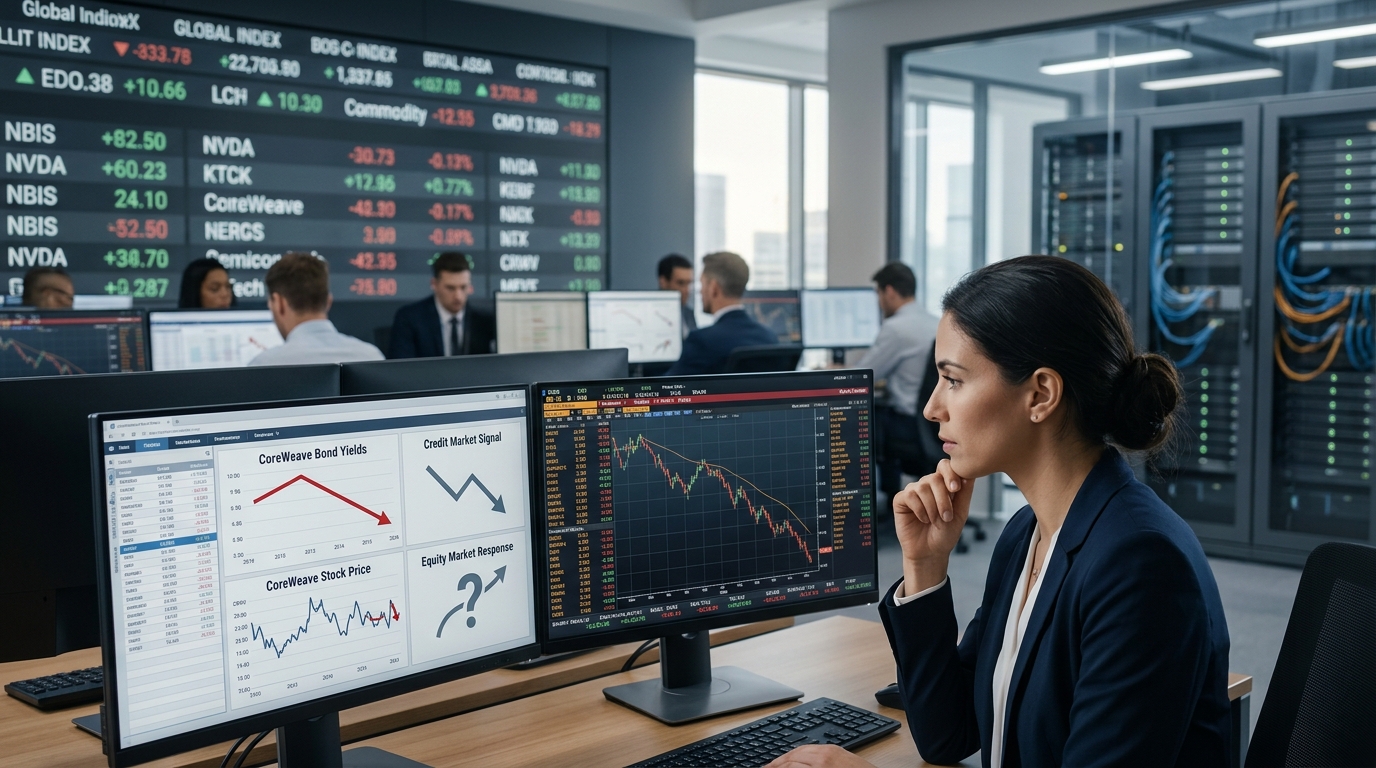
CoreWeave’s 9.75% coupon bonds now trade at secondary market yields around the mid-teens. Its credit default swaps have traded above 1,000 basis points, levels usually associated with distress. Bankers have noted in recent weeks that the high-yield debt market for new cloud vendors is essentially closed to new issuances, with yields in the mid-teens being prohibitive for many borrowers.
The maturity wall makes the timing acute. The nearer-term pressure is the clustering of debt that comes due and must be repaid or refinanced. For CoreWeave, the combined wall is roughly $10.6 billion: approximately $4.4 billion due by the end of 2026 plus approximately $6.2 billion in 2027. Q2 interest expense ran at $640 million for a single quarter, driven by increased debt to support infrastructure scaling.
Nebius faces a structurally different but parallel problem. On October 22, Nebius disclosed a $3.5 billion senior secured financing facility arranged by Citi, with proceeds earmarked for data center development, GPU procurement, and general corporate purposes. The facility has a 364-day maturity. The tighter credit market has shifted the yardstick: it is not only the business promised that counts, but whether it can be financed into existence. NBIS has shed roughly 33% in October, closing Thursday at $154.14 against a 52-week high of $299.86.
Equity Valuations vs. the Credit Signal
CRWV closed October 30 at $54.87, down 9.66% on the session, with a market cap of $30.26 billion. The 52-week range spans $51.24 to $138.36. For full-year 2026, management guided to $12.4 billion to $13.2 billion in revenue and $960 million to $1.15 billion in adjusted operating income. Revenue backlog reached $104.2 billion, up 246% year over year. The demand argument is real. The financing argument is now equally real, and the bond market is saying the two cannot coexist at current capital costs.
Analyst consensus carries a 12-month price target of $134.58 for CRWV, implying 145% upside from current levels. That target was built when bond markets were open. With secondary yields around the mid-teens on the 9.75% senior notes, the refunding math is broken unless the primary market reopens at materially tighter spreads. Equity bulls are essentially pricing a credit recovery that hasn’t started yet.
The Nvidia Linkage
The clean-hands argument for Nvidia (NVDA) is getting harder to sustain. As Nvidia has become more directly entangled in the AI infrastructure build-out, some investors see the company taking on outsized risk tied to the funding chain behind the GPU cycle, and those concerns are showing up in the market with neocloud shares selling off and bond yields rising. NVDA fell 4.22% on October 30 to $204.64, with a 52-week range of $164.27 to $243.37. The all-time closing high of $239.24 was set on October 6, 2026. NVDA is now roughly 14% off that peak, sitting just above its 200-day trend, with earnings due November 17.
Oracle (ORCL), by contrast, announced last week that Google’s Tensor Processing Units will be available through Oracle Cloud Infrastructure, marking the first time Google TPUs will be offered on a hyperscale cloud platform outside Google. Oracle expects to raise $45 to $50 billion in gross cash proceeds during 2026 through a combination of debt and equity financing, with the explicit goal of maintaining a solid investment-grade balance sheet. The investment-grade label is exactly what the neoclouds cannot claim, and the spread between the two cohorts’ cost of capital is now the trade.
Structural Context
Gartner warned in mid-October that more than $3.5 trillion of AI infrastructure spending could be exposed to impairment by the end of 2030 if AI providers continue their current pace of capital spending. By 2030, Gartner predicts that cost pressure and a lack of a differentiating business model will force over 80% of neocloud providers to cease independent operations. Elon Musk sharpened that view publicly, saying more than 200 neocloud companies could collapse. His stated rationale: debt markets have almost entirely shut off access to money for any company that doesn’t have substantial revenue independent of AI data centers.
Scenario Modeling
Bull Case. The primary bond market for neoclouds reopens in Q1 2027 as the Fed signals rate cuts. CoreWeave refinances its 2026-2027 maturity wall at sub-12% all-in yields. Nvidia’s November 17 earnings confirm demand acceleration, CRWV recovers toward the $80-$90 range, and NBIS reclaims $200.
Base Case. The bond market stays closed through year-end. CRWV and NBIS trade sideways to down 10-15% as equity investors price in higher dilution risk from emergency equity raises. NVDA holds $200-$215 as hyperscaler capex remains robust but neocloud contagion keeps a ceiling on the multiple. The CDS spread on CRWV stays above 900 basis points.
Bear Case. CoreWeave’s maturity wall forces a distressed asset-backed refinancing at yields above 16%, triggering a secondary equity raise that dilutes current holders 20-30%. CRWV tests the 52-week low near $51. NBIS, with its 364-day Citi facility due for renewal, faces parallel rollover risk. NVDA sells off toward $180 if neocloud credit stress is read as a leading indicator of GPU demand destruction.
Active Trader Strategy Framework
CRWV is trading near the bottom of its 52-week range and below its 200-day simple moving average. The $51.24 level is the structural floor. A sustained close below that level would signal potential for a more severe unwind. On the upside, $65-$68 is the first resistance band where supply is likely to emerge from trapped long holders. Position sizing must account for a beta of 2.67, which makes CRWV one of the most volatile large-cap names in the market.
For NBIS, the $149-$150 zone marked the intraday low on October 30. Key support levels sit at $155.40, $152.06, and $148.27, with resistance at $162.53, $166.33, and $169.67. The credit spread on CRWV is the most reliable leading indicator for the group: watch the 9.75% senior note yield daily. If it compresses below 14%, the equity trade becomes more interesting. If it widens past 17%, the base case accelerates toward the bear case.
The core positioning idea is the long-short between investment-grade AI infrastructure (ORCL, and hyperscalers) and the neocloud cohort. The bond market has already established that trade’s rationale. The equity market is still catching up. Manage risk around NVDA’s November 17 earnings as the binary catalyst that determines whether this is a sector rotation or something wider.
Preparation, not prediction, is the edge here. The credit signal is unusually clear. The question is whether the equity market’s lag is an opportunity or a warning.