November 1, 2026
Bonus Content: The Fed Is Pricing One More Hike. Logan Says Two. That Gap Has a Cost.
Former tech executive Jeff Brown, the man who picked Nvidia in 2016, before it jumped as high as 37,800%, just got inside a Cybercab, Elon Musk’s new car that has no steering wheel or pedals… and what happens will shock everyone. Click here to see the details or read more below.
Dear Reader,
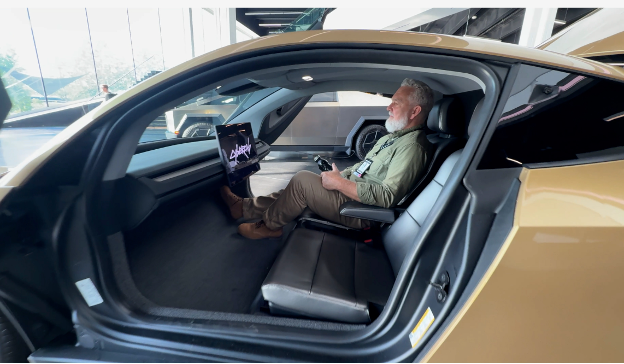
This man you see below just got inside a Cybercab…
Elon Musk’s new car that has no steering wheel…
No gas or break pedals…
And no rearview mirrors.
You won’t believe what happened next.
Click here to see this exclusive Cybercab footage
And get the details on why Elon is predicting his next move could help unleash $320 trillion in new wealth…
And how you could claim your piece of that pie.
Regards,
Lindsey Hough
Managing Director, Brownstone Research
The Fed Is Pricing One More Hike. Logan Says Two. That Gap Has a Cost.
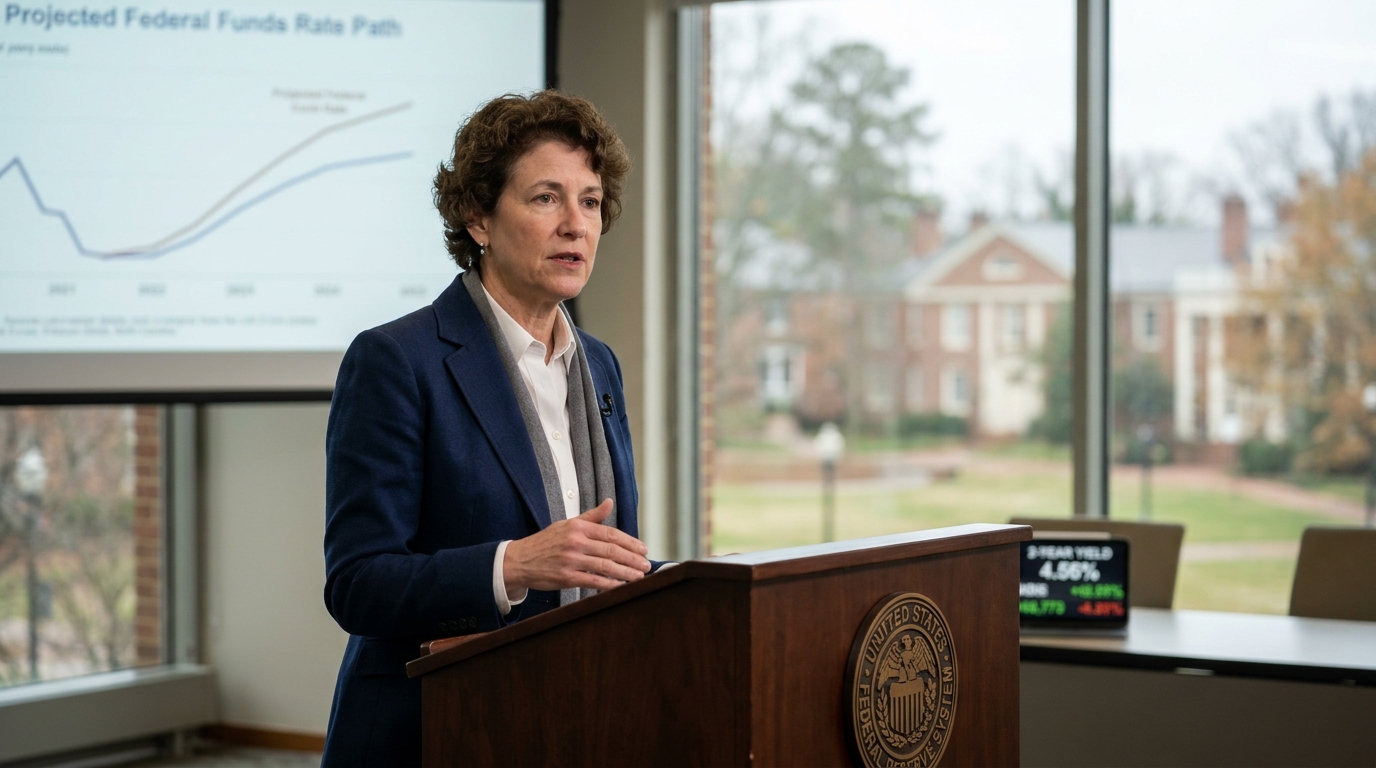
The question coming out of the October FOMC meeting was never really about December. It was about where rates stop. Dallas Fed President Lorie Logan answered that on Friday, and her answer does not match what the curve is pricing.
What just happened: Logan, in prepared remarks for Davidson College students, said the FOMC “needs to implement at least two more 25-basis-point rate increases.” She added that, given her current outlook, she estimates the target range needs to rise an additional 50 basis points or more. That is not a December binary. That is a path that runs through at least Q1 2027.
The Backdrop
The Fed voted to keep the overnight funds rate at 3.75% to 4.00% on October 28. Two of the 12 voting members dissented: Governor Lisa Cook and Cleveland Fed President Beth Hammack, both of whom preferred a quarter-point hike. Logan voted with the majority but wasted no time framing the hold as tactical rather than directional. She said skipping a meeting “does not change the monetary policy destination.”
The data supporting her view is hard to argue with. Real GDP grew 3.4% annualized in Q3 2026, and core PCE inflation was 3.1% year over year in September. Compared with August, headline PCE rose from 3.4% to 3.6%, while core PCE rose from 3.0% to 3.1%. An economy running at 3.4% real growth with core inflation still above 3% is not an economy demanding relief.
Where the Gap Lives: The 2-Year vs. Logan’s Terminal
As of October 30, the 2-year Treasury yielded 4.56% and the 10-year yielded 4.94%, with the fed funds target at 3.75% to 4.00%. Futures markets, as of this week, are pricing one hike in December with meaningful but not dominant conviction.
That is a single move. Logan is describing two. The mismatch between a 2-year yield at 4.56% and a policy destination of 4.50% or higher compresses the carry available in short duration and extends the duration risk in any position that fades the hawks. Every basis point the curve refuses to price carries a cost in mark-to-market exposure for long bond holders.
The compression in carry has a parallel in other rate-sensitive assets. Rising real yields set the opportunity cost across every asset that pays nothing or yields less than Treasuries, a mechanic that extends well beyond the bond market.
The 10s to 2s spread stood at 38 basis points on October 30, a still-modest positive slope that offers little compensation for taking on the path risk Logan is now describing openly.
The Hawkish Chorus
Logan is not alone. St. Louis Fed President Alberto Musalem said “additional firming of monetary policy will be necessary, and soon,” in prepared remarks for a Shadow Open Market Committee meeting in New York. Logan will be among the Fed officials voting on the rate decision in December. Musalem’s voting status rotates from year to year, and he was not a voting member for the October 2026 decision. That distinction matters: Logan’s words carry direct committee weight through year-end.
During remarks at Davidson College, Logan said it is “unacceptable” that inflation has exceeded the Fed’s 2% target for nearly six years. With core PCE at 3.1% and headline PCE at 3.6%, the data gives that language teeth.
Scenario Framework
Bull Case (Rates Peak at December Hike): October CPI, due November 10, prints at or below 2.6% on core, and October payrolls on November 6 show meaningful deceleration in wage growth. The curve shifts toward a single-hike terminal near 4.25%, and the 2-year rallies 15 to 20bp from current levels. Logan dissents or softens guidance at December.
Base Case (December Plus One More): December delivers a 25bp hike to 4.00% to 4.25%, November data keeps the door open, and the February 2027 meeting becomes live. The 2-year drifts toward 4.75% to 4.85%, and the spread between the 2-year and 10-year compresses or inverts modestly. Duration underperforms carry through Q1.
Bear Case (Logan’s Full Path Prices In): October CPI surprises to the upside, payrolls remain tight, and the FOMC delivers back-to-back hikes in December and February. The 2-year pushes toward 5.00%, the 10-year tests 5.25%+, and the long end shifts materially. October CPI on November 10 and October NFP on November 6 are the key data gates before the December 8 to 9 decision.
The November 10 CPI is not the first time a single inflation print has carried this much committee weight. Fed governors have already shown they can move in opposite directions inside the same week when inflation data arrives at a live meeting.
Active Trader Considerations
The asymmetry here sits in short duration. If the market is pricing one hike and Logan is arguing for two, any data confirmation of her view creates a rapid repricing event in 2-year Treasuries. Traders running duration-neutral positions should audit their 2-year exposure specifically. On the equity side, rate-sensitive sectors including utilities and REITs remain structurally vulnerable in a two-hike path. Monitor the November 6 payroll release and November 10 CPI as the sequenced catalysts that either validate or challenge Logan’s terminal rate framing before December 9.
Preparation, not anticipation, is the edge here. The path is contested. Position sizing should reflect that uncertainty, not resolve it prematurely.