November 3, 2026
Bonus Content: Costco Is Spending $7.5 Billion for 33 Warehouses. The Real Test Is Returns.
Hello, my name is Marc Lichtenfeld.
And thanks to an obscure tax loophole (on page 1,794 of the U.S. tax code) …
Regular investors can collect payouts from what I call “SpaceX Royalty Shares.”
In this video, I show you everything, including:
How YOU can collect huge payouts…potentially thousands of dollars more… (depending on the size of your stake…)
Why JP Morgan increased its stake in “SpaceX Royalty Shares” by over 22X!
The easiest way to INCREASE your payouts – without investing any additional money!
And WHY you must hurry if you want to participate… The cutoff deadline for the next payout is November 18…
To find out more…
Watch my full “SpaceX Royalty Shares” briefing now.
Good investing,
Marc Lichtenfeld
Chief Income Strategist, The Oxford Club
P.S. I’ve already shown over 150,000 Americans how to start collecting consistent payouts from investments just like this…
Including Dean B., who grew his portfolio from $300,000 to $1.3 million in four years and is now collecting $75,000 per year in payouts…
Hurry! The cutoff deadline for the next payout is November 18…
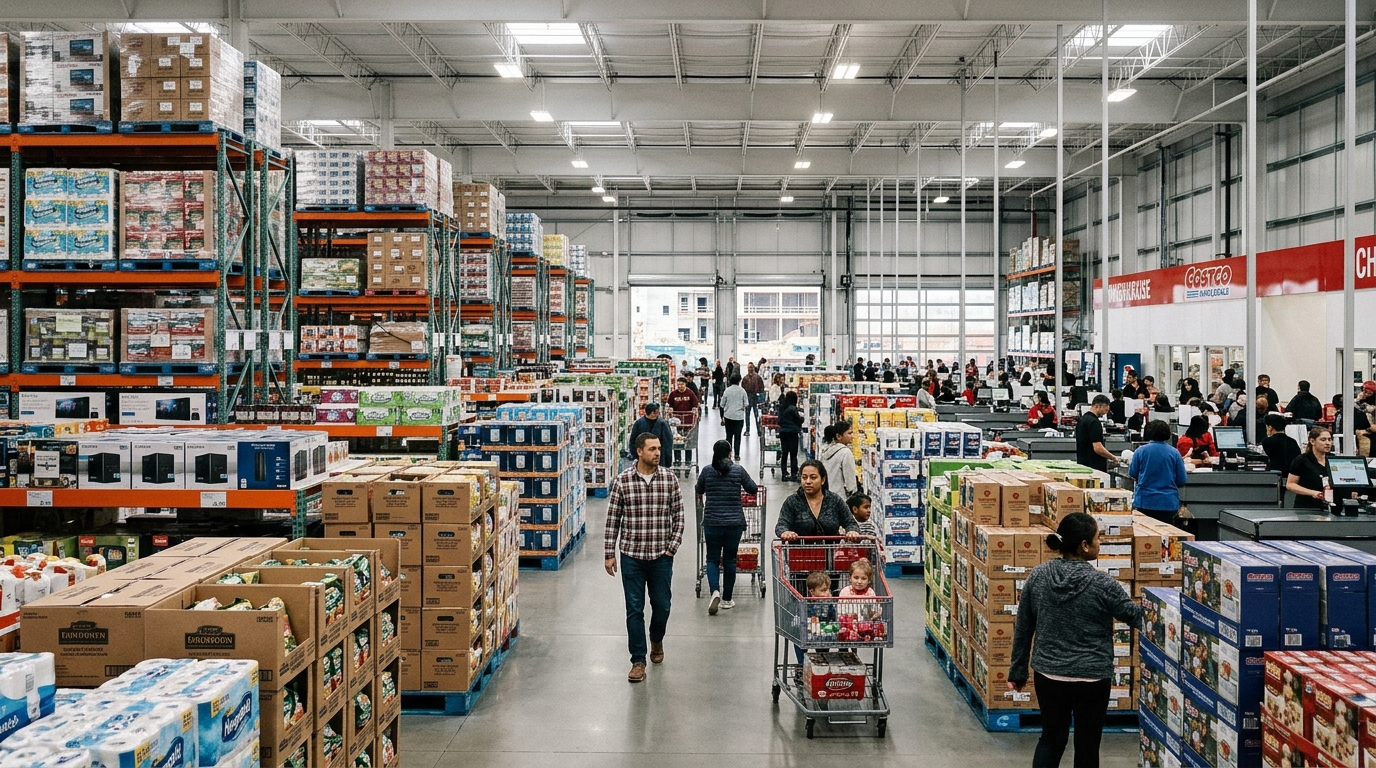
Costco Is Spending $7.5 Billion for 33 Warehouses. The Real Test Is Returns.
Near $1,000 a share, Costco is priced for perfection. The question active traders need to answer right now is not whether the business is good. It demonstrably is. The question is whether a 17% jump in capital spending produces returns that justify a roughly 49x trailing earnings multiple.
The Capex Surge in Numbers
Costco’s fiscal 2027 capital budget sits at about $7.5 billion, up from $6.435 billion in fiscal 2026, as management targets up to 33 warehouse openings including five relocations. CEO Ron Vachris has anchored the company to a five-to-ten-year run rate of about 30 net new warehouses annually. Management has also indicated capex growth slows after fiscal 2027, but that qualifier is only as good as the new-unit economics underneath it.
Fiscal 2026 delivered strong cash generation. Free cash flow rose about 19.7% to roughly $9.38 billion, and Costco ended fiscal 2026 with $21.301 billion in cash and cash equivalents plus short-term investments. The balance sheet can absorb the spend. The problem is what happens next: some Street models still assume a sizable free cash flow decline in fiscal 2027 as the capex draw peaks. At this price level, COST also trades at a premium multiple on free cash flow, which leaves less room for execution slippage if the new-unit ramp is slower than expected.
The Return-on-Capital Test
Costco’s ROIC is commonly estimated in the high teens, so the spread versus an estimated high-single-digit WACC is still comfortably positive. Fiscal 2026 net income rose 14% to $9.226 billion on net sales of $297.247 billion. Membership fee revenue grew 11% to $5.907 billion, with U.S. and Canada renewal rates at 92.3%. These are the structural buffers that let management write a $7.5 billion capex check with credibility.
But invested capital has been rising quickly as the footprint and supply chain expand. Each new warehouse must generate strong member acquisition, traffic, and per-location sales just to hold ROIC steady. If the 33 new units land below the system average, that spread narrows precisely when the stock is priced at a rich forward multiple.
Scenario Framework
Bull case: New warehouses open near system average productivity, membership fee income continues compounding above 7%, and any free cash flow trough proves shallow and brief. COST retakes about $1,068 (a current consensus target) and the premium holds.
Base case: Free cash flow dips as modeled, new-unit ramp takes two to three quarters longer than management expects in a tighter real estate environment, and the stock consolidates in the $950 to $1,020 range through December’s fiscal Q1 2027 report.
Bear case: Any combination of weaker comparable sales, LIFO charges (the Q4 fiscal 2026 LIFO charge rose to $152 million from $43 million a year earlier), and slower member growth forces a multiple reset toward 40x forward earnings, implying downside toward $910.
The multiple-reset scenario depends partly on whether the consumer holds up. Walmart’s comparable-sales line is one of the clearest real-time reads on whether middle-income households are sustaining spending on necessities.
What Traders Should Watch
The December fiscal Q1 2027 report is the first scoreboard check. Capex spending for the quarter, measured against the roughly $7.5 billion annual plan, is the number to track. If the first quarter alone exceeds $2 billion with limited new openings to show for it, the market will start asking whether the buildout timeline has slipped. Membership fee growth and Executive member penetration, at 42.3 million paid Executive members and about 75.2% of net sales, are the defensive metrics that anchor the premium. If either softens, the valuation math gets harder fast.
Preparation here means knowing your levels and your thesis. A stock priced at a premium multiple is not a position that forgives reactive decision-making.