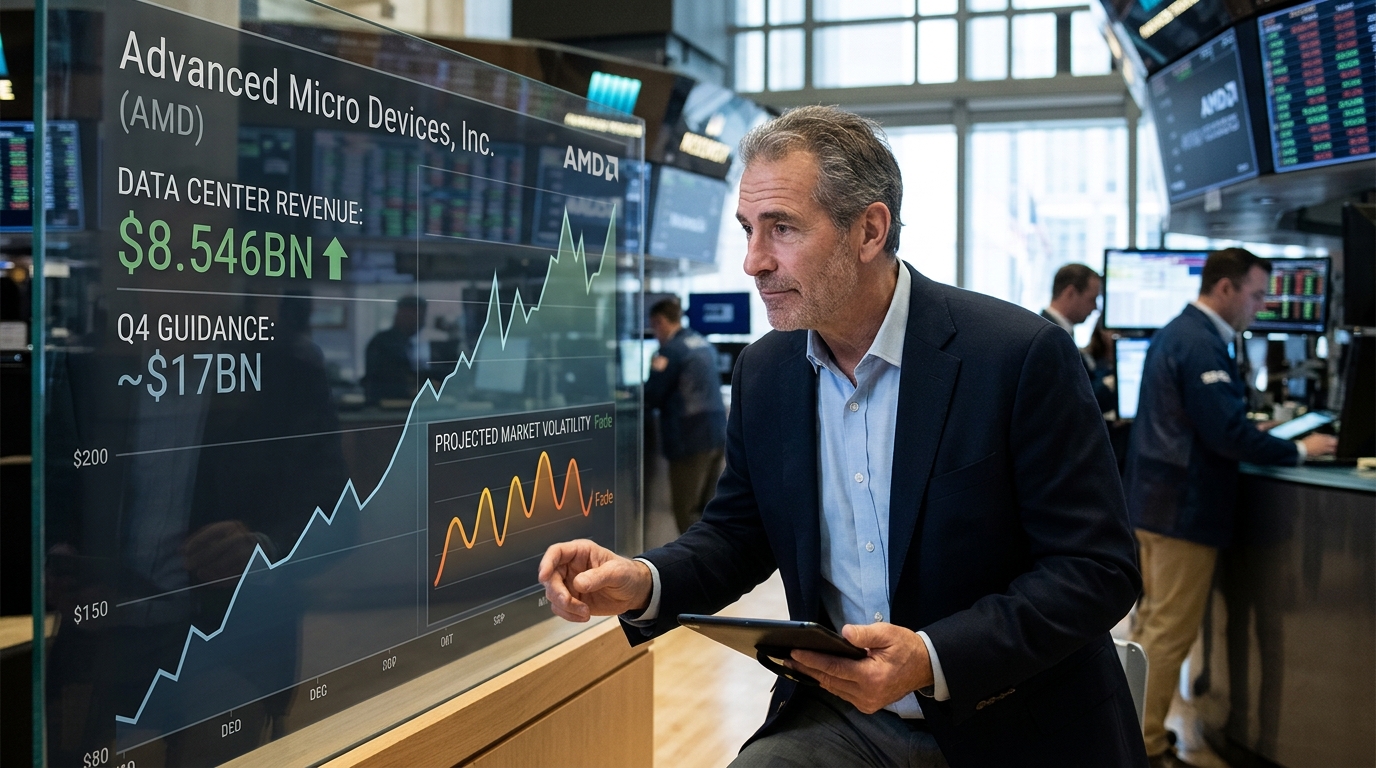
- Q3 revenue: $13.377bn, +45% YoY
- Data Center segment: $8.546bn, +97% YoY, +27% sequentially, about 64% of total revenue
- Non-GAAP diluted EPS: $2.09
- Q4 guidance: approximately $17bn (±3%), implying ~66% YoY growth and ~27% sequential growth at the midpoint
- Inventory increased approximately $3bn sequentially to $11.5bn, per management on the earnings call
- After-hours range: $475.07 to $530.38; last after-hours print shown at $508.20
- Key levels heading into the open: $466 support, $520 resistance, $560 bull case marker
Market Context
AMD reported Tuesday evening into an already pressured backdrop. Concerns about AI spending durability had battered semiconductor sentiment through October, and AMD entered earnings down sharply over the prior month.
The Nasdaq Composite closed up 0.83% on November 3, 2026, as chip stocks rebounded. Overnight, U.S. index futures turned volatile as the election outcome came into focus. The 2026 midterm elections delivered Democratic control of Congress, setting up a new round of macro headline risk into today’s open.
Sector Breakdown
AMD’s data center strength sparked an after-hours bid across the complex, with sympathetic strength in large-cap AI bellwethers and infrastructure names. The read-across is straightforward: a clean data center quarter from AMD helps stabilize sentiment around near-term AI demand. The harder question is whether election-driven policy uncertainty changes sector-level risk tolerance at the open, overwhelming stock-specific momentum from an objectively strong quarter.
AMD: What the Numbers Actually Say
The Data Center segment generated $8.546bn in revenue, up 97% YoY and 27% sequentially, with AMD attributing the surge to strong EPYC demand and the launch of Instinct MI450 Series GPUs. Data Center operating income was $2.882bn versus $1.074bn a year ago, and the segment operating margin expanded to 34% from 25%.
On the call, Lisa Su said Q4 will be the quarter that data center AI revenue surpasses server CPU revenue for the first time. Management also said it expects server revenue to double year over year in 2027, with data center representing more than 80% of total company revenue in 2027.
Against consensus expectations circulating into the report, AMD guided Q4 revenue to approximately $17bn (±3%). At the midpoint, AMD said that implies about 66% year-over-year growth and about 27% sequential growth.
The complication: inventory increased approximately $3bn sequentially to $11.5bn, which management tied to fulfilling strong data center demand. If shipments land on schedule, working capital normalizes; if demand or timing slips, the inventory line stays a risk variable for active traders.
Inventory risk in AI hardware is not unique to AMD. Micron has moved to lock in customers through take-or-pay contracts extending to 2031, a structural answer to exactly the demand-timing uncertainty AMD’s inventory line raises.
Technical Framework
AMD’s after-hours tape showed a high of $530.38 and prints down to $475.07, with $508.20 displayed as the last after-hours price. The near-term issue is whether the stock can hold reclaimed levels after the initial earnings reaction.
$520 remains the first clean resistance zone on the tape. On the downside, $466 is still the key support reference. A decisive failure through that level would shift the short-term structure and puts the next downside air pocket into focus. Volume confirmation matters: a high-volume open that holds reclaimed levels is structurally different from an early spike that reverses on expanding sell volume.
Scenario Modeling
Bull Case: $560
Index futures stabilize, targets move higher on the ~$17bn guide, and AMD reclaims its prior breakout zone. The inventory build is absorbed by Q4 shipments, and segment margin holds the 34% area, supporting a higher multiple into year-end positioning.
Base Case: $505 to $520 consolidation
AMD holds most of the after-hours move but chops between $505 and $520 as the market digests the quarter alongside macro headlines. Inventory and policy uncertainty cap multiple expansion, keeping price action range-bound until traders get clearer shipment and capex reads.
Bear Case: $466
Macro pressure deepens at the open and the earnings move fades into a full gap fill. Any softer-than-expected hyperscaler commentary in coming weeks tightens risk appetite further. If Q4 revenue trends toward the low end of guidance, the $11.5bn inventory line becomes a recurring headline risk.
Macro pressure on chip stocks is not a new variable this cycle. The Philadelphia Semiconductor Index dropped roughly 19% from its June high as broader market stress overwhelmed stock-specific fundamentals across the complex.
Active Trader Strategy Framework
The key variable is not the fundamental result. That was clean. The key variable is whether election-related sector pressure resolves within the first 60 minutes of trading. Watch $500 as the first decision point: a hold above it on declining sell volume is structurally different from a fade through it on expanding volume.
Position sizing should reflect that AMD can move fast around earnings. Traders leaning into volatility should anchor risk to the $466 level, where a daily close below that threshold materially changes the short-term structure. Those already long from lower levels should monitor the $520 to $530 zone as a measured objective, not a reason to add risk.
Conclusion
AMD’s Q3 is not the debate. A 97% data center revenue gain, $2.09 in non-GAAP diluted EPS, and a ~$17bn Q4 guide is an objectively strong quarter by any measure. The debate is whether a macro dislocation driven by election outcomes has created a tradable gap between fundamentals and price, or whether inventory risk and policy uncertainty around AI infrastructure justify a wider discount. Those two questions tend to resolve around the same levels traders are already watching: $466 and $560.