November 5, 2026
Bonus Content: SMCI Beat Earnings. The Stock Is Still Down 31% in a Month.
The U.S. Military Has Painted Itself Into a Dangerous Corner…
And Only One $5 Stock Can Fix the Problem
Dear Reader,
It seems like the U.S. military has painted itself into a dangerous corner.
Starting January 1st… a hard deadline takes effect.
A Pentagon-issued deadline that will ban Chinese-sourced materials from every weapon America builds.
The problem is…
China currently supplies 90%+ of these metals to the entire world.
Chinese-sourced materials are in every Tomahawk missile.
Every military drone and satellite.
Every night-vision goggle our soldiers wear into battle.
A single F-35 uses about 900 pounds of these critical materials, and one nuclear submarine needs almost five tons.
It’s a major bottleneck…
Without them, America’s defense industry could grind to a halt.
But Trump has a $16 Trillion Chess Move that practically nobody will see coming.
A move he could deploy any day now.
In fact, I just received an OVERNIGHT FedEx envelope from a former CIA insider… a man who knows Donald Trump personally.
Inside is the executive order Trump signed that lays out his entire plan.
Click here to see for yourself…
It might be the most important document he has ever signed… not just for America, but for savvy investors who connect the dots.
They could see gains as high as 1,000% before his second term is over.
Because… at the center of it all is one small company you can buy today for about $5 a share.
Regards,
Matt McCall, Head Innovations Strategist
Monument Traders Alliance
P.S. The last time Trump backed a company like this, its stock shot up 407% in a single week. With January 1st closing in, I want you in position before Trump makes his move. Click here for the details.
SMCI Beat Earnings. The Stock Is Still Down 31% in a Month.
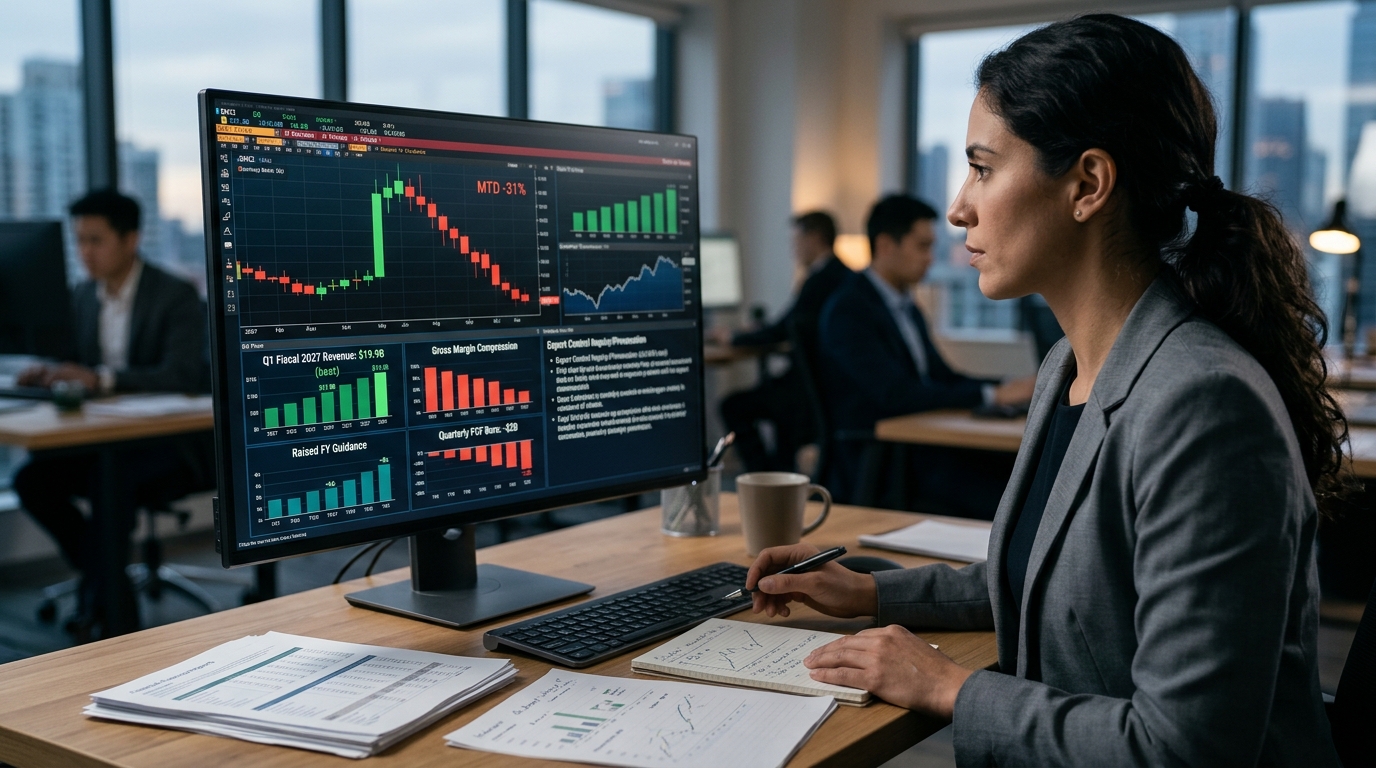
Super Micro Computer delivered a quarter that would have sent most technology stocks into orbit. Q1 fiscal 2027 revenue of $19.9 billion came in 298% above the prior year and cleared the company’s own pre-announced ceiling of $19.5 billion. Non-GAAP diluted EPS of $1.81 beat the $1.28 consensus by 41%. Management then raised full-year revenue guidance to a range of $72 billion to $82 billion. By any headline metric, the numbers were emphatic.
SMCI is trading near $27 today. The stock has shed 31% over the past month alone.
The disconnect is not a mystery. Three separate forces are eroding the case for the valuation to re-rate higher, and cheap optics on a P/E screen are not sufficient to override them.
The Margin Problem Is Structural, Not Seasonal
Gross margin came in at 12.8% in Q1, which cleared internal guidance but landed below the Q4 fiscal 2026 reading of 17.5%. Management guided Q2 to 12.0% to 12.5%, and the full-year shape implies further margin compression in the second half. Bank of America kept an Underperform rating and raised its price target only to $39 from $38, a signal that at least one major desk sees the margin trajectory as the binding constraint.
The Cash Drain Is the Bigger Red Flag
SMCI’s net cash used in operating activities for fiscal year 2026, ended June 30, was negative $6.81 billion. Working capital requirements scaled with revenue at a rate that consumed every dollar of profit and then some. Total debt hit $8.7 billion at fiscal year-end. Total current liabilities were $7.16 billion. Cash and cash equivalents were $7.52 billion at fiscal year-end.
Revenue growing at 77.8% annually sounds compelling until working capital absorbs it in full.
The Legal Overhang Has a Co-Founder’s Name on It
An indictment unsealed on March 19, 2026 named Super Micro co-founder Yih-Shyan “Wally” Liaw and two others in an alleged scheme to export AI servers to China in violation of U.S. controls. Reuters reported on Oct. 9, 2026 that a contractor linked to the company pleaded guilty in Manhattan federal court. The company has said operations have not been disrupted, but any escalation that restricts sales or triggers broader government scrutiny carries asymmetric downside.
The export-control risk also has a supply-chain dimension worth tracking. Jabil, which builds AI server hardware for three hyperscale customers, sits directly in the same data-center supply chain that any SMCI disruption would reroute.
How Traders Should Frame the Levels
SMCI’s 52-week range runs from $19.48 to $51.40. At $27, the stock is 43% off the top. The forward P/E sits near 6.4x, and the consensus analyst target is $43.27, implying more than 60% upside from today’s price. Rosenblatt’s $57 target is based on 9x fiscal 2027 earnings. The bull case requires margin stabilization in Q2 and Q3, the export-control case remaining contained at the individual level, and no disruption to the $60-billion-plus order backlog.
The base case is a range-bound stock, with $25 as the technical floor and $35 as resistance until a gross margin print above 14% offers the market a reason to re-rate. The bear case is a formal government action against the company itself, a scenario the 10-K explicitly names as a possibility.
Discipline here means watching the Q2 gross margin print in February before accepting the valuation discount as genuine rather than earned. A cheap multiple is only an opportunity when the denominator stops shrinking.