There is a monetary shift building that retirement savers will not see until it has happened.
Almost every retirement account in America is held in dollars.
But what your account is really worth is not the number on the statement. It is what that number can buy.
And since 1971 when Nixon cut the tie between the dollar and gold, this number is buying less every single year.
You feel it at the pump. You see it at the cash register.
Your savings have been running uphill against that erosion for more than 50 years.
Now Congress is taking a second look at the gold the government owns.
And a bill in Congress would require the Treasury to reprice the government’s gold on its books, at market value.
Here is why it matters to you.
The government values its own gold at $42 an ounce. Congress set that price in 1973 and never changed it.
Gold trades at over $4,000 today.
America holds more gold than any country on earth. On the books, it is worth about $11 billion. In the real world, more than $1 trillion.
That is a gap of about 95 times, sitting on the nation’s books, in plain sight.
And Washington has noticed. That is what the repricing bill is.
If that number is ever corrected, Washington books a trillion-dollar gain. From gold.
The Americans who already hold physical gold did not wait for Washington to notice.
More than 60 million Americans qualify to move a portion of their savings into physical gold right now. Tax-free. Penalty-free.
The 2026 Gold Guide walks through every step.
Takes 30 seconds to request.
Nixon made his move on a Sunday night. No warning.
If it changes again, the only question is which side you are standing on.
Japan’s Economy Just Shrank. Here’s What Traders Need to Know Before December.
The Gap That Matters
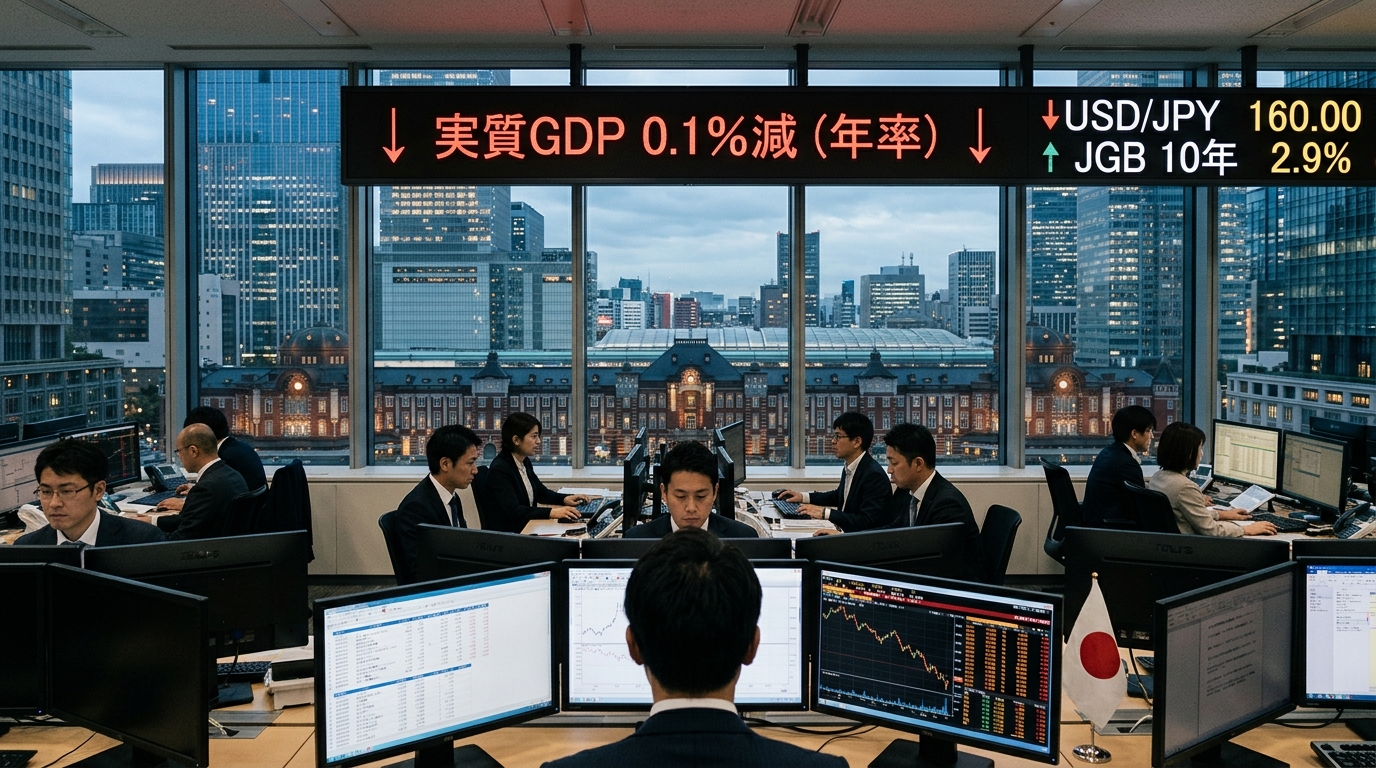
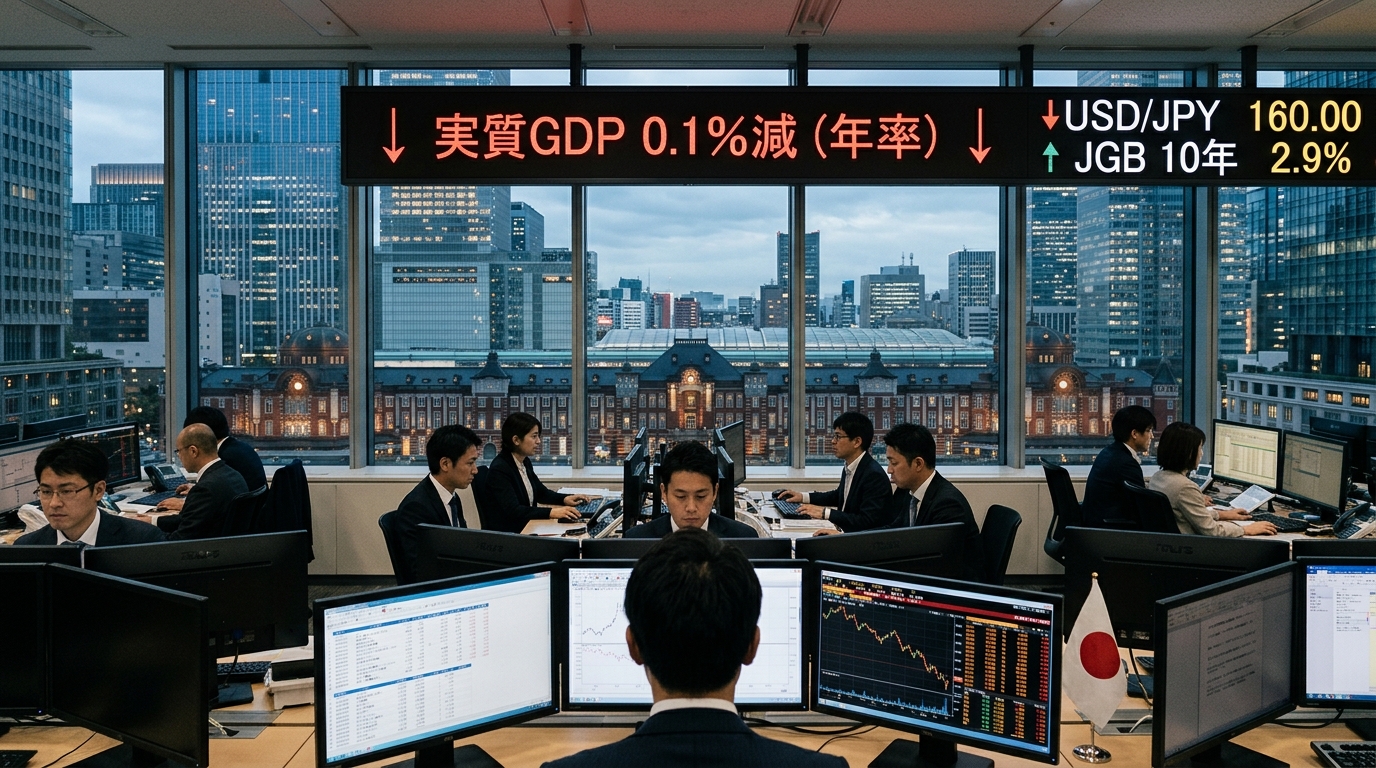
Japan’s Cabinet Office reported this morning that real GDP contracted at an annualized 0.1% in Q3 2026, the first negative quarter in four, and a full 40 basis points south of the +0.3% Reuters consensus. The Nikkei 225 gave back 2.4%, not 1.6%. That is the headline. But the gap between a recession-flirting GDP reading and a market that only sold off 2.4% is precisely where the trade lives.
What the Data Actually Says
The contraction was overwhelmingly a trade story. Net exports subtracted 0.6 percentage point from growth as imports surged 2.5% while exports of goods and services fell 0.2%. Private consumption dropped 0.3% for a second straight quarter, pressed by elevated prices and weather-disrupted summer spending. The offsetting factor: capital expenditure rose 1.6%, and domestic demand contributed a positive 0.6 point.
The GDP deflator came in at 2.4% year-on-year. That detail is not trivial. Several analysts, including Capital Economics’ Marcel Thieliant, argue that weak consumption is itself a symptom of elevated prices, which strengthens rather than undermines the case for further rate normalization.
The BoJ December Calculus
The Bank of Japan held its policy rate at 1.25% in October. Market-based estimates vary by model and data source, but futures pricing broadly implies better-than-even odds of a 25-basis-point move by the December 18 meeting. A Reuters survey of 78 economists found 54 expecting that December move.
The complication: the Fed is moving in the same direction. With the 10-year Treasury around 5.1% and the 10-year JGB around 2.9%, the roughly 225-235 basis point yield spread keeps carry trades leaning dollar-long, yen-short regardless of what the BoJ does.
Key Companies in the Frame
Toyota is the clearest lens on how the yen and domestic demand interact. Its fiscal first-half results, reported November 5, showed operating profit up 9.2% to ¥2.19 trillion on revenue up 9.5% to ¥26.96 trillion. The full-year operating profit forecast was raised to ¥3.9 trillion. At a trailing P/E near 9.7x, Toyota is cheap by any global auto standard, but a yen that stabilizes or firms from 160 compresses that earnings tailwind fast.
MUFG reported interim profits attributable to owners of parent of ¥2.8 trillion as its full-year earnings target for the fiscal year ending March 31, 2027, in materials dated November 13. Rising JGB yields structurally benefit MUFG’s net interest margin, making it one of the few Nikkei constituents that gains from a tighter BoJ path rather than losing from it.
Technical Framework
The Nikkei’s 200-day moving average sits several hundred points below current levels and was not seriously tested on today’s move. USD/JPY near 160 is the more urgent line: Japan’s Finance Ministry has previously flagged rapid, one-sided moves as problematic, and the market continues to treat the 160 area as intervention-sensitive. For JGBs, the 10-year around 2.9% is retesting the range established around the late-October highs, with 3.0% remaining the obvious psychological and volatility trigger for rates desks.
Scenario Modeling
Bull Case for Japanese risk assets: October CPI data, due November 20, comes in soft. December hike odds trim to 60-65%, the yen firms from 160 toward 157, and import costs ease. The Nikkei recovers its 2.4% loss within a week as rate-sensitive exporters stabilize. Level to watch: Nikkei holding 38,500.
Base Case: The BoJ hikes 25 basis points on December 18 as the Fed also hikes on December 9. The policy gap stays wide, the yen drifts in a 158-162 range, and the Nikkei consolidates between its 50-day and 200-day averages. MUFG outperforms domestically oriented names on margin expansion; Toyota guidance holds unless yen drops below 155.
Bear Case: Board dissenters block December action, the second GDP estimate confirms a deeper contraction, and yen weakness accelerates past 162. Import inflation reaccelerates, consumption deteriorates into Q4, and the Nikkei breaks its October low. JGB yields pushed higher by US rates breach 3.0%, forcing BoJ to address yield dynamics once again.
Active Trader Positioning Considerations
Three levels define the decision framework through December 18: USD/JPY 160, the JGB 10-year at 3.0%, and the Nikkei’s 200-day moving average. A yen that holds below 160 without intervention keeps the carry trade crowded and equity volatility contained. A breach of 3.0% on the JGB reopens structural questions about BoJ credibility that go well beyond this quarter’s GDP. Volatility around the November 20 CPI release and the December 8 second GDP estimate deserves positioning attention. Preparation matters more than the number itself.