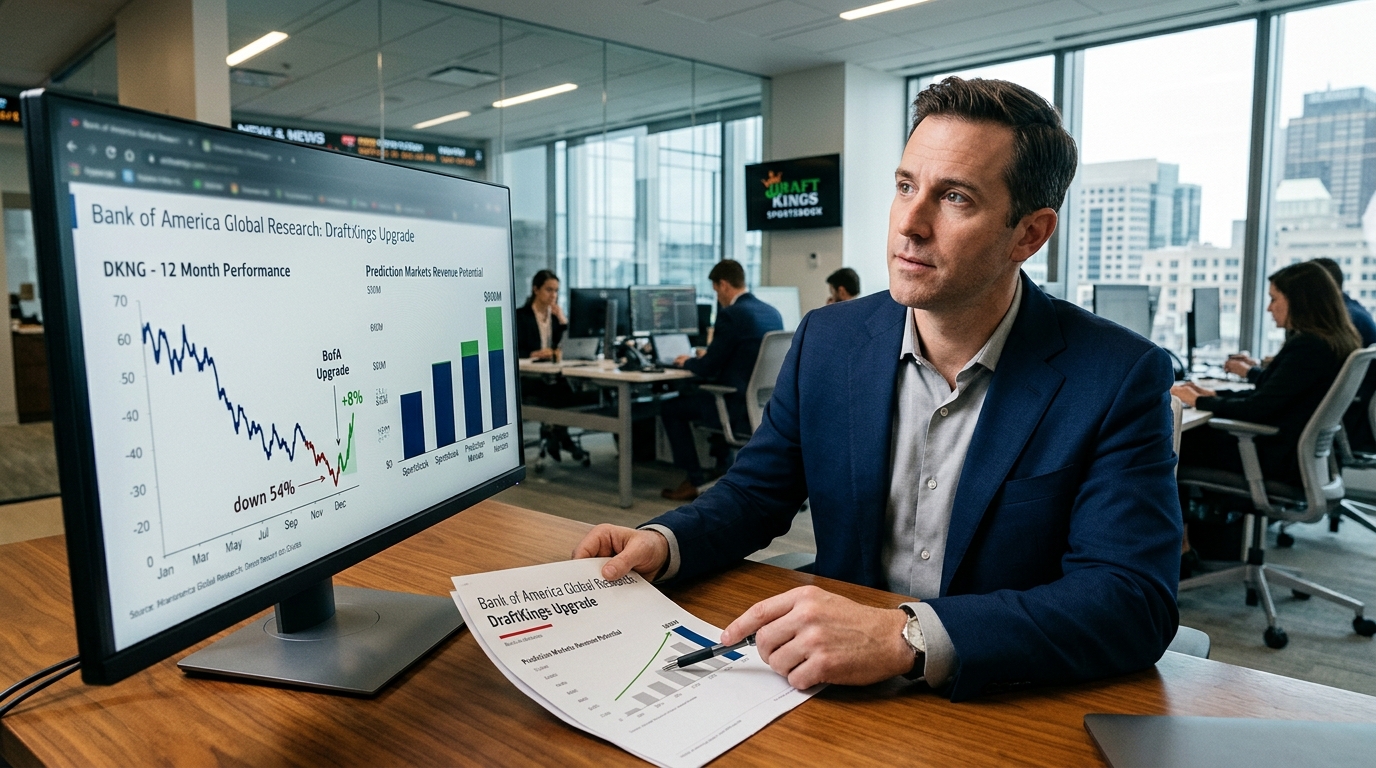
DraftKings shares jumped about 8% on Monday after Bank of America upgraded the stock from Neutral to Buy, setting a $27 price target and making one central claim: prediction markets are a second revenue engine, not a wrecking ball aimed at the core sportsbook.
That case matters because the stock badly needs one. DKNG had fallen roughly 54% over the past year before Monday’s move, weighed down by a brutal combination of unfavorable NFL outcomes, weaker-than-expected guidance, and persistent fear that prediction market platforms like Kalshi and Polymarket were poaching DraftKings’ customers. The analyst team at BofA called that selloff excessive, while flagging that stronger cost discipline will be needed to support higher margins beyond 2027.
The Business
DraftKings operates a vertically integrated U.S. online sportsbook, covering sports betting and iGaming across many states. It launched DraftKings Predictions in December 2025, a separate app letting users trade contracts on real-world sporting outcomes, and has since launched its proprietary prediction markets exchange, DKeX, with integration into the DraftKings: Sports & Casino app. The company offers sports event contracts in 18 states where it does not run its traditional sportsbook, keeping the two products largely on separate turf.
First-quarter 2026 revenue came in at $1.646 billion, up 17% year over year. Full-year guidance remains $6.5 billion to $6.9 billion in revenue, with adjusted EBITDA of $700 million to $900 million. That EBITDA midpoint disappointed Wall Street when it was set, but BofA’s upgrade rests on what 2027 could look like, not what 2026 has delivered.
Why Wall Street Is Paying Attention
BofA estimates prediction markets could generate about $400 million in fees for DraftKings in 2027, with a further $200 million to $400 million potentially coming from market-making activities. That is a combined range of $600 million to $800 million in incremental annual revenue from a business line that did not exist eighteen months ago.
The bank’s $27 price target implies roughly 38% potential upside from Tuesday’s price, based on a 12 times multiple of 2027 enterprise value to adjusted EBITDA, a modest discount to other leading disruptors. BofA raised its 2027 adjusted EBITDA estimate to $1.15 billion from $1.05 billion, reflecting stronger core trends and expected contributions from market-making.
The data on cannibalization has also started to shift in DraftKings’ favor. BofA pointed to early-season trends showing traditional sportsbooks growing faster than prediction markets, reducing concerns that the newer products will materially weaken DraftKings’ core business. DraftKings has said its own prediction market volume has risen to nearly 2.5 times its July level, helped by a stronger base coming out of World Cup-related activity.
What’s Driving the Opportunity
The regulatory angle is where BofA’s argument gets genuinely interesting. The analyst noted that DraftKings could benefit even if prediction markets were ultimately restricted, because removing the regulatory uncertainty would eliminate an overhang on the company’s valuation. Heads DraftKings wins a sizable new market. Tails the uncertainty discount in the stock simply goes away.
Citizens, which maintained a Market Outperform rating, cited a 15% increase in sports betting handle and prediction market volume running at about 2.5 times July levels. Stifel, maintaining a Buy at $36, noted 15% year-over-year growth in DraftKings’ online sportsbook handle during the initial weeks of the NFL season. Multiple banks are reaching the same conclusion: the sportsbook is not shrinking.
What Could Go Wrong
The honest counterargument starts with DraftKings’ position inside the prediction market itself. After NFL Week One, Kalshi captured 76% of prediction market volume versus DraftKings’ DKeX at roughly 3%. The company is the third-largest player in a fast-moving market where Kalshi and Polymarket have significant head starts. Catching up will cost money. BofA already lowered its 2026 adjusted EBITDA forecast from $625 million to $500 million because of higher investment in prediction markets.
There is also the November earnings date. DraftKings has not announced its next earnings date yet, but several calendars estimate it around November 5, 2026. If NFL outcomes run against the house or prediction market losses widen further, the upgrade thesis gets tested quickly. BofA’s 2027 EBITDA estimate of $1.15 billion requires the prediction market revenue ramp to actually materialize, which is still an assumption, not a result.
The Bottom Line
The stock has been punished as though prediction markets are an existential threat. BofA’s upgrade says they are an expansion opportunity with a regulatory backstop either way. At around $19.60 today with a 52-week high of about $36.98, the market’s skew is still pessimistic. A move to BofA’s $27 target is achievable if the NFL season data keeps validating what the sportsbook numbers already suggest: that bettors are not choosing prediction contracts over traditional wagers, they are doing both.
For investors willing to hold through November’s earnings, DKNG offers an unusual combination of a deep reset in expectations, a live catalyst in prediction markets, and a regulatory tail that cuts in its favor regardless of the outcome. That is a compelling case today.