October 12, 2026
Bonus Content: TSMC’s 2027 Capex Is the Only Figure That Matters Thursday
Below is an important message from one of our highly valued sponsors. Please read it carefully as they have some special information to share with you.
Dear Reader,
California tried to threaten Elon’s NEXT MOVE.
For years, Newsom made California a war zone for Elon’s companies.
(This is nothing new to Elon.)
They taxed them harder than anywhere in the country.
Buried them in regulations.
State regulators even voted to cap how often SpaceX could launch, and they even went after his politics in the hearings.
Newsom boxed him in at every turn.
So Elon packed up. Took SpaceX to Texas and never looked back.
But now…
I Believe Elon’s NEW PLAN for SpaceX Has Just Surfaced…
All inside an FCC filing I just got my hands on.
And Trump is tearing down every roadblock in Washington to help him do it fast.
Want to get in on the action?
Because this could be Elon’s biggest project to date.
Bigger than Paypal…
Bigger than Tesla…
And even bigger than SpaceX itself.
And with Newsom out of the picture (and California losing out on billions)…
The profit potential could be ENORMOUS.
Which is exactly why it is crucial you watch my FREE Millionaire Maker Masterclass.
(I call it that because Elon’s plan could create 1,806,000 new millionaires.)
I’ll show you what’s inside that FCC filing.
And how to get positioned in the one company sitting at the center of all of it.
A company trading for less than $100 that I believe could help you become one of the new “Musk Millionaires” over the next decade, if you position yourself NOW.
Just click here and watch it now.
It’s 100% FREE. No credit card. No purchase. Not even an email needed to watch.
Click this link now, and I’ll see you on the inside!
Sincerely,
James Altucher
TSMC’s 2027 Capex Is the Only Figure That Matters Thursday
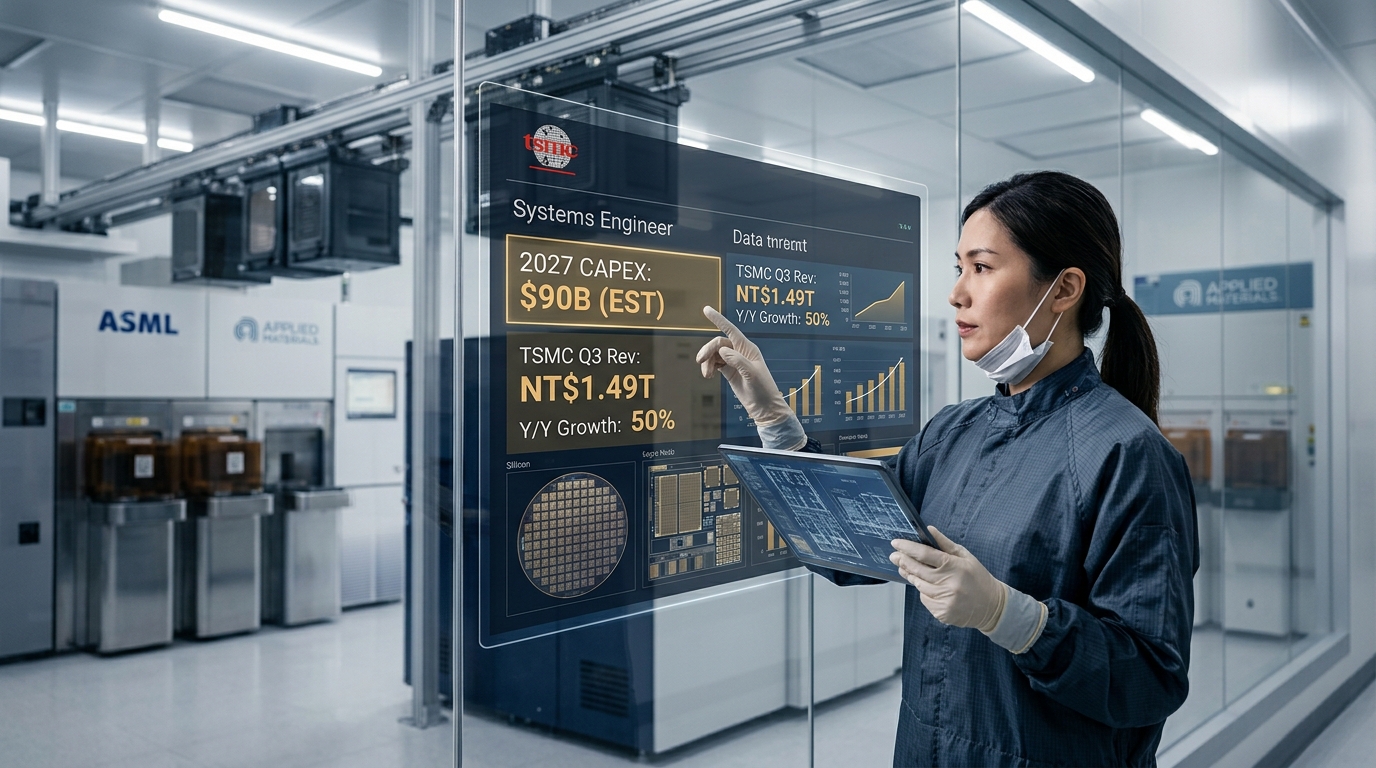
TSMC reports Thursday, October 15, at 2:00 am ET. The revenue line already cleared: third-quarter sales came in at NT$1.49 trillion ($46.71 billion), up 50% year over year and above both the company’s own guidance ceiling of $45.8 billion and the LSEG SmartEstimate. September alone rose 54.6% to NT$511.86 billion. The top line is not the debate.
What moves the AI complex Thursday is the 2027 capital spending figure. UBS raised its forecast to $90 billion for 2027 and $105 billion for 2028, up from prior estimates of $80 billion and $95 billion respectively. TSMC’s own 2026 capex has already been lifted to $60–64 billion after beginning the year at $52–56 billion, a 15% step-up at the midpoint. Thursday’s call is where management either validates the UBS math or trims around the edges. One number, two very different sector outcomes.
The Margin Overhang
Consensus has Q3 gross margin at 66.5%, inside the company’s 65–67% guidance band. That compression relative to Q2’s 67.7% is already priced. The structural question for the call is whether the 2nm ramp remains the primary drag. Management flagged explicitly that the steep ramp of 2-nanometer technology dilutes second-half gross margin by 3–4 percentage points. In Q2, 2nm contributed 3% of wafer revenue while high-performance computing reached 66% of total revenue. As 2nm output scales, the cost front-loads before the pricing power catches up. Analysts are watching the Q4 gross margin guide for any sign that the dilution is stabilizing.
Net profit is seen jumping roughly 64–65% year over year to around NT$740–746 billion. That would mark a sixth consecutive record profit and an eleventh straight quarter of earnings growth. Even so, net margin is expected to slip toward 50%, down from Q2’s 55.6%, reflecting the node-transition cost load.
What the Capex Figure Means for Equipment Names
The stakes are clear. ASML remains highly exposed to a small set of leading-edge customers, and Taiwan represented 25.5% of ASML’s 2025 net sales by geography. Bernstein has estimated that ASML’s revenue from TSMC alone could grow roughly 27% under a fully expanded capex framework, far above the 10% implied by prior consensus. Tokyo Electron has raised its wafer fab equipment market outlook to $150 billion or more in calendar 2026, with calendar 2027 projected at $190 billion or more. Applied Materials has said Semiconductor Systems is approaching 55% gross margin.
A $90 billion capex anchor from TSMC would validate those numbers. A more conservative or conditional figure, one hedged to geopolitical risk or demand visibility, pulls the rug from under all three. TSM itself closed at $453.31 on October 9, down from its October 5 record close of $485.80, partly because the Philadelphia Semiconductor Index dropped 3.39% on October 8 after the Financial Times reported OpenAI’s annualized revenue was about $50 billion, roughly $20 billion below the $70 billion figure that had been widely cited. That selloff creates the positioning context: the sector entered this earnings week already wounded by an AI demand question.
Scenario Framework
Bull Case
TSMC confirms 2027 capex at or near $90 billion, raises full-year 2026 revenue growth guidance toward the low-to-mid 40% range as Morgan Stanley expects, and signals that 2nm yields are tracking ahead of schedule. ASML, Applied Materials, and Tokyo Electron gap higher. TSM reclaims the $480–487 range. SOX recovers the October 8 loss and then some.
Base Case
Management holds the 2027 capex directionally consistent with UBS’s view but declines to quantify it formally until January. Q4 gross margin guidance lands at the high end of a 65–67% range, signaling that 2nm dilution is manageable. TSM trades in the $455–475 band. Equipment names hold recent levels without a catalyst to run.
Bear Case
TSMC hedges 2027 spending language around geopolitical risk or customer visibility, and Q4 gross margin guidance disappoints below 65%. The OpenAI revenue revision becomes the read-through: AI capex is front-running real monetization. SOX revisits the October 8 close of 12,623.7. TSM tests the $430–440 support zone.
Trading Framework
The binary risk is in the call, not the revenue figure. Traders holding long semiconductor exposure into Thursday morning are carrying an event they cannot hedge cheaply given elevated implied volatility. Key levels to watch: SOX 12,623.7 is the recent low and the line the bear case requires a breach of. TSM’s 50-day moving average sits in the $440s, providing a natural reference if the capex language disappoints. ASML and Applied Materials, which track TSMC capex guidance with higher beta, offer cleaner expression of the 2027 spending thesis than TSM itself on a day-of basis.
Position sizing matters more than directional conviction this week. Thursday’s call is the first hard datapoint on 2027 AI infrastructure capacity. Preparation, not prediction, is the edge.