October 18, 2026
Bonus Content: The Yen Is Two Figures From Japan’s Red Line. Here’s the Real Risk.
Ian Cooper here,
For the longest time…
I thought successful options trading required:
- ❌ Staring at charts all day
- ❌ Learning 100 different strategies
- ❌ Taking huge risks
- ❌ “Predicting” the market perfectly
And honestly?
That belief nearly cost me everything.
I was overwhelmed, confused, and constantly second-guessing every trade.
Then I discovered something that completely changed the game…
A surprisingly SIMPLE options setup that helped me stop overthinking and start trading with clarity.
No complicated indicators.
No endless market analysis.
No “Wall Street genius” required.
Just a straightforward approach almost anyone can learn.
That’s why I just released this FREE report:
“The 10X Options Profit Strategy;
Inside, you’ll discover:
- ✔ The #1 mistake rookie options traders make
- ✔ A simple & repeatable trade setup
- ✔ Step-by-step trade blueprints you can copy tonight
- ✔ How to ignore the noise and focus on bigger opportunities
👉 Get your free copy here now.
In your corner,
Ian Cooper
The Yen Is Two Figures From Japan’s Red Line. Here’s the Real Risk.
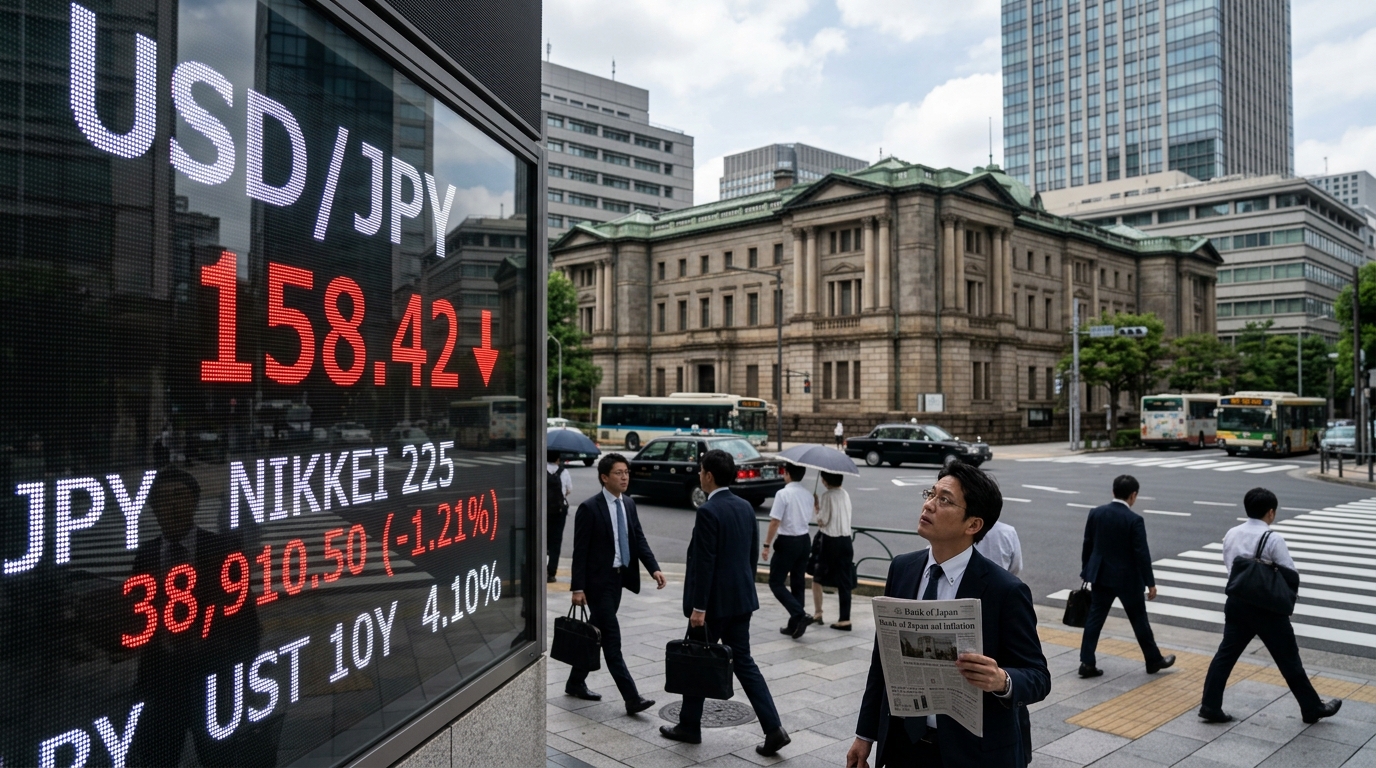
The yen is not falling apart. It is being held in a corridor by two opposing forces: a rate differential that favors the dollar and a Ministry of Finance that has already shown it will spend to enforce a ceiling. That corridor is narrowing.
- USD/JPY near 158 as of October 16.
- BoJ policy rate: 1.25% vs. Fed funds at 3.75%–4.00%, a gap of roughly 250–275 basis points.
- October hike probability: ~10%. December hike probability: ~88%. The market has already made its call.
- Japan’s Ministry of Finance spent about ¥11.73 trillion defending the yen in spring, then carried out a coordinated U.S.-Japan intervention in late July after USD/JPY moved above 160.
- Tokyo CPI for September came in at 2.7% year-on-year, well above the 2.4% forecast. Nationwide September CPI prints Friday, October 23.
- The 10-year JGB yield held at 2.93% on October 16, up 130 basis points year-on-year.
- The Nikkei 225 closed at 65,324 on October 16.
The Corridor Between 158 and 160
After the hot U.S. CPI print on Wednesday, USD/JPY climbed to 159.05. Finance Minister Satsuki Katayama warned that Japan was ready to intervene again. The yen pulled back. Between 158 and 160, verbal warnings and possible rate checks are the main tools. Actual yen purchases come later, and the record suggests they come fast.
Between April 28 and May 27, 2026, the Ministry of Finance bought about ¥11.73 trillion of yen. Then, in late July, Tokyo and Washington carried out a joint intervention after USD/JPY moved above 160. Katayama said there has been no change in the stance of Washington and Tokyo since that joint intervention. The message is consistent: 160 is the line.
Japan told G20 counterparts that authorities must closely watch exchange-rate moves. Verbal pressure is the first tool. Capital deployment is second. Traders who have tested Tokyo’s resolve since July know the cost.
The BoJ Decision and What Friday Changes
Bank of Japan officials are leaning against a rare back-to-back interest rate increase this month while still eyeing the possibility of another move as soon as December. The BoJ officials see little need for consecutive rate hikes in the absence of signs that upside inflation risks will increase abruptly. The central bank will instead carefully examine economic data to see if another hike is warranted as early as the December gathering.
Traders put the odds of an October move near 10% and see about an 88% chance by December. That pricing is the equilibrium. Disrupt it with a hotter-than-expected September CPI on Friday and the yen gap closes sharply. Miss to the downside and USD/JPY could test 159 again before Katayama’s desk picks up the phone.
Japan’s wholesale inflation rose 6.8% year-on-year in September, underscoring persistent price pressures. The internal affairs ministry will release CPI data at 8:30 a.m. on Friday, October 23. The Bank of Japan is considering declaring that the country’s underlying inflation rate has reached around 2%, as early as October 30 in its quarterly Outlook report. That declaration, even without a rate move, changes the December calculus.
The Political Backdrop
Prime Minister Sanae Takaichi continues to back away from support for reflationary economic policy to reassure markets and the Trump administration that the government is not overly cautious about interest rate hikes. Swap contracts imply that investors see around a 90% probability for another rate hike by December. Takaichi’s pivot removes one ceiling from BoJ Governor Kazuo Ueda’s flexibility. The political constraint has shifted.
Scenario Framework
Bull case for yen (USD/JPY lower): Friday’s CPI prints above 2.5% nationwide, raising the probability of a December hike sharply. JGB yields push toward 3.1%. USD/JPY breaks below 157 as carry trades unwind. Target zone: 155–156.
Base case: September CPI comes in near 2.1%–2.3%, consistent with a December hike but not enough to revive October bets. USD/JPY holds 157–159, with 160 capped by intervention threat. The BoJ holds on October 30, drops hawkish language in the Outlook report, and December becomes the dominant trade.
Bear case for yen (USD/JPY higher): CPI undershoots, December odds fade toward 70%, and the dollar resumes its bid on the 250-basis-point rate differential. USD/JPY presses 159.50–160. Katayama intervenes verbally first. If the pair holds above 159.50 for multiple sessions, physical intervention returns. The Nikkei faces further pressure from a stronger yen on any reversal.
Trader Framework
The asymmetry here is not the BoJ decision itself. It is Friday’s data feeding into market pricing for December, which in turn determines how much pressure builds on the 158–160 band before October 30. Watch the 159 handle as the first escalation level for verbal intervention. A daily close above 159.50 raises intervention risk materially.
On the JGB side, the 10-year yield held at 2.93% on October 16. A CPI surprise that lifts December hike odds could push yields back toward 3.10%, the level that rattled the Nikkei earlier this month. Exporters and rate-sensitive financials in the Nikkei respond to both variables simultaneously.
The JGB yield move is not happening in isolation. Global long-end bond yields have been resetting simultaneously, with 30-year gilt and Treasury yields both hitting multi-decade highs in the same sessions.
Position sizing should reflect the reality that the BoJ’s October 30 decision is not fully priced: the final policy decision at the Oct. 30 meeting could still change until the last minute. Friday is the last clean data point before that uncertainty resolves. Preparation, not prediction, is the edge available here.