One week on from Lula’s shock runoff win, the damage to Brazilian assets is not stabilizing. It is compounding. EWZ, the iShares MSCI Brazil ETF that U.S. traders use as their primary Brazil proxy, was down 2.05% at Friday’s close on October 30. The fund has fallen sharply over the past month, but the exact one-month market-price and NAV drawdowns vary by data vendor and measurement window. That is not a post-election exhale. It is a sustained re-rating of fiscal risk.
The reason is no longer uncertainty about who won. It is certainty about what the winner’s party will accept.
The Red Lines Inside the PT
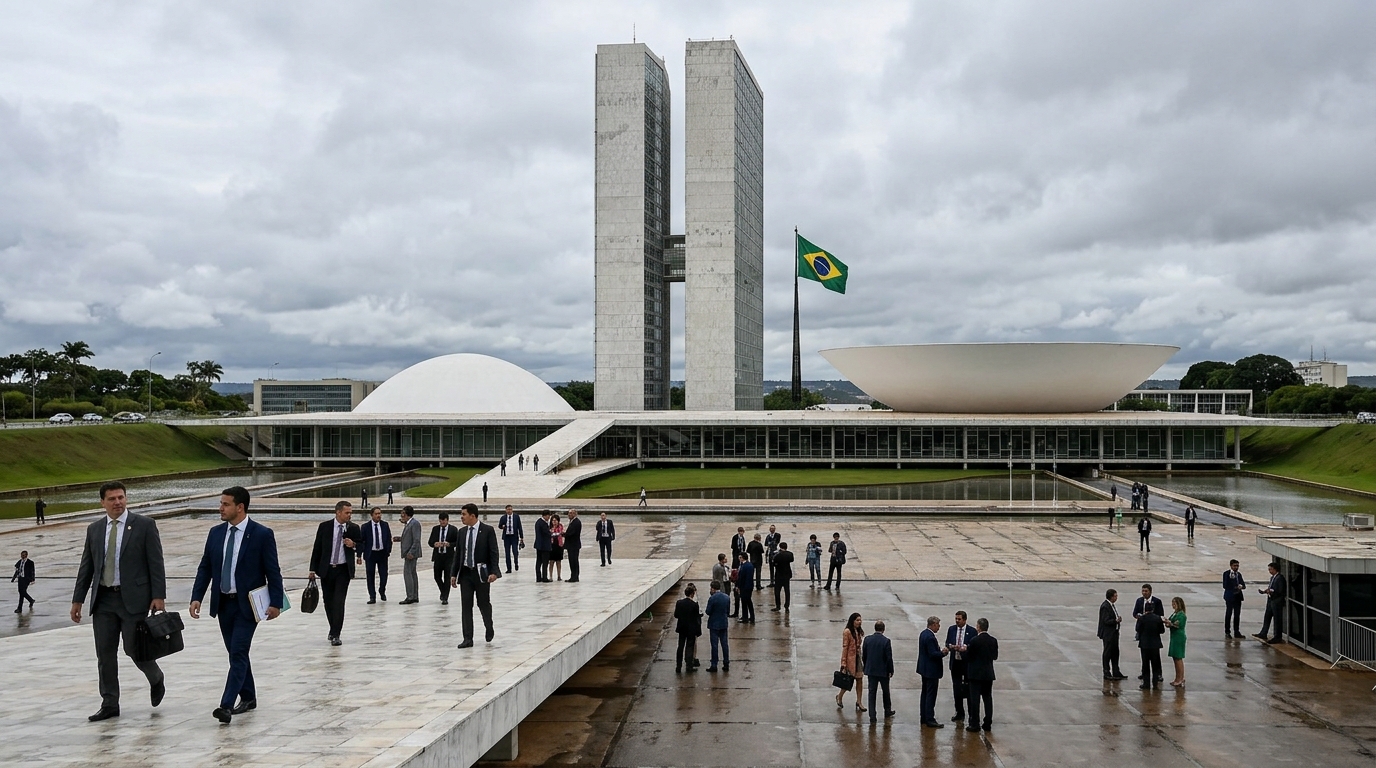
Less than a week after Lula’s re-election, members of his government and the Workers’ Party are drawing red lines around potential tougher spending measures, underscoring the challenge of slowing Brazil’s rising debt amid resistance from his own political base. Institutional Relations Minister Jose Guimaraes said it plainly: “That issue (fiscal adjustment) was not discussed, is not being discussed, and certainly is not being discussed within our caucus.” The same day, the PT’s executive committee issued a statement saying controls on spending should not come at the expense of the poor.
The comments have fueled concerns among investors hoping for signs that Lula’s next administration will tackle national debt that has climbed during his presidency to 82.9% of GDP, as fiscal uncertainty drives up government borrowing costs.
The Finance Ministry’s Signal and Its Limits
Finance Minister Dario Durigan has tried to contain the damage. Durigan said the government will pursue a higher effective primary surplus next year, and plans to send legislation to Congress this year requiring policymakers to formally target the midpoint of the primary balance goal. Brazil’s fiscal target for next year calls for a primary surplus of 0.5% of GDP, with a tolerance band of 0.25 percentage point on either side. If achieved, it would be Brazil’s first fiscal surplus since 2022.
The market’s skepticism is earned. Durigan gave no text or timetable for the bill, and the bill itself is a signal, not yet a spending cut. Most investors and economists view that pace of fiscal consolidation as too slow given the rapid growth of mandatory spending, pushing investors to demand ever-higher premiums to hold Brazilian debt.
The One Catalyst That Changes the Direction
Attention has turned to who will lead Brazil’s finance ministry and whether that person will have the political capital to overcome internal resistance to rein in spending. Two leading names frequently cited are Piauí Governor Rafael Fonteles and Vice President Geraldo Alckmin.
The next signal is the finance minister, ahead of the start of Lula’s fourth term on January 5, 2027. A market-oriented name, credibly empowered, could begin reversing the BRL move toward R$5.40. A PT loyalist, or a long delay, extends the pressure on EWZ, Petrobras ADRs, and Vale, which together make up roughly 25% of EWZ’s holdings at current weights.
What Traders Should Watch
- Finance minister announcement: The highest-impact single event. Market-friendly pick stabilizes the real; a political appointment deepens the rout.
- Fiscal bill content and timetable: The content and the date the bill goes to Congress are not yet public; any concrete schedule adds credibility the rhetoric has not.
- BRL level: Recovery toward R$5.20 requires a fiscal anchor soon; further weakness toward R$6.00 follows if no fiscal signal emerges and foreign funds continue selling.
- EWZ, PBR, VALE: All three remain exposed until either a credible finance minister or a bill with actual spending numbers lands. EWZ has traded as low as about $30.71 in the past 52 weeks.