November 1, 2026
Bonus Content: Datadog Reports Wednesday. The Real Number Is Not Revenue.
Dear Reader,
What the heck is going on at OpenAI?
The ChatGPT maker seems to make the news every day … And not for good reasons.
Their agents are attacking government websites around the world.
Leaking users’ data …
Even launching a cyberattack on a competitor.
No wonder Wall Street Veteran George Noble said …
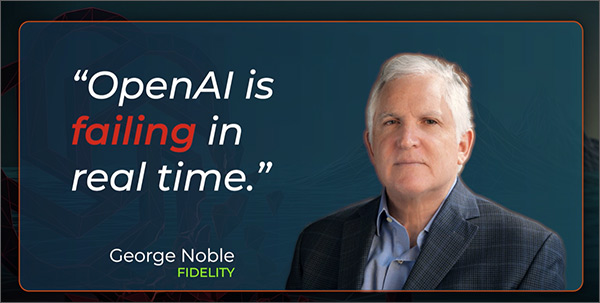
“OpenAI is failing in real time.”
Yet as terrifying as all this is …
It pales in comparison to what they are not revealing …
Medium referred to it as …
“Sam Altman’s $500 billion dollar bluff.”
So powerful that Bernstein Research, a firm with trillions under management, said …
“Sam Altman now has the power to crash the global economy … for a decade.”
This ticking time bomb could detonate as early as Dec. 18 around 4 p.m …
Don’t wait until it’s too late.
Click below to see how to protect yourself …
And potentially profit when the OpenAI truth bomb explodes.
Sincerely,
Eliza Lasky
Weiss Ratings
P.S. With the ludicrous amount of spending going into AI …
This crash has the potential to be the worst one we’ve ever seen.
Bigger than the Dot-Com bubble, the housing market collapse and the Great Depression …
It’s imperative you take the steps necessary to protect yourself.
Check out this video to learn how.
Datadog Reports Wednesday. The Real Number Is Not Revenue.
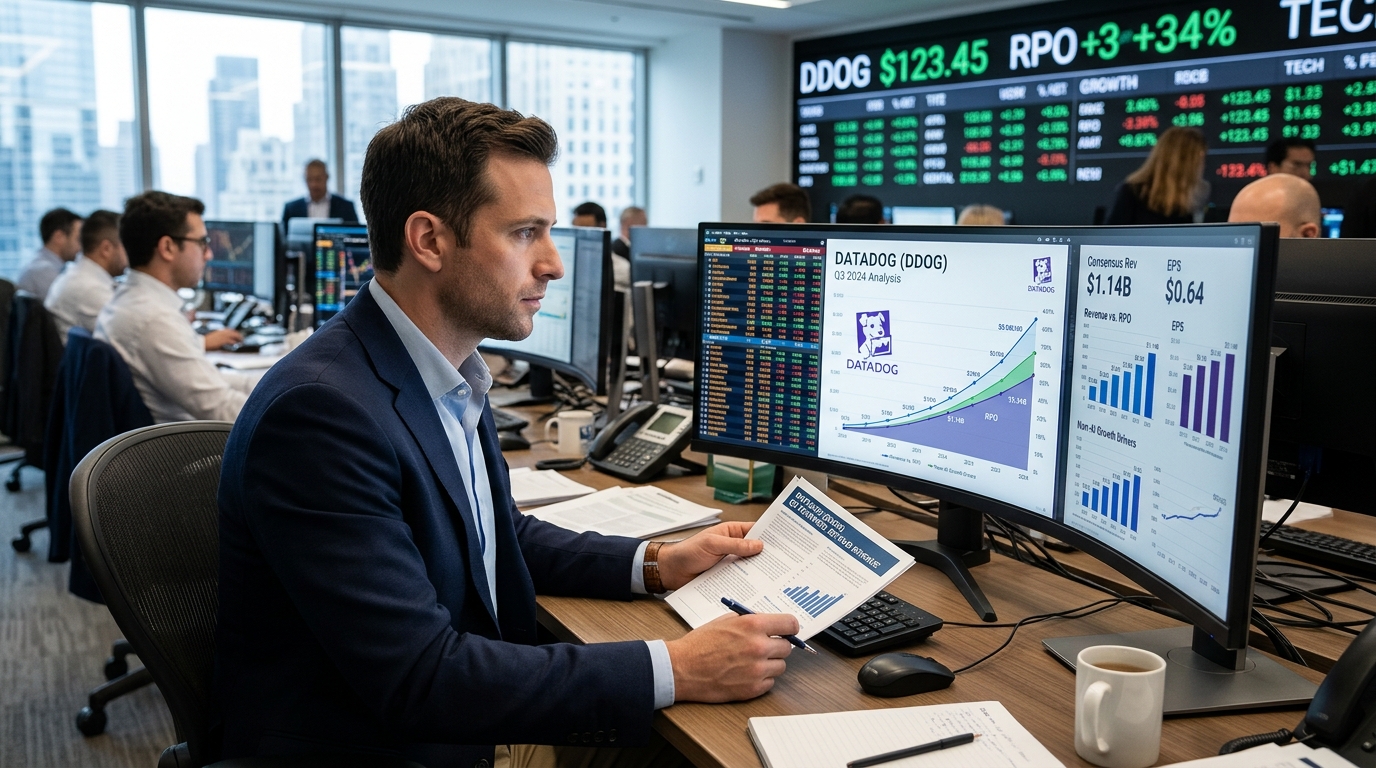
Every analyst on Wall Street already knows Datadog reports Q3 results before the open on November 4. Consensus sits at $0.64 in EPS, up 16.4% year over year, against $1.14 billion in revenue, implying 28.9% growth from the prior-year period. Those numbers are nearly certain to be met or cleared. Datadog has beaten EPS estimates in each of its last four quarters, and Oppenheimer expects revenue at the top end of management’s full-year range. The beat is priced in. The question that determines what the stock does Wednesday morning is more precise.
The Non-AI Acceleration Is the Tell
The structural trade in DDOG heading into Wednesday is not about AI-native startups. Those 750-plus customers already spend at scale, with 31 AI-native clients exceeding $1 million annually and eight exceeding $10 million. That cohort is visible, already modeled, and largely priced. What moved the stock in August was something different: revenue growth from non-AI customers accelerated to the high 20s year over year in Q2, up from the mid-20s the prior quarter and 18% in the year-ago quarter. If that line extends into the high 20s or touches 30% in Q3, the traditional enterprise cloud migration argument becomes self-funding. If it stalls, the AI-native cohort cannot cover the shortfall at current multiples.
Analysts project Remaining Performance Obligations of $3.55 billion for Q3, compared to about $2.79 billion a year ago. RPO growth that outpaces revenue growth signals forward commitment from enterprise accounts, and at 43% year-over-year growth in Q2, RPO already stood at $3.47 billion. Any deceleration there changes the contract-coverage math that underpins the bull case.
Valuation Leaves No Margin for Ambiguity
DDOG has risen 15% since August’s Q2 report, outperforming a broadly unchanged Nasdaq, while trading at 17 times forecast 2027 revenue and 57 times free cash flow. Gross margins are running near 80%, which supports the premium, but the multiple is unforgiving. UBS noted that feedback from large enterprise customers pointed to expected future spending growth of zero to 10%, with views on demand described as mixed. That gap between analyst optimism and customer-level caution is the fault line worth watching.
Scenario Framework
Bull case: Non-AI revenue growth prints at or above 30%, RPO accelerates past $3.6 billion, and management raises the full-year revenue guide above $4.50 billion. Bernstein’s $350 target comes into play, with multiple expansion possible if agent monitoring volume sustains its Q2 trajectory.
Base case: Revenue lands near $1.15 billion, non-AI growth holds in the high 20s, and guidance nudges modestly higher. The stock consolidates near current levels. The average analyst price target of $294.49 represents roughly 7% from here, consistent with a well-executed but unsurprising quarter.
Bear case: Non-AI growth decelerates to mid-20s, RPO disappoints, or management’s largest-customer headwind resurfaces in guidance language. With price-to-sales north of 26, there is no room for big disappointments. A 15% drawdown, as seen after Q2 despite the beat, remains the historical template when guidance clarity is absent.
What Traders Should Monitor
Watch the Q3 conference call for commentary on agent monitoring volume, specifically whether MCP tool calls continue the quadrupling trajectory seen quarter over quarter. That metric, not headline EPS, is the leading signal for where Datadog’s platform revenue lands in 2027. Position sizing ahead of the report warrants respect for the implied move. Disciplined execution means having your levels defined before the call begins, not after.