Lennar’s final quarterly report of fiscal 2026 is about six weeks away, and the company has already told traders most of what they need to know. The question is whether the market has done the arithmetic.
The Guidance Gap
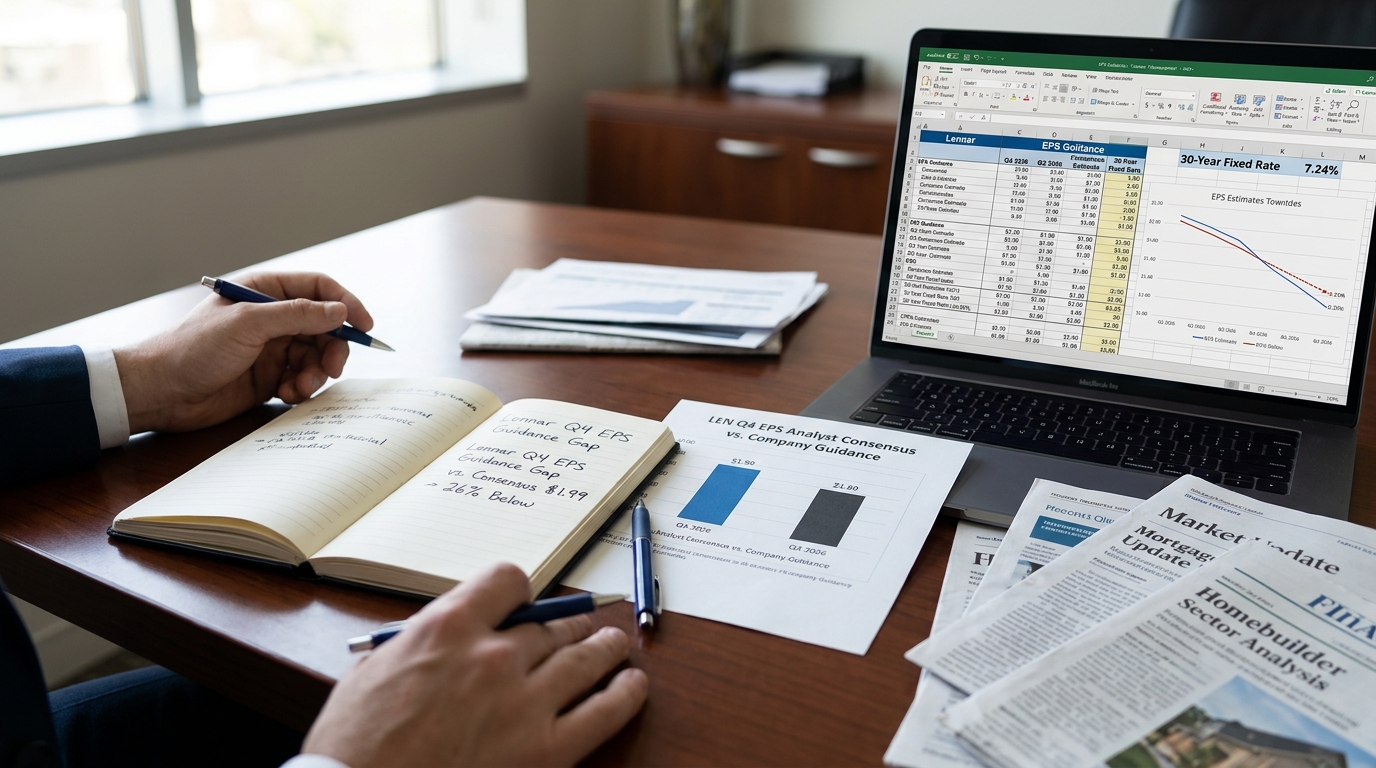
Lennar guided fourth-quarter 2026 EPS to $1.30–$1.65, well below the $1.99 analyst consensus estimate as of that guidance update. That midpoint of $1.475 sits roughly 26% beneath consensus.
The Rate Problem Is Getting Worse, Not Better
Freddie Mac’s latest weekly Primary Mortgage Market Survey has the average 30-year fixed mortgage rate at 7.24% as of October 29. That is the operating environment Lennar must close its fiscal year into. Freddie Mac also showed the 30-year fixed averaging 7.40% as of October 8, near the recent peak.
CEO Stuart Miller noted on the Q3 call that nearly 50% of visitors in many markets cannot immediately qualify for a mortgage because “the buyer at median family income is stretching well past 30% of gross income to carry a home.” That is not a cyclical soft patch. That is structural affordability failure at current rate levels.
The Buydown Burden
Homebuilding gross margin improved sequentially to 15.8%, and management said sales incentives on deliveries were about 12%. Management also highlighted a high mortgage capture rate and continued use of rate buydown programs to keep sales moving. The cost of those programs is rising. Management explicitly stated: “The cost of our buydown is becoming more expensive.” Management did not quantify the incremental cost of mortgage-rate buydowns because it varies by loan type, term, starting rate and required reduction. That unquantified liability lands squarely inside the Q4 gross margin guidance range of 15.5%–16.0%.
Scenario Modeling
Bull Case: Rates pull back toward 6.75% ahead of a November payrolls miss. Incentive costs ease, deliveries hit the top of the 22,000–23,000 range, and EPS closes at $1.65. Consensus upgrades follow into fiscal 2027.
Base Case: Rates hold near 7.1%–7.2%. Homebuilder confidence, already at a 14-year low in October, keeps buyer traffic suppressed. Lennar delivers within guidance but prints at the lower half of the EPS range. LEN remains range-bound near current levels.
Bear Case: Mortgage rates close the quarter near or above roughly 6.8%–7.0% and incentive pressure accelerates. Gross margin slips below 15.5%, EPS undershoots guidance for the fifth consecutive quarter, and Fitch’s view that EBITDA margins will step down into the mid-single digits over fiscal 2026 and fiscal 2027 becomes the dominant re-rating catalyst.
Lennar is not absorbing these pressures in isolation. The broader homebuilder sector faced a simultaneous hit from falling construction spending, rising rates, and an index ejection, a combination that reframes how traders should size exposure across the group.
Active Trader Framework
The Dec. 16 report date is the event. Traders should track the 30-year fixed weekly through November as the primary leading indicator for Lennar’s incentive cost trajectory. The unresolved question is whether builders can keep using incentives to support demand while margins fall and mortgage rates remain above 7%. That question gets its clearest answer on Dec. 16. Position sizing relative to that binary matters more than any single technical level.
Preparation is the edge here. The data is already public. The market’s pricing reflects neither the full guidance cut nor the worsening rate backdrop entering the quarter.