Wall Street loves a new story.
But sometimes the more interesting opportunity is a company that has been waiting years for the market to catch up.
One little-known Nasdaq company has spent more than 25 years developing professional drone technology that is now a priority in Washington.
This is not a company trying to invent itself around D.C.’s latest push.
It was developing these technologies long before America’s current drone demand started.
That experience matters as the Pentagon looks for scale and Washington directs more attention toward domestic manufacturers.
Yet the company is still trading under $5… for now.
If America’s drone industry is entering a much bigger chapter, investors may want to know why this pioneer remains so overlooked.
The 10-Year Treasury Hit 5.02%. Here Is What Traders Need to Know Right Now.
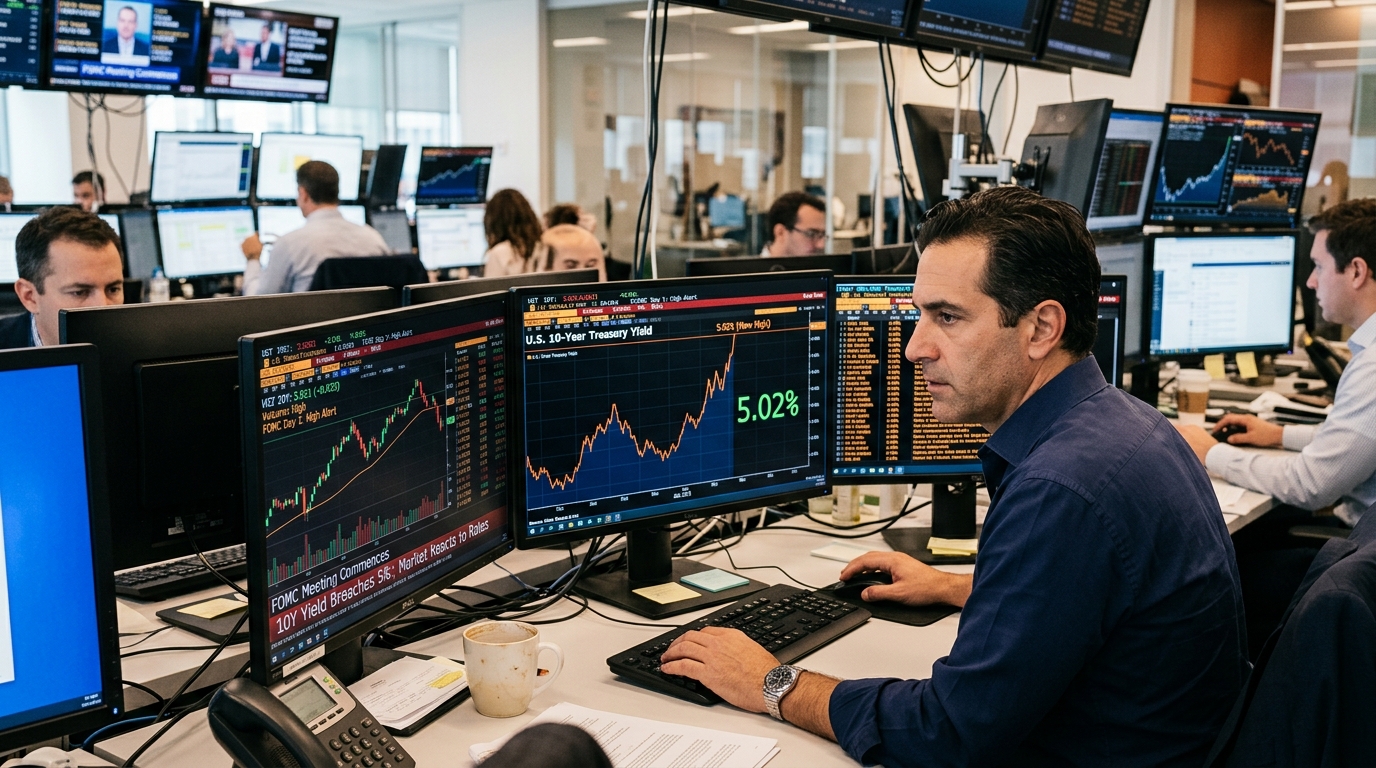
The 10-year Treasury yield closed Monday near 5% and then pushed above it. Early Tuesday, major outlets and market commentary described the 10-year trading over the 5% threshold after briefly touching 5% during Monday’s session. The 10-year moving through 5% is notable, but it is not a 19-year yield high, since the 10-year was also above 5% in 2023.
- 10-year yield: Above 5% early Tuesday after briefly touching 5% Monday (not a 19-year high)
- 30-year yield: Around the mid-5% area as rates extended their recent rise
- 2-year yield: Around the mid-4% area, sensitive to near-term Fed policy expectations
- Market-implied probability of a 25bp hike at Wednesday’s decision: High, with multiple market trackers and commentary placing odds around the mid-80s to ~90% range in recent days
- 2026 path: Yields have climbed through the year and are now testing levels that have historically tightened financial conditions quickly
- Energy: Oil’s late-summer rise has reinforced the inflation risk investors are debating into this meeting
- Mortgages: The 30-year fixed mortgage averaged 6.76% as of September 10, up from 6.71% the prior week, and some daily-rate trackers have shown readings around 7%
Why This Level Is Different
Bond investors are grappling with a mix of concerns: elevated energy prices, expectations for central banks to keep policy tight, uncertainty around geopolitics, and large fiscal financing needs. Heavy Treasury issuance is meeting a growing federal deficit, and Treasury data showed total U.S. debt crossed $40 trillion in August 2026. Term premium is the price being demanded for all of it.
The June dot plot pointed to one rate hike by year-end. After stubborn inflation prints over the summer, futures pricing has leaned toward additional tightening into year-end. At Jackson Hole in late August, Chair Kevin Warsh recommitted to the 2% PCE target and stressed that elevated prices should remain the central bank’s main focus, a hawkish signal relative to his late-July communications.
Sector Damage and Capital Rotation
A five-handle risk-free rate is not a neutral backdrop. Utilities are structurally among the most rate-sensitive equity sectors: their dividends compete directly with Treasury yields, and the sector carries meaningful balance sheet leverage, alongside REITs. Homebuilders also sit on the front line when mortgage rates move higher.
The housing market tends to slow when rates jump and volatility rises, as affordability resets and buyers step back. Mortgage rates have already drifted toward 7% in some daily indicators, and Freddie Mac’s weekly average sits at 6.76%, deepening the affordability challenge for prospective buyers.
Banks offer a partial offset. Financial companies often see improved net interest margins in a higher rate environment, but Monday’s tape tested that thesis: Goldman Sachs fell 3.96%, Morgan Stanley dropped 3.64%, and JPMorgan declined 1.71% on September 14. The market appears to be weighing credit risk over margin expansion, at least for now.
Equity weakness has remained relatively modest in 2026. The S&P 500 was still up about 11% for the year as of September 14 even as yields pushed to this new range. The question heading into Wednesday is whether 5% is the level where that tolerance breaks.
Technical and Trading Framework
On the 10-year yield itself, 5.00% is now the key psychological line. The level that mattered technically through early September was 4.95%, where the yield paused on September 10 before accelerating again. Rate-sensitive equities that were already trading below their 50-day moving averages (utilities, REITs, homebuilders) face additional compression if yields hold above 5% through Wednesday’s decision.
Oil price action remains a key real-time input for rates. If crude resumes its upswing, it can tighten inflation expectations quickly and feed into term premium. Conversely, any clear cooling in energy could take pressure off the long end even if the Fed delivers a hike.
Scenario Modeling
Bull Case
The Fed hikes 25bp Wednesday but Warsh’s press conference signals the committee is likely done for the year. Yields pull back toward 4.75% to 4.85%, relieving pressure on homebuilders and utilities. The S&P 500 recovers above pre-meeting levels. Catalyst: a dovish dot plot showing no further hikes penciled in for 2026.
Base Case
The Fed hikes 25bp and the dot plot signals one additional hike possible by December. The rate decision lands Wednesday, September 16, at 2:00 PM ET, with the Summary of Economic Projections. Yields consolidate between 5.00% and 5.10%. Rate-sensitive sectors remain under pressure. The S&P 500 churns without directional commitment through the press conference.
Bear Case
Oil prices spike further toward $100/bbl, the dot plot projects two more hikes, and Warsh reinforces that inflation data remain unacceptably high. The 10-year yield tests 5.20% to 5.30%. Long-duration equities behave mathematically like long-duration bonds: when the 10-year moves sharply higher, names with implied cash-flow duration of 15 or 20 years take a larger hit than shorter-duration positions. Growth and high-multiple technology names face the steepest re-rating.
Active Trader Strategy Framework
The FOMC statement and dot plot at 2:00 PM ET Wednesday are the primary event. Position sizing ahead of that release deserves scrutiny. Volatility compression before a Fed decision followed by a sharp move after the statement is a well-established pattern; carrying outsized rate-sensitive exposure through the announcement is a risk management question, not a directional one.
Key levels to monitor: 5.00% on the 10-year as psychological support, 5.10% as the next resistance zone. On equities, the S&P 500’s roughly 11% year-to-date gain is a cushion that can narrow quickly if financial conditions tighten further. Sector relative strength favors energy and, selectively, financials over utilities and homebuilders in a sustained high-yield regime, though bank credit concerns can override the margin benefit.
Preparation wins here. The traders with defined parameters before 2:00 PM ET Wednesday will be best positioned to respond to whatever Warsh delivers. The 5% 10-year is the context. The Fed’s next move is the catalyst.