September 21, 2026
Trump’s new “AI Force” shifts the tone in Washington and raises the stakes for Nvidia’s policy edge.
Most regulatory moats are built slowly, through years of lobbying and incremental rule-writing. Nvidia’s was built on a speakerphone call in Los Angeles on September 14, 2026.
Marc Chaikin Issues the “Strangest” Prediction of His 60-Year Career
Wall Street legend Marc Chaikin has advised billionaires like George Soros, Steve Cohen and D.E. Shaw. He predicted the 2020 Covid Crash… the 2022 bear… and the 2025 tariff sell-off, too. But he’s never made a prediction like the one he just issued.
According to Chaikin, a $248T “White Swan” event is about to overturn the AI industry… and the global order, too. It involves a strange new technology called “micro clusters.” These miniaturized data centers will render current AI tech obsolete when it comes to major breakthroughs – including models from SpaceX, Google, Anthropic and OpenAI. And they could send shares of one obscure company soaring starting Sept. 29th.
Go here for Marc’s full prediction and the name and ticker of the stock, for free.
When President Trump dialed Jensen Huang live on stage at the All-In Summit, the exchange was more than a moment of theater. The call, captured on video and widely reported, had Trump dismissing A.I. safety fears as a “hoax,” with Huang on speakerphone in front of the crowd.
The downstream consequences for NVDA’s addressable market are direct. As of September 21, 2026, Trump has said he is forming an “AI Force” modeled on the Space Force and will name an A.I. czar soon, but the administration has not released details on leadership, budget authority, or an organizational structure. But the philosophical posture is set. Trump’s September 19 announcement signals federal commitment to acceleration over restriction, and Huang’s own stated position reinforces it. He has argued publicly that A.I. risks are overblown and that safety should be approached through engineering and testing, rather than broad legislative restraint, a view now echoed in the White House’s current messaging.
Market Context: What the Regulatory Shift Unlocks
The single largest overhang on Nvidia’s revenue growth was always a Washington posture hostile to the compute buildout. That risk has been substantially reduced this week. Consider what the numbers look like with that overhang removed.
Nvidia posted full-year fiscal 2026 revenue of $215.9 billion, up 65% from a year ago, with net income of $120.067 billion. Data Center revenue for fiscal 2026 was up 68% from a year ago. Then Q1 fiscal 2027 arrived: Nvidia reported record revenue of $81.6 billion for the quarter ended April 26, 2026, up 20% sequentially and up 85% from a year ago. Data Center revenue for that quarter reached $75.2 billion, up 92% year over year, driven by the ramp of Blackwell 300 products.
Nvidia holds an estimated 80% to 92% share of the A.I. accelerator market depending on the metric used. That dominance is real. The question for active traders is how much of the regulatory moat is already priced in.
Your Entire Portfolio is Dangerously Exposed…
If you own ZERO of the Next Magnificent Seven stocks.
Original Mag Seven turned $7,000 into $1.18 million.
But these seven AI stocks could do it in 6 years (not 20).
Now, the man who called Nvidia in 2005 is revealing details on all seven for FREE.
The Friction the Bull Case Ignores
Political cover from Washington does not override a county zoning board. A New York Times and Siena University poll of 1,503 likely voters conducted Sept. 8 to 13 found 61% oppose new A.I. data center construction. Only 14% of respondents said they strongly support building these facilities. Opposition includes nearly half of Trump’s 2024 supporters. That is a durable grassroots dynamic showing up in local permitting battles and utility negotiations that no executive order resolves quickly.
Competitive pressure is also building. Amazon has said its chips business eclipsed a $25 billion annual revenue run rate by Q2 2026, growing at triple-digit percentages year over year. Google, Microsoft, and Meta are all scaling proprietary silicon. Nvidia’s grip is real; it is not structurally permanent.
Technical Framework
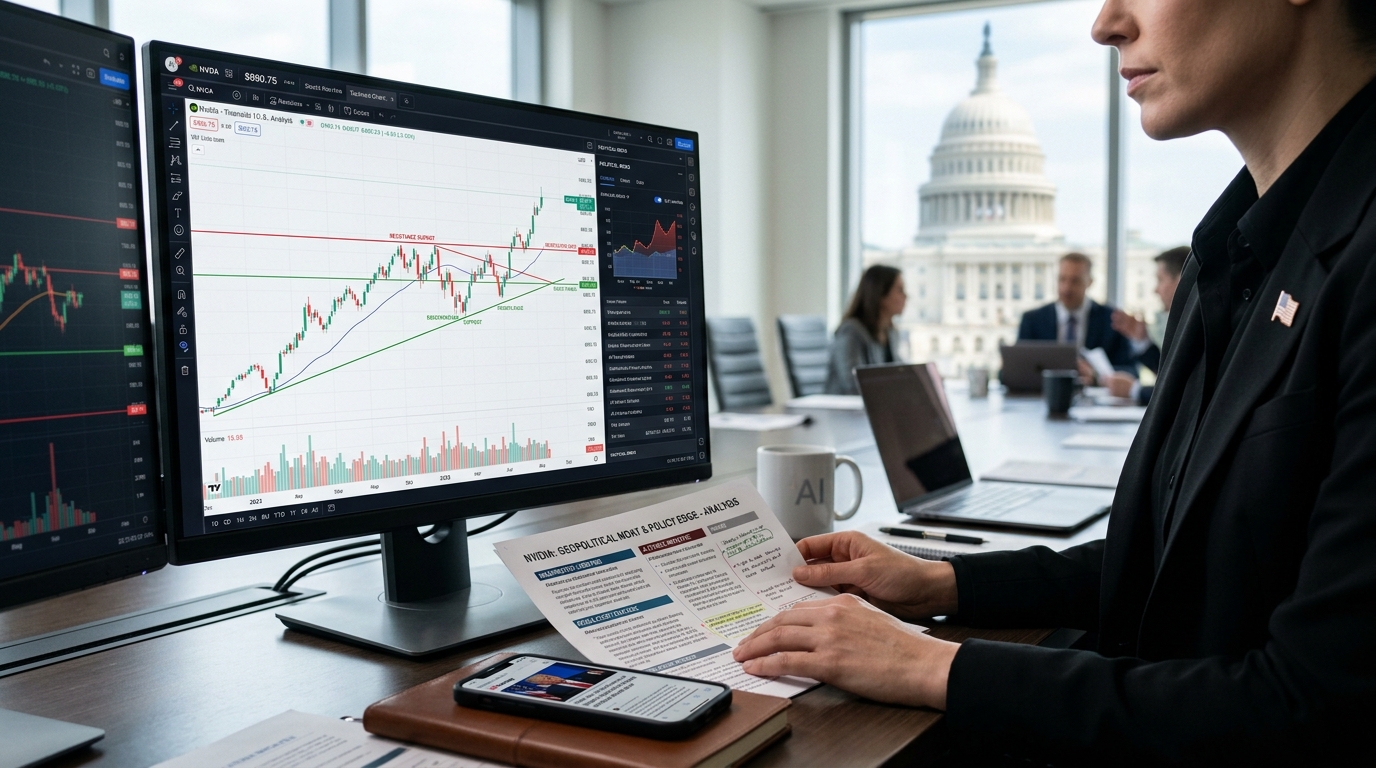
NVDA’s chart structure into this week reflects two competing forces: the political catalyst providing upside momentum, and the broader market digesting historically elevated multiples. Traders should monitor the 20-day and 50-day moving averages as dynamic support. Volume confirmation on any breakout above recent highs matters given the stock’s tendency to produce false starts on news catalysts. VWAP from the Q1 fiscal 2027 earnings session remains a meaningful reference for institutional positioning. Momentum indicators are constructive but extended on a weekly basis, suggesting pullback risk on any headline reversal.
Scenario Modeling
Bull Case: The AI Force receives a budget allocation, procurement begins resembling the Space Force ramp, and federal data center investment accelerates in fiscal 2027. Nvidia’s data center revenue sustains 60%+ year-over-year growth. Price targets in the $200 range on adjusted share count come into scope.
Base Case: The AI Force remains a directional signal without near-term procurement specifics. Nvidia sustains 40% to 50% revenue growth through calendar 2026 as hyperscaler capex holds. Stock consolidates near current levels with elevated but stable implied volatility. Management guided Q1 fiscal 2027 revenue at $78 billion, plus or minus 2%, a figure the company surpassed materially, suggesting guidance conservatism persists.
5 Nasdaq Stocks Under $5 That Aren’t What You Think
Most stocks under $5 come with a reputation. These don’t.
Each company on this list is tied to major trends like AI, cybersecurity, and next-gen infrastructure.
They may not have the spotlight yet, but they are building real businesses in real markets. That combination is not always easy to find at this price level.
Bear Case: Local permitting battles and voter opposition slow data center approvals. Custom silicon from Amazon, Google, and others takes meaningful share in inference workloads. A regulatory event in a major international market, or a Salesforce-style enterprise spending pause, compresses the multiple. Support levels near the 200-day moving average become the relevant risk parameter.
Active Trader Strategy Framework
The political alignment Huang has built with the administration is a secondary advantage. The primary case for NVDA ownership has to rest on the technology lead: Blackwell architecture, the CUDA software moat with over four million registered developers, and the compounding infrastructure cycle. When political access rather than engineering output drives conviction, position sizing discipline should increase proportionally.
Huang is slated to attend Trump’s state dinner for Chinese President Xi Jinping on September 24, 2026, a room few other semiconductor CEOs are expected to occupy. That access has direct implications for export policy on H200 and successor chips, which remains a live variable for revenue models.
Volatility into and around that diplomatic event warrants attention. Position sizing should reflect the binary nature of export policy outcomes. Defined-risk structures through options are worth considering for traders who want exposure without absorbing a gap risk in either direction.
Conclusion
Preparation, not prediction, is the framework here. Nvidia holds a historically rare combination: technology leadership, market share above 80%, and a CEO whose worldview is now informally echoed in executive branch policy. Both vectors currently point in the same direction. The discipline required is ensuring the political vector remains a supplement to the fundamental one, not the reason to own the stock. Monitor Washington, track data center permitting trends, watch competitor silicon adoption curves, and respect the levels.