Dear Reader,
I had to share this with you today.
It’s probably the greatest stock story I’ve ever heard.
It involves a strange new wonder material that just set two world records.
As a result, the company behind it is suddenly partnering with major tech companies.
It includes Samsung, LG, Lenovo, Dell, Xiamo… and the big one Nvidia.
Nvidia is working at lightning speed to get this new tech in its brand new AI super-factories.
Why?
Well, that’s the most interesting part of the story.
If there’s one stock that could repeat Nvidia’s 35,600% climb over the past 10 years, this new tiny stock might just be it.
Click Here to See The Greatest Stock Story Ever Told
Yours in smart speculation,
Stephen Prior, Publisher
Monument Traders Alliance
P.S. The Center for Strategic & International Studies reports this new tech “has emerged as a frontrunner in the quest to push the boundaries of electronics, ushering in a new era of energy-efficient and high-performance devices.”
See how it was used to set two new world records right here.
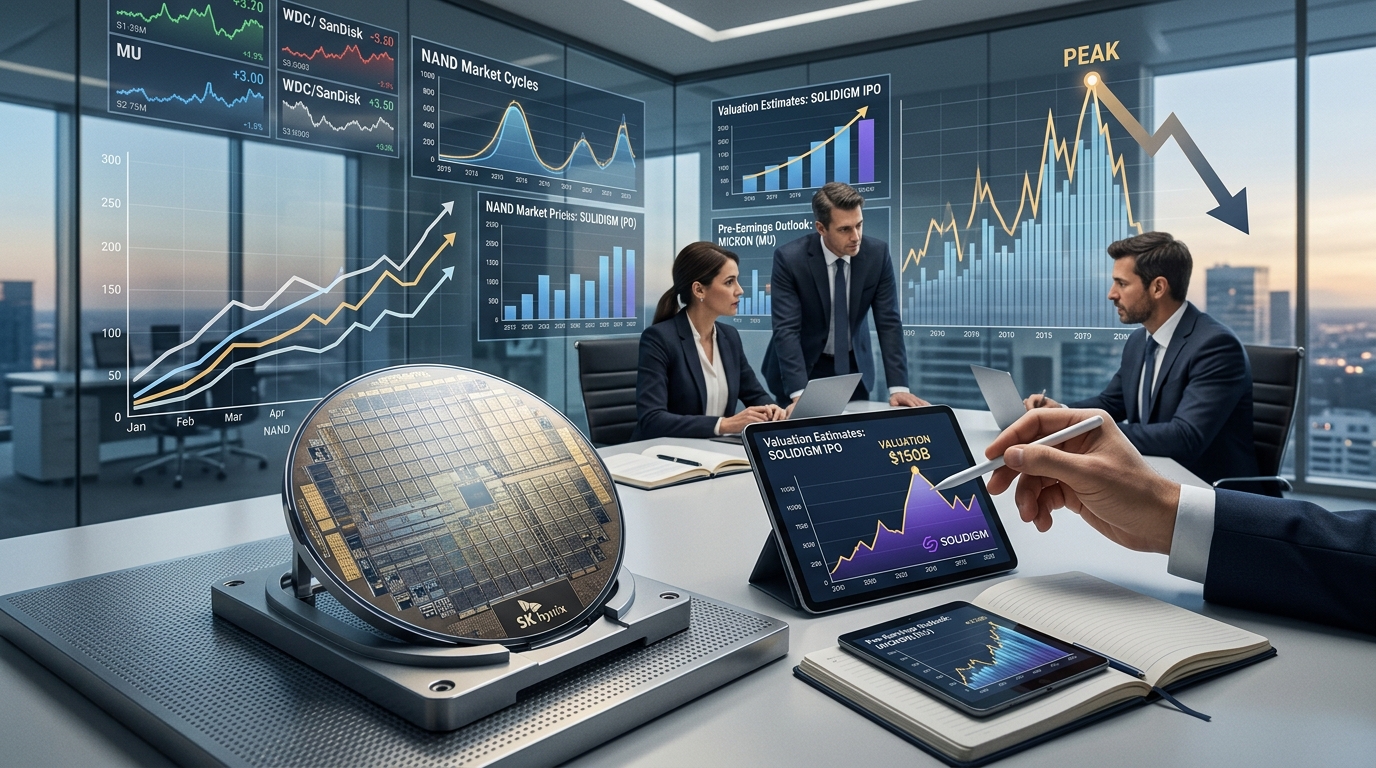
SK Hynix Is Trying to Sell NAND at the Peak. Watch MU and SanDisk.
When the company that built the cycle starts pitching bankers on how to exit it, traders should pay attention. Reuters reported Friday that Solidigm, SK Hynix’s U.S. NAND unit, met with investment banks this week in a competitive bake-off for IPO roles, targeting a valuation of up to $150 billion with a potential raise of as much as $15 billion. The timing: three business days before Micron reports fiscal Q4 2026 earnings.
That sequencing is not coincidental. It is a decision about when peak valuations are available.
Market Context
Memory equities have been one of the defining trades of the AI infrastructure cycle. SanDisk stock has rallied roughly 675% to 700% year-to-date, driven by AI-driven NAND demand and pricing power. Micron is scheduled to report next week, and the broader setup remains the same: tight supply, accelerating end-demand in AI-linked memory, and equity prices that have already discounted a lot of good news.
The fundamental driver is real. Micron has said demand for high-bandwidth memory remains tight, and industry commentary has consistently framed HBM availability as constrained. Micron’s fiscal Q3 2026 results showed NAND revenue increased 99% sequentially, primarily due to a mid-80% range increase in average selling prices, with bit shipments up in the mid-single-digit percentage range. Separately, Micron’s reported business unit results show the Cloud Memory Business Unit generated $13.769 billion in revenue in fiscal Q3 2026, up from $7.749 billion the prior quarter, with an 83% gross margin.
The Solidigm Signal
SK Hynix acquired Intel’s NAND business for about $9 billion, with the final phase closing on March 27, 2025, according to Intel’s filings. A $150 billion IPO valuation would represent roughly a 16-fold return on that cost basis in about five years. Cycle tops tend to be when 16-fold returns get monetized, not when they get held.
A valuation of up to $150 billion would far exceed recent semiconductor IPOs, including Arm Holdings’ roughly $54 billion valuation at its 2023 debut and Cerebras Systems’ roughly $56 billion fully diluted valuation in its 2026 IPO. Separately attributed commentary on memory pricing has emphasized that tight markets can normalize quickly once supply responses arrive. SK Hynix is asking banks to price that risk into someone else’s capital.
Read-Through to MU, SNDK, WDC, INTC
MU’s next earnings date is confirmed for Wednesday, September 30, 2026, after market close. Wall Street expects adjusted earnings of about $31.5 per share, up sharply from $3.03 in the year-ago period. That is the bar, and it is elevated. The market has been conditioned to expect strong results, which is precisely what makes the lead-up complex.
A $2,400 Buy initiation from Rosenblatt sent SanDisk up about 6% to 7% earlier this week, a stock already up roughly 675% to 700% year-to-date on AI-driven NAND pricing power. That sympathy move compresses the margin for error ahead of Tuesday’s report.
While new fabrication capacity typically takes years to come online, a faster-than-expected ramp could eventually ease the current supply shortage. SK Hynix’s recent Nasdaq ADR listing could also divert capital from domestic chipmakers like SanDisk and Micron. A Solidigm IPO in 2027 adds a direct NAND-pure competitor to the public market at a moment when supply discipline is the only thing holding pricing.
Scenario Framework
Bull Case: Micron delivers a beat-and-raise on September 30, guiding Q4 free cash flow above the $30 billion already flagged. MU holds above $1,100, SNDK reclaims $1,900, and the Solidigm IPO announcement is absorbed as cycle validation rather than a top signal. Key level: MU above $1,150 post-earnings.
Base Case: Micron meets the roughly $31.5 consensus but guides conservatively on NAND pricing durability into 2027. The stock fades 8-12% from current levels as the Solidigm headline shifts the framing from supply shortage to supply monetization. SNDK and WDC underperform on sympathy. MU range: $950-$1,050 by mid-October.
Bear Case: Micron misses or signals NAND ASP deceleration in fiscal 2027. The Solidigm bake-off retroactively reads as informed selling at a cycle high. MU tests the $740-$800 band seen in late July. SNDK, already up roughly 675% to 700% year-to-date, faces institutional distribution that has no historical precedent for this valuation level.
Trading Framework
The pre-earnings drift in MU is already constructive, but the Solidigm news introduces an asymmetric risk overlay. Traders holding long memory exposure into Tuesday’s close should size positions against the $950 level as a defined risk boundary. Implied volatility on MU options will expand into the report; premium sellers face adverse skew if the results disappoint. SNDK’s roughly 675% to 700% YTD run leaves no cushion for a guidance miss in the group.
Watch INTC separately. SK Hynix created Solidigm after acquiring Intel’s NAND business for about $9 billion, with the transaction’s final phase closing on March 27, 2025, per Intel’s filings. A successful Solidigm IPO at $150 billion would be a permanent reminder of what Intel sold at the bottom of the cycle. That context matters for how the market revalues INTC’s capital allocation credibility.
Preparation over prediction. The Solidigm bake-off does not guarantee a top. It does guarantee that the seller has done the work to identify one.