Corporate IT budgets get squeezed every cycle. Zero trust does not. The distinction matters for traders sizing positions in cybersecurity names right now, because the spending forcing enterprises into zero-trust architecture is not driven by discretion, it is driven by regulatory mandate, breach liability, and the structural reality that multi-cloud expansion has permanently dissolved the perimeter that traditional firewall vendors once guarded.
The Macro Picture
Global cybersecurity spending is projected to reach about $240 billion in 2026, up 12.5% from roughly $213 billion in 2025, according to Gartner. Within that total, the zero trust security market is commonly estimated in the tens of billions of dollars in 2026, with forecasts that extend well above $100 billion in the early 2030s. The multi-cloud security segment is also widely forecast to grow at a low-20% annual rate in the mid-2020s. These are not venture-stage projections. They are the contracted-revenue shadows of three publicly traded vendors that already show up in quarterly filings.
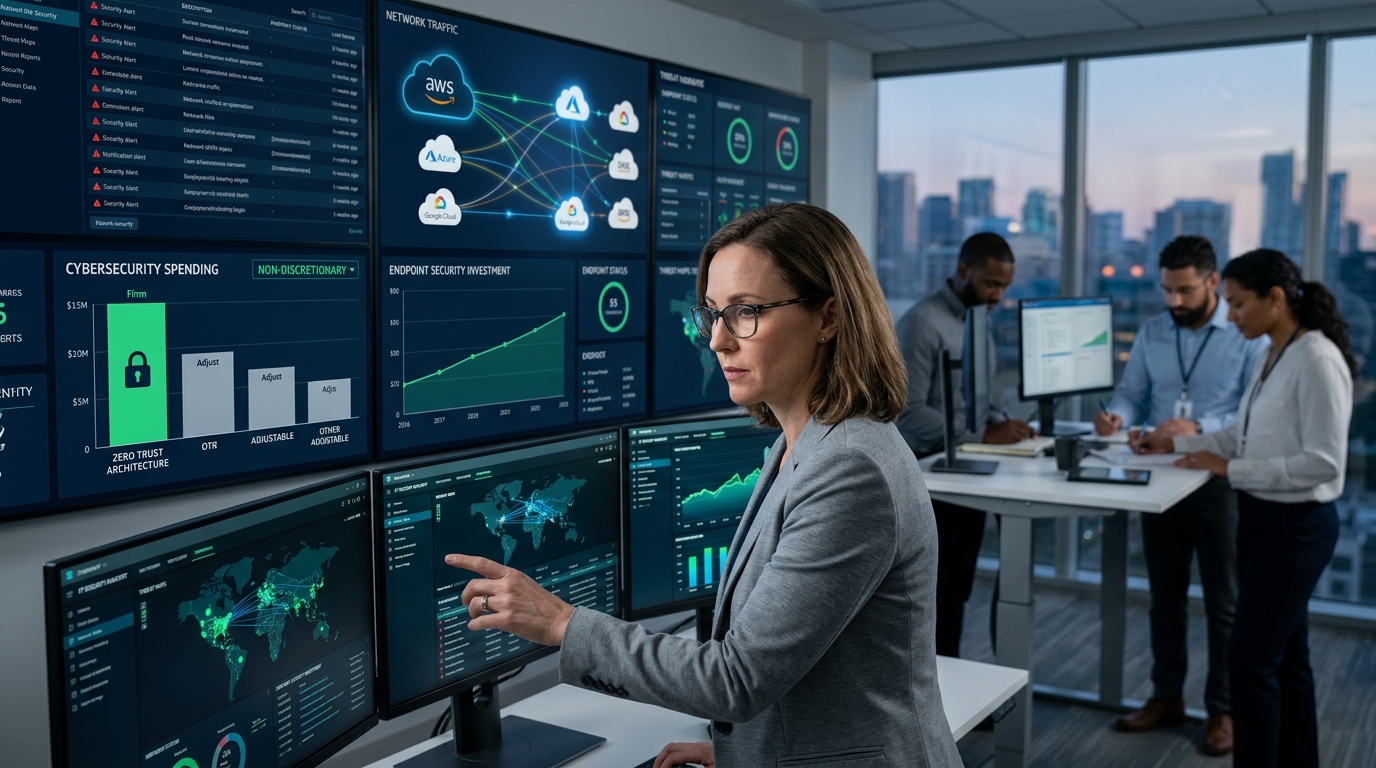
The structural driver is simple: endpoint security is a large share of the multi-cloud security spend because laptops, mobile devices, and IoT endpoints are primary entry points for attackers targeting distributed cloud workloads. As enterprises span AWS, Azure, and Google Cloud simultaneously, every unmanaged device becomes a liability that compliance frameworks now require them to address explicitly. CISA’s Binding Operational Directive BOD 25-01 already requires federal civilian agencies to implement secure cloud practices and establish ongoing assessment and monitoring for in-scope cloud tenants, and private-sector regulators are following.
Sector Breakdown: Three Names Absorbing the Spend
Palo Alto Networks posted Q4 fiscal 2026 revenue of $3.41 billion, up 34% year over year, closing full-year revenue at $11.5 billion. Its next-generation security ARR jumped 63% to $9.1 billion in that quarter, with nearly $1 billion in net new NGS ARR added in a single period. Remaining performance obligation crossed $20 billion for the first time, closing at $21.2 billion. Management is targeting $20 billion NGS ARR by FY2030.
CrowdStrike closed fiscal year 2026 with $4.81 billion in revenue, up 22% year over year, and ended the year with ARR of $5.25 billion. In its fiscal 2027 first quarter (ended April 30, 2026), CrowdStrike reported ARR of $5.51 billion, up 24% year over year, and record net new ARR of about $256 million, up 32% annually. The stock trades around the mid-$200s, and Bank of America raised its price target to $260 in September 2026 while Morgan Stanley lifted its target to $254.
Zscaler reported fiscal Q4 2026 revenue of $898.2 million, up 25% year over year, with annual recurring revenue reaching $3.77 billion and deferred revenue growing 19% to $2.926 billion as of July 31, 2026. The company guided FY2027 for continued growth in the mid-20% range for ARR.
Technical Framework
CRWD is trading near the top of its 52-week range, above both its 50-hour and 200-hour moving averages. RSI sat at approximately 64 in mid-September, below the 70 threshold traders use to flag an overbought condition. Price reclaimed $200 in early September and has held. The risk zone is a mean-reversion to the 200-day moving average on a broader tech selloff. PANW closed around $331 following its September 1 earnings report; sector tone from that report directly influenced CrowdStrike and Zscaler intraday moves given how tightly correlated platformization commentary now travels through the group.
Scenario Modeling
Bull case: AI-driven breach volumes accelerate into Q4, CIO survey data confirms zero-trust budget ring-fencing for 2027, and PANW’s $14.1 to $14.2 billion FY2027 revenue guide stays intact. CRWD pushes through $270, PANW through $360.
Base case: Multi-cloud endpoint security demand grows steadily, platformization wins continue at Palo Alto, and CrowdStrike ARR sustains mid-20s growth. Valuation compression in the broader software sector keeps multiple expansion limited, capping index-level upside for the group near current levels while earnings close the gap.
Bear case: Enterprise budget freezes in response to a macro slowdown shift zero trust from non-discretionary to deferred spend. CRWD’s elevated EV/revenue multiple remains a compression target. A retest of the $200 level on CRWD and $280 on PANW would define the technical floor to monitor.
Active Trader Strategy Framework
The valuation divergence across the group is the clearest positioning input. PANW trades at a significant discount to CRWD on a forward multiple basis despite larger absolute revenue and about $3.47 billion in free cash flow in fiscal 2025, which management described as roughly a 38% adjusted free cash flow margin that year. Traders watching for relative-value rotation within the sector should track net new ARR prints and platformization traction as the leading signal, not trailing revenue. Volatility in individual names remains elevated on earnings, with PANW falling about 5% after its fiscal Q2 report despite beating consensus, a pattern that rewards patient entry rather than reactive positioning. Keep sector ETF flows in view: CrowdStrike’s weight in CIBR tends to sit near the top of the ETF’s holdings, so ETF flows can amplify individual moves.
Conclusion
Zero trust has moved from security philosophy to contractual obligation. Multi-cloud expansion does not pause, and neither does the regulatory calendar enforcing it. Preparation means tracking ARR growth rates, platformization traction, and remaining performance obligations as the real economic signal, while maintaining discipline around entry levels in a group that regularly punishes investors who chase after earnings beats.