Dear Reader,
In the days leading up to June 12, one trader on Wall Street stood almost completely alone.
While nearly every media outlet in America was selling readers on the biggest IPO in stock market history…
Hall of Fame Trader Jon Najarian was saying the opposite.
He was right.
The math he laid out before the IPO was simple. SpaceX went public at a valuation as high as $2 trillion. Early investors who got in years ago at a fraction of that valuation already made their fortunes.
The IPO day buyers were paying a massive premium.
But Jon’s full analysis was never just a warning.
It was a recommendation – a publicly traded company building exactly what Elon needs for his next venture. A venture Morgan Stanley estimates at $40 trillion.
A company that’s 42 times smaller than SpaceX. The recommendation is still open.
Microsoft’s Copilot Overhaul Lifted the Dow. Now Azure Must Deliver.
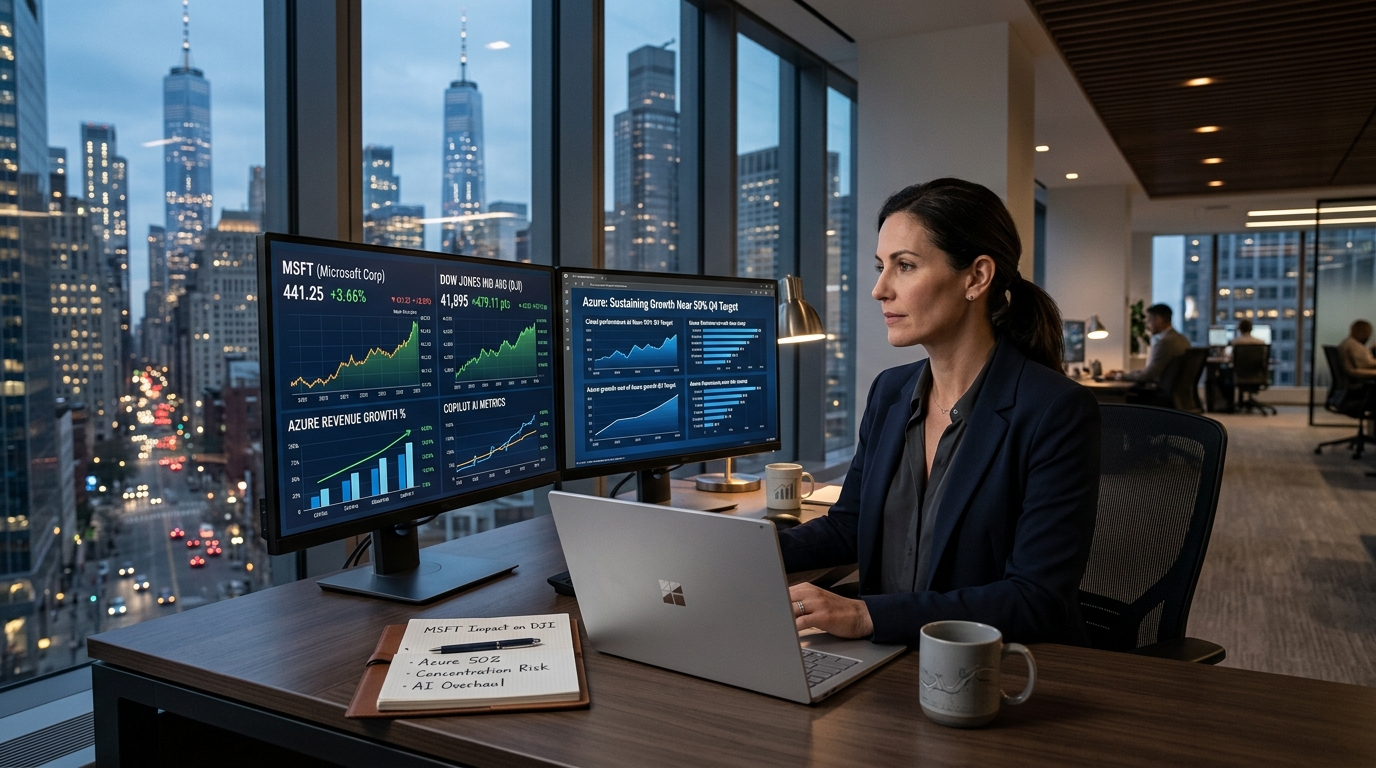
One stock did most of the Dow’s work on Friday. Microsoft (MSFT) gained 3.66% after unveiling a sweeping Copilot overhaul on September 25, contributing roughly 120 points to the Dow’s roughly 479-point advance. The S&P 500 added 0.5% and the Nasdaq 0.48%. That dispersion matters: a price-weighted index moving on a single name is not a broad rally. It is a concentration trade. Traders entering the new week need to decide whether the product announcement justifies the price, or whether Friday was a sentiment event that Azure earnings must now defend in late October.
What Microsoft Actually Shipped
The Copilot revamp consolidated consumer and enterprise products into one application built around three capabilities. Home provides a unified chat interface. Code lets users build apps and dashboards from plain-language prompts, powered by the same underlying technology as GitHub Copilot, with early access rolling to customers by month-end. Autopilot, the agentic feature, builds on the Scout agent Microsoft introduced on June 2 and can execute multi-step tasks without step-by-step user direction. Word, Excel, and PowerPoint are now embedded directly in the app. Microsoft also introduced consumption-based billing for advanced features, moving beyond flat per-seat subscriptions.
The product architecture matters because it closes the gap between developer tools and executive-layer workflow. Oppenheimer analyst Brian Schwartz described the shift as transforming Copilot from a standalone chatbot into an “AI operating system,” arguing that platform positioning drives higher engagement, more monetization vectors, and stronger customer stickiness than a point solution ever could. Reuters reported September 22 that Oppenheimer raised its price target to $570 from $515, keeping an Outperform rating.
The Azure Threshold That Drives Rerating
Schwartz was precise about the condition for a valuation rerating: Azure growth approaching 50% while operating at a scale exceeding $100 billion annually. That bar is not hypothetical. Microsoft said Azure surpassed $100 billion in annual revenue in fiscal 2026, the first time it has done so. Growth last quarter came in at 43%. Microsoft has guided to Azure constant-currency growth of about 45% for the September quarter. Microsoft reports fiscal Q1 results in late October, with some earnings calendars currently pointing to October 28.
For context, Microsoft’s most recent full-year revenue was $331.8 billion, up 18%. The Intelligent Cloud segment, which houses Azure, generated $137.8 billion for the fiscal year. Microsoft’s AI business surpassed a $37 billion annual revenue run rate as of the March quarter, up 123% year-over-year. Capex for fiscal 2026 exceeded $115 billion, almost entirely in data centers and AI infrastructure. The market’s patience with that spending depends directly on Azure acceleration sustaining.
Sector Positioning: Who Benefits, Who Competes
Friday’s session exposed a clean divergence. Alphabet (GOOGL) gained a modest 0.46% and closed at $343.92 as investors stayed focused on Microsoft’s spending plans rather than Google’s own AI cloud products. Meta (META) fell 3.33%, a pointed contrast: META is doubling down on personal AI assistant products at the exact moment Microsoft is pivoting Copilot toward enterprise workflow and away from that consumer layer. Enterprise software rivals felt the pressure. Salesforce (CRM) closed down 1.76% on the day, despite its own Agentforce platform crossing $1 billion in annual recurring revenue earlier this month. Salesforce guides FY27 revenue to $46.1-$46.4 billion with 11-12% growth, a trajectory the market continues to discount given competitive pressure from Microsoft’s bundled distribution. ServiceNow (NOW) carries a steeper valuation than CRM, with 2026 subscription revenue guidance near $15.76-$15.78 billion growing about 21% in constant currency, but its AI annual contract value also crossed $1 billion and agentic deployments grew ninefold in nine months. Neither can match Microsoft’s distribution reach or Azure’s infrastructure leverage.
Technical Framework
MSFT closed Friday at $516.17, having traded as high as $519.40 on the session before settling. Volume reached 38.19 million shares against an average of 23.89 million, confirming institutional participation in the move. The stock’s 52-week range runs from $349.20 to $553.72; Friday’s close places it roughly 7% below the prior high. The $516 area that acted as resistance in early September analysis is now the immediate test zone: holding above it as a support level opens a measured-move objective toward $525-$530. A failure to hold brings $495-$500 back as the next reference. The RSI reading is elevated following this week’s move, suggesting momentum is extended short-term. The 50-day SMA sat near $459 as of early September; the stock is trading well above that level, which remains the structural floor for any deeper pullback.
Scenario Modeling
Bull Case
Azure September-quarter growth prints at or above 46% when Microsoft reports in late October. Copilot paid subscriptions, which surpassed 30 million as of fiscal Q4, accelerate through consumption-based billing. MSFT holds above $516 and tests the $540-$553 range into earnings, approaching the consensus target of $570-$572.
Base Case
Azure delivers in the 44-46% range, in line with guidance. The Copilot revamp generates positive enterprise commentary on the earnings call but material revenue contribution remains a 2027 story. MSFT trades in a $495-$530 range, consolidating the Friday gap, with the Dow index concentration risk limiting further single-session contributions from the stock.
Bear Case
Azure growth disappoints at or below 43%, erasing the rerating thesis Schwartz outlined. Treasury yields, already at multi-decade highs during this past week’s trading, resume their rise and compress multiples across high-capex technology. MSFT gives back the gap and tests $480-$490. The Dow’s dependence on one constituent becomes a structural liability, as 19 of 30 components were already trailing on Friday.
Active Trader Framework
The asymmetry heading into late-October earnings is clear. Traders long MSFT above Friday’s close should treat $495 as the first meaningful stop zone and $516 as the tactical line to defend on a closing basis. Position sizing should account for the October earnings binary: Azure either validates the rerating or forces a re-test of pre-announcement levels near $497-$500. Volatility expectations should be elevated given the capex scrutiny and the size of Friday’s move on above-average volume. On the sector level, a continuation of Microsoft’s enterprise AI momentum argues for relative strength in MSFT over CRM and GOOGL into the report, though that trade reverses sharply if Azure disappoints. Risk management, not conviction, is the framework here.
The product announcement was real. The revenue test is still ahead. Friday’s Dow gain was not confirmation of a broad AI rally; it was a single stock responding to a product catalyst. What matters now is whether Azure’s growth trajectory, not Copilot’s feature list, earns the multiple that Friday’s close implies.