October 9, 2026
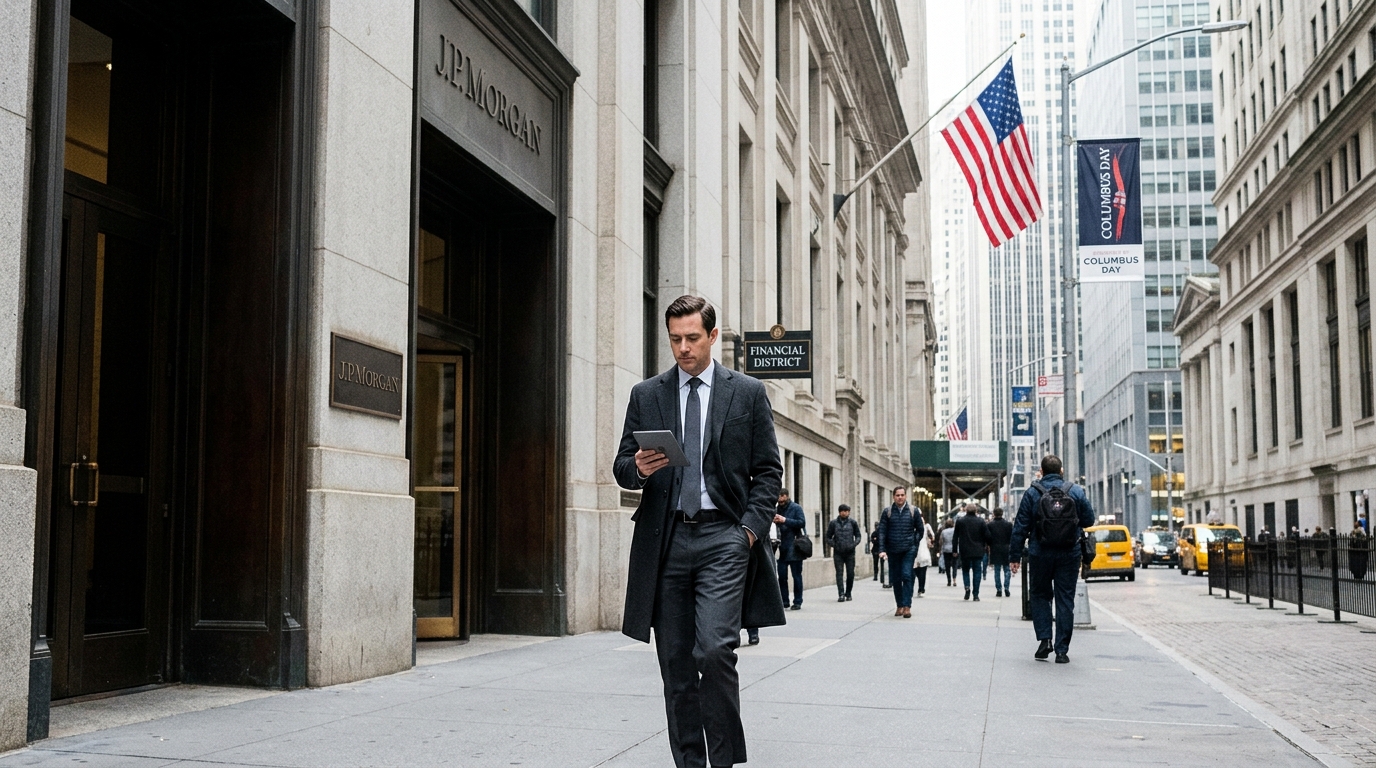
Columbus Day thins Monday trade. JPMorgan reports Tuesday at 7 a.m. ET.
The S&P 500 closed Friday at 7,811.54, up about 0.6% on the session. The Nasdaq added about 0.6%. On the surface, the week ended well. Under the surface, the conditions that rattled Thursday have not changed.
AI CEO Issues Code Red: Prepare for Meltdown
The CEO of this AI company (click here to get the name, 100% free) just issued a CODE RED in an internal memo…
Warning his employees that they’re dealing with a critical situation.
Another company executive even implied they might need a government bailout.
And now Jim Rickards is predicting this company is about to go bust, in a full-blown AI meltdown that could be 10 times bigger than Lehman Brothers.
What Friday’s rally did not fix. The 10-year Treasury yield touched about 5.36% this week, its highest reading since 2002, before pulling back modestly. The MOVE Index, which measures Treasury volatility, stood at 100.70 at Friday’s close, down from a weekly peak above 113 but still well above mid-July levels. Semiconductors, represented by SMH, fell Friday even as software (IGV) gained. The divergence matters: one widely followed participation measure had about 36% of S&P 500 members trading above their 50-day moving averages. This is a narrow rally carrying record-level index prices.
The Three-Day Runway
Monday is Columbus Day. Bond markets close. Equity markets stay open, but volume will be thin. The Fed’s communication blackout ahead of the October 27 to 28 FOMC meeting begins Saturday, October 17, not yet. That still compresses the window. Traders have roughly one full trading session before a wall of event risk lands Tuesday morning.
Tuesday, October 13, before the open: JPMorgan Chase, Goldman Sachs, Wells Fargo, and Citigroup all report Q3 results. JPMorgan’s release is due at approximately 7:00 a.m. ET, with an 8:30 a.m. ET conference call. Street consensus sits near $5.93 EPS on roughly $51.2 billion in revenue. Options markets are pricing a roughly 4.4% earnings-day move for JPM. The bar is high and the implied move is wide.
Goldman Sachs consensus sits near $16.00 to $16.40 EPS. Bank of America follows Wednesday, October 14, alongside the September CPI print at 8:30 a.m. ET.
World’s Largest Investors Are Moving Their Money (Not Into AI)
While the media distracts you with stories about the next big AI IPO… The world’s largest investors are moving their money into one asset – at the fastest pace in a generation. This asset has crushed the S&P 500’s return over the past 12 months… More than TRIPLED the S&P 500’s return in 2025… and has outperformed the S&P 500 over the past 25 years by more than 1,100 percentage points. According to one Wall Street veteran, with over 40 years of professional investing experience… the biggest gains could be still ahead. That’s why he’s urging you to make one money move now.
CPI Is the Rate Fulcrum
Street consensus for September CPI is around 3.7% year over year, up from August’s 3.4% reading. The Cleveland Fed nowcast has recently put the headline closer to 3.60%. Core CPI consensus is around 2.5% year over year. The FOMC meets October 27 to 28. A hot headline number, particularly if driven by energy rather than core services, could reignite the debate over whether the Fed’s next move is a hold or another hike. A core print below 2.4% would likely relieve yield pressure and give risk assets room to extend.
Thursday, October 15 brings PPI, with consensus expecting 0.5% month over month after August’s 0.4% reading, and retail sales. Full-year S&P 500 earnings growth is now tracking near 30% by some estimates, but that multiple sits against a forward P/E of roughly 21x and a risk-free rate above 5%. The arithmetic on valuation is unforgiving if inflation does not cooperate.
Scenarios for the Week Ahead
Bull case: JPMorgan delivers at or above $6.00 EPS, investment banking commentary is constructive, and Wednesday’s CPI comes in at or below 3.6% year over year with core near 2.3%. The 10-year yield retreats toward 5.1%, and the S&P 500 retests the 7,844 level.
Base case: Banks report in line, CPI lands near 3.7%, and the market interprets the data as consistent with a Fed hold at the October 27 to 28 meeting. Yields stay rangebound between 5.1% and 5.4%, and the S&P 500 consolidates between 7,750 and 7,844.
This Loan Shouldn’t Be Possible
A federal board just voted unanimously to lend roughly $3 billion to one American mining company.
One of those two valuations is wrong, and the papers get signed in the second half of this year.
Bear case: CPI surprises above 3.9% on energy passthrough, or JPMorgan issues cautious guidance on credit costs and net interest income trajectory into 2027. The 10-year yield spikes toward 5.5%, and SPY loses the 775 level on volume, reopening the path toward 760.
The Level That Matters Monday
With the bond market closed and banks prepositioned into earnings, Monday’s equity session is most useful as a positioning check. Watch whether SPY holds above 778 on any intraday softness. A clean hold confirms institutions are willing to carry risk into Tuesday’s reports. A breakdown below 774, particularly on thin volume, would signal that the smart money is hedging before the data, not after.
Preparation, not anticipation, is the edge this week. The catalysts are known. The levels are visible. The only question is whether the numbers confirm what prices are already pricing.