October 9, 2026
Bonus Content: The Fed Just Signaled More Rate Hikes. Here Is What Traders Need to Know.
Dear Reader,
Elon Musk has spent years quietly developing a new machine.
It’s not a rocket… robot… or car…
Most investors have never heard of it.
But the United States Patent Office has already revealed how it works.
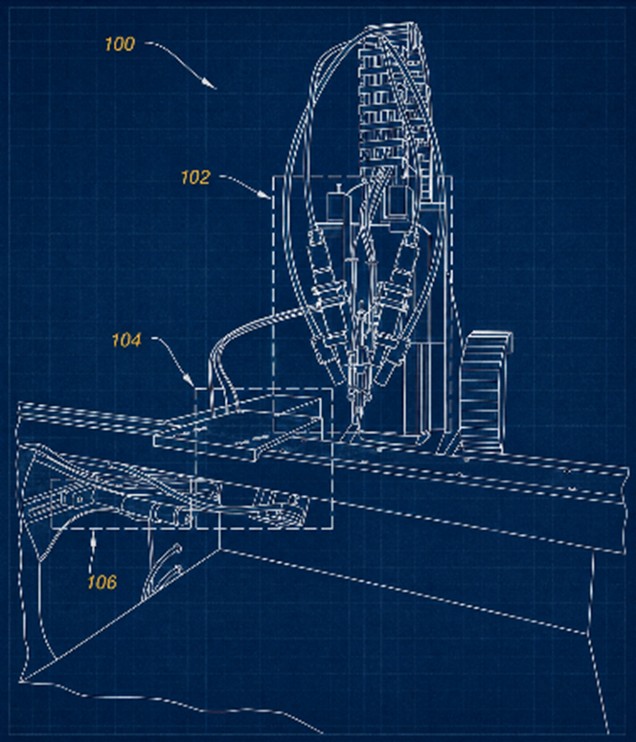
The evidence is buried inside Patent No. US 11,291,508 B2.
Click here to examine the discovery and the stocks connected to it.
Let me be clear…
This is something completely new.
If it works, it could open an enormous new market for artificial intelligence and launch what Wall Street veteran Matt McCall calls the sixth “Musk Stampede.”
Click here to see what Elon’s patented machine could make possible
Matt has spent more than 25 years identifying major technology trends before they became obvious.
Over that time, he has uncovered more than 50 stocks that later climbed 1,000% or more at their peak.
Now he believes one small public company could benefit as Elon brings this patented technology into the mainstream.
It’s already attracted an eight-figure investment from Nvidia.
And a major gathering beginning November 14th could bring fresh attention to the entire field.
Click here to learn how to get the name and ticker symbol before November 14th.
Good investing,
Matt McCall
Former Fox Business analyst, Editor of McCall Innovations Report
P.S. The patent is already public. The companies surrounding it are still almost entirely unwatched.
The Fed Just Signaled More Rate Hikes. Here Is What Traders Need to Know.
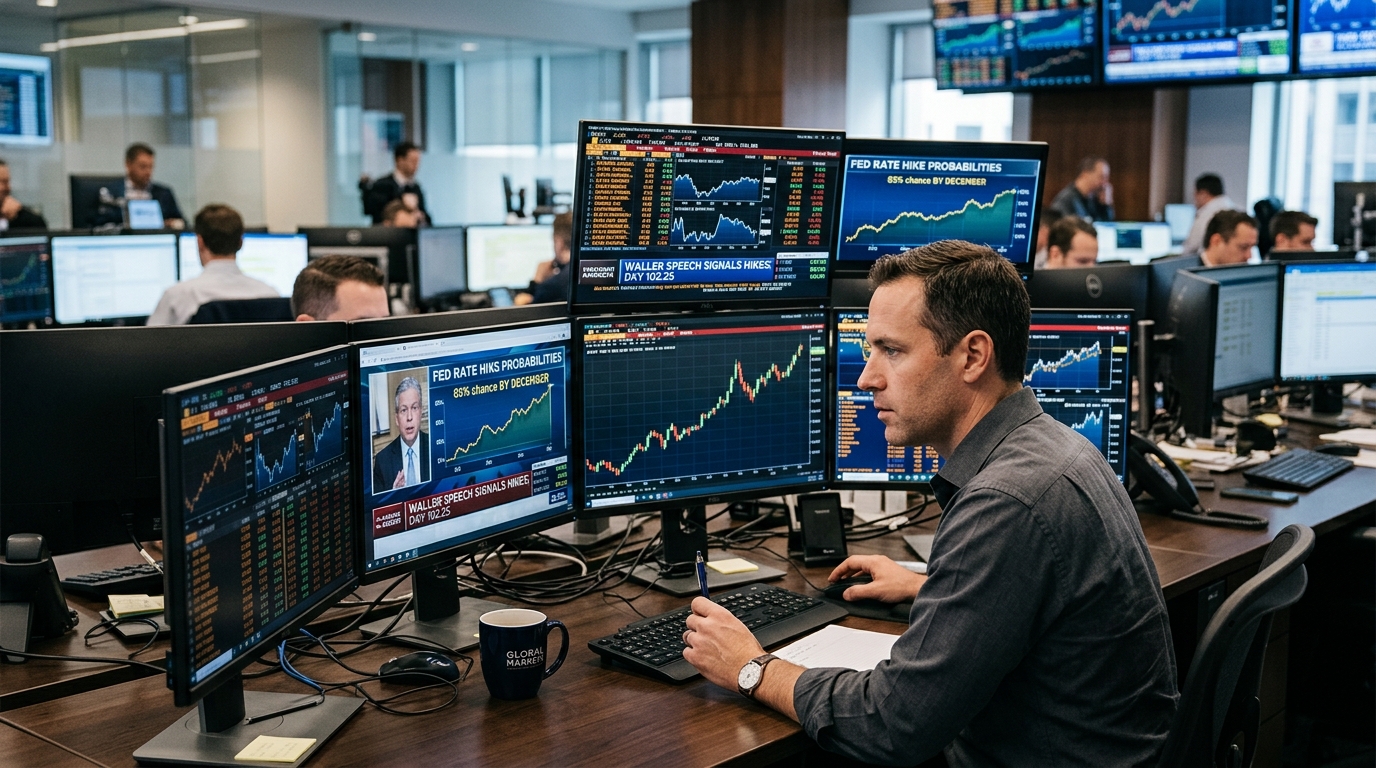
Governor Christopher Waller stepped to the podium in Istanbul Thursday morning and handed markets a clear policy signal: more rate hikes are coming, the only open question is when. The rates complex has been moving for weeks, but Waller’s remarks crystallized the direction. Traders who have not yet updated their positioning frameworks for a genuine second tightening leg need to do so now.
Market Context
The 10-year Treasury yield sits at 5.23% this morning, pulling back from a 52-week high of 5.365% printed earlier this week, its highest level since early 2002. The two-year is at 4.75%, and the 30-year has climbed to 5.60%, according to U.S. Treasury par yield data as of October 8. The yield curve has bear-steepened meaningfully over the past month, with the 10-year up roughly 12 basis points since early September and about 109 basis points higher than one year ago.
The dollar index (DXY) trades near 102.25, its highest level since March 2025. EUR/USD sits around 1.12. USD/JPY is at approximately 158.1, with the yen having weakened over the past month as elevated US yields continue to widen the rate differential.
What Waller Actually Said
Speaking at the Central Bank of the Republic of Türkiye’s Istanbul Economic Forum, Waller was explicit: “If the economic data continue to come in as expected, I anticipate additional hikes to support a timelier return of inflation to our 2 percent goal.” He also acknowledged that 16 of 18 FOMC participants project at least one additional hike this year, with four projecting two. Critically, he noted that markets have read the Committee as likely to raise the policy rate 50 basis points in the coming months, and futures as of October 7 showed an 85% probability of at least one hike by the end of the December meeting. He added flexibility language, saying hikes need not come at consecutive meetings, which is why October is now largely priced out.
Waller identified three persistent inflation risks: elevated oil prices that could last through 2027, AI infrastructure spending pushing technology prices higher, and the threat of new tariffs reigniting goods inflation.
Hike Odds and Where They Stand
The October meeting is now effectively a hold. CME FedWatch has the probability of a quarter-point hike at roughly 18%, with an 82% hold probability. December is the live meeting. Waller cited futures pricing that implied an 85% probability of at least one hike by the end of the December meeting and close to an 80% chance of at least two hikes by March 2027.
Sector and Credit Implications
High yields this steep carry real weight across asset classes. The ICE BofA US High Yield Index option-adjusted spread was about 3.12% as of October 7. For investment-grade credit, effective yields on BBB-rated debt are running near 6.19%. The stress is more acute in lower-quality high yield, where spreads remain materially wider than BB and single-B.
Rate-sensitive equity sectors, utilities, REITs, and long-duration growth names, face the most direct valuation headwind. The dollar’s strength at 102.25 pressures US multinationals with large overseas revenue streams, while financials with floating-rate books stand to benefit from the tightening cycle.
Technical Framework
The 10-year yield broke its multi-year range ceiling decisively in September and has spent the last two weeks consolidating near 5.23–5.28%. The prior breakout area near 5.00% now acts as a long-term reference level for the yield complex. DXY held above 101.80 on every daily close this week, keeping the trend intact. EUR/USD has a sequence of lower highs and lower lows on the daily chart, with technical targets toward 1.1065 on a continued decline. USD/JPY has been probing the 158 area, with the next resistance zone at 158.85–160.00 and intervention risk returning if yen weakness accelerates.
Scenario Modeling
Bull Case for Risk Assets
October 14 CPI prints at or below 3.0% year-over-year, giving the Fed cover to skip October and signal a patient December. The 10-year retraces toward 5.00%, the dollar softens below 101.00, and credit spreads tighten. Equities stabilize with the S&P finding footing above key technical support.
Base Case
Data comes in roughly as Waller expects. The Fed holds in October, hikes 25 basis points in December, and the 10-year oscillates in a 5.10–5.40% range through year-end. DXY holds 101–103. High-yield spreads drift modestly wider. Equity volatility remains elevated into the December 8–9 meeting date.
Bear Case
A hot CPI on October 14 reactivates October hike odds above 50%, the 10-year tests its 52-week high of 5.365%, DXY breaks above 103, and EUR/USD tests 1.10. Lower-quality high-yield spreads widen further, and rate-sensitive equities reprice sharply lower. BoJ intervention risk also spikes if USD/JPY moves through 160.
Active Trader Strategy Framework
The October 14 CPI release is the most actionable near-term catalyst. Traders should monitor whether the 10-year can hold below 5.30% or retest 5.365% as a directional guide. In FX, EUR/USD below 1.1150 opens the path toward 1.0870; USD/JPY above 158.85 on a sustained basis raises intervention risk and demands disciplined stop management. In credit, the divergence between investment-grade spreads (still relatively contained) and lower-quality high-yield stress is a positioning signal worth tracking. Sizing and hedging into binary data events remains the discipline that separates prepared traders from reactive ones.
Waller’s speech did not predict a specific meeting outcome. It defined a direction. The market’s job now is to price the path, and that path runs squarely through December.