October 13, 2026
China’s graphite export-control suspension ends Nov. 10, 2026. Amprius just raised 2026 guidance to at least $140 million. The two events land five days apart.
Silicon anodes are no longer a laboratory promise. They are a live supply chain event, and the clock is ticking.
The Supreme Court Protected Your Location. What About Your Financial Data?
In June, the Supreme Court ruled that acquiring an individual’s cell-phone location data constitutes a Fourth Amendment search. But your financial activity on most public blockchains can still be visible. One overlooked altcoin was designed around financial privacy – and our team believes it deserves attention as crypto momentum builds.
Discover our next “Freedom Coin” and get the complete $3 research report today.
China suspended its expanded export licensing requirements covering certain lithium-battery and artificial-graphite anode-material items, plus related manufacturing technologies and equipment, for one year. That suspension is set to expire on November 10, 2026, less than a month from today. That single deadline is concentrating capital into materials companies already replacing graphite with silicon at commercial scale. The trade is not about which EV charges fastest. It is about who owns the anode supply chain when Beijing’s temporary reprieve runs out.
The backdrop is stark. Beijing sits at the center of the graphite supply chain, including the bulk of global graphite processing. Battery manufacturers must evaluate whether to treat the suspension as a temporary reprieve or a signal of sustained trade normalization. Historical precedent suggests China is unlikely to permanently relinquish export control authority over strategically important materials.
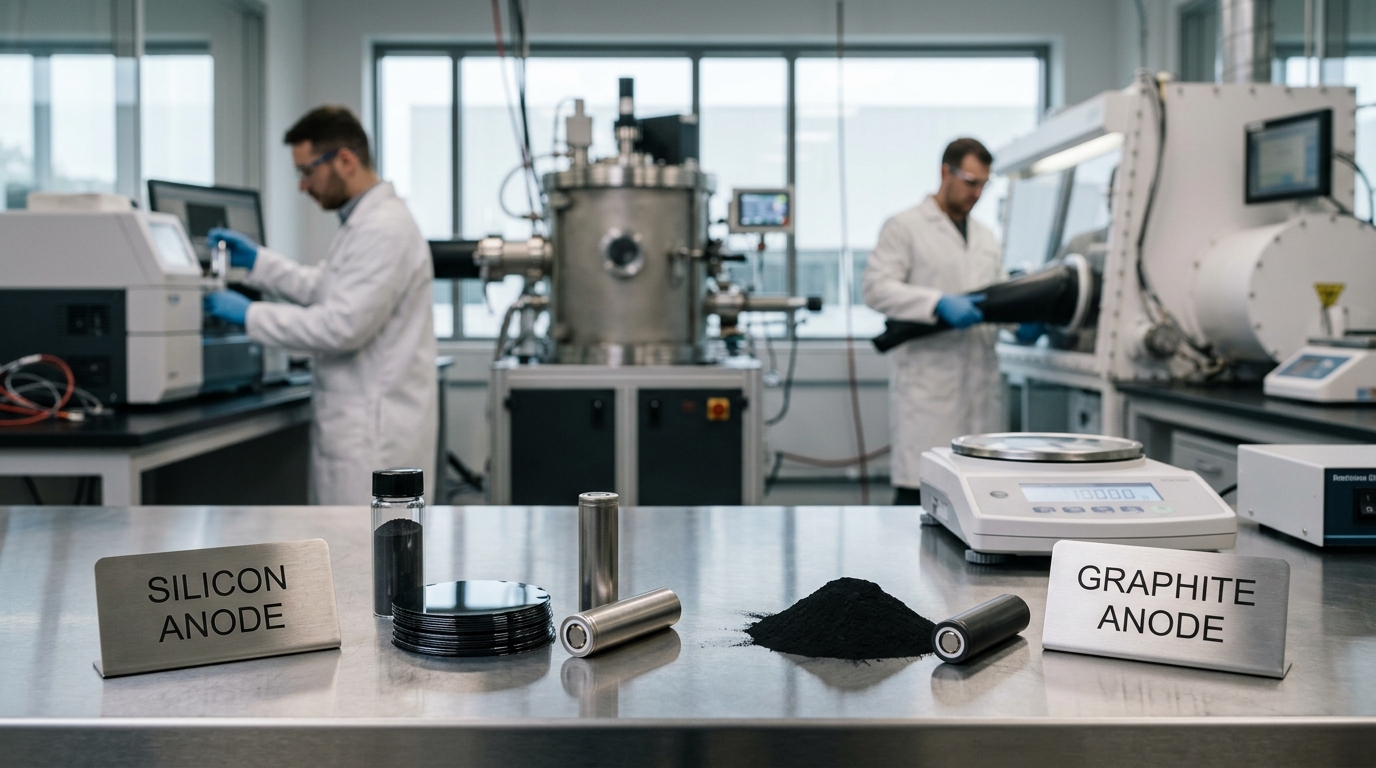
Silicon-carbon anode technology has crossed its first genuine commercial threshold in 2026. Group14 Technologies announced in March 2026 that its South Korea battery-material plant has begun EV-scale production of its SCC55 material. The plant is designed for up to 2,000 metric tons of silicon battery material per year, enabling approximately 10 GWh of energy-storage capacity annually as production ramps. Claims of sub-two-minute full recharges vary widely by cell design and test conditions, so treat the most aggressive charge-time anecdotes as marketing until they show up in third-party cell-level data. On cycle life, silicon-carbon platforms such as SCC55 are generally positioned as improving durability versus earlier silicon-heavy designs, but performance ranges depend on chemistry and use case. On the passenger vehicle side, Sila Nanotechnologies says its silicon anode can help enable a 10-to-80% charge in about 20 minutes today, with a path to below 10 minutes.
The only publicly traded pure-play with real revenue is Amprius Technologies (NYSE: AMPX). Q2 2026 revenue more than doubled year-over-year to $34.0 million, up 126% from $15.1 million in Q2 2025. Amprius raised its full-year 2026 revenue forecast to at least $140 million, up from at least $130 million previously. Gross margin expanded to 27% in Q2 2026, improving from 20% in Q1 2026. The company also disclosed a $24 million order from a new European drone manufacturer and a multi-year supply agreement starting in 2027 with Stark Future that it said represents a total revenue opportunity exceeding $100 million. Longer term, Amprius has discussed targets including more than $600 million of contracted capacity by 2030, gross margins above 30%, and adjusted EBITDA margins of at least 20%.
Louis Navellier: Don’t buy OR sell another AI stock…
Until you’ve heard this urgent AI warning from the man who called Nvidia before its 44,000% rise…
According to Louis, a massive reset is coming in an obscure corner of the AI market.
This $100 trillion disruption could send some of the world’s biggest AI stocks to zero… and one off-the-radar stock soaring… starting now.
Silicon is not the only battery-material story attracting capital as supply chains restructure. Lithium extraction technology has drawn its own wave of strategic investment, with one company reaching a $1B valuation on GM and POSCO partnerships.
The stock has not followed the numbers. AMPX has recently traded in the high-single-digits, well below its prior 52-week high, but those levels move and should be treated as time-sensitive. Wall Street price targets also move with coverage changes and revisions, so treat any single median target as a snapshot, not a constant. But Amprius Technologies’ Q3 2026 earnings are expected around November 5, 2026, five days before the graphite deadline closes.
Scenario Modeling
Bull Case: The November 10 deadline triggers immediate supply chain re-contracting toward silicon alternatives. Q3 revenue exceeds $34 million, guidance rises for a third consecutive quarter, and margin expansion toward 30% pulls analyst targets higher. AMPX retraces toward the $15 to $18 range within 30 to 60 days.
Base Case: Q3 lands between $29 and $32 million, consistent with prior guidance. Full-year guidance holds at $140 million. Stock consolidates between $8 and $12, awaiting a November 10 policy headline that either confirms controls returning or grants another suspension.
Why Nov. 12 Could Matter for Your Money
If you own stocks, bonds, or have retirement savings, Nov. 12 deserves your attention. Jeff Opdyke warns China’s next financial move could hit the U.S. dollar – and your wealth. See why.
Bear Case: China grants another suspension, removing urgency. Q3 gross margin disappoints relative to the at-least-28% full-year gross margin guidance the company reiterated in its Q2 2026 update. AMPX retests the prior 52-week low area, with risk toward $6.50 on valuation compression.
Policy deadlines reshaping one critical-material supply chain rarely travel alone. Copper has already moved through its own Section 232 tariff escalation, showing how fast procurement decisions shift when a government deadline closes.
Active Trader Framework
The November earnings report and the November 10 graphite deadline create a two-event window most traders are treating as unrelated. They are not. With suspension deadlines expiring in November 2026, the race to build alternative supply chains has become a live capital allocation decision, not a strategic planning exercise. Risk sizing must account for both catalysts. Use recent 52-week extremes as context rather than anchors, and treat $12 as a practical reference point for overhead supply if it has repeatedly capped rallies in recent months. Positioning into earnings should assume elevated implied volatility, with an added policy headline risk the week after.