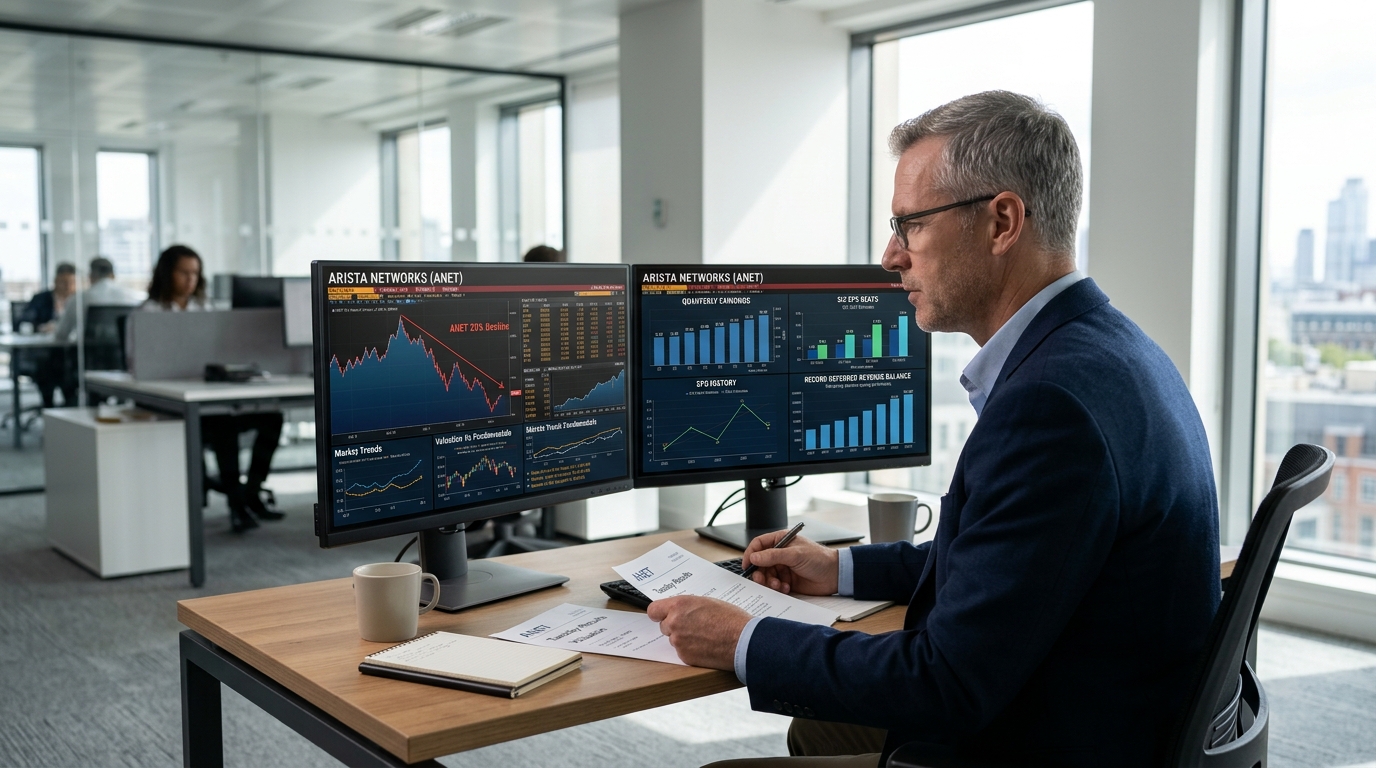
Arista Networks reports Q3 2026 results Tuesday after the close, and the company enters that call with a peculiar problem: the business is outperforming, the stock is not. ANET has shed roughly 20% from its October 9, 2026 high, and shares have pulled back nearly 10% in the last month, even as the fundamental case has improved. That gap is exactly why this report deserves close attention.
The Business
Arista builds and sells the high-speed Ethernet networking switches that underpin AI data centers at Microsoft, Meta, and a growing list of hyperscalers. Its software layer, CloudVision, provides the automation and telemetry that hyperscale operators need when running clusters at scale. The business is narrow by design, and that focus shows in the economics. Arista’s operating margin ran at 45.4% on a GAAP basis (49.9% non-GAAP) in Q2 2026, versus roughly 24.6% GAAP (34.6% non-GAAP) for Cisco in its fiscal Q2 2026. Cisco offers a broader portfolio; Arista offers a purer one.
Revenue grew 37.7% year over year last quarter to $3.04 billion, Arista’s first $3 billion quarter. Non-GAAP EPS of $1.02 extended Arista’s EPS beat streak to six consecutive quarters. For Q3, management guided to roughly $3.3 billion in revenue, 63% gross margin, and EPS between $1.06 and $1.08. Analysts consensus sits at $3.33 billion in revenue and $1.08 in EPS, implying 44% year-over-year growth.
Why Wall Street Is Paying Attention
The AI networking market is growing faster than anyone projected 18 months ago, and Arista holds the high-performance Ethernet position that hyperscalers prefer for scale-out deployments. Demand is outpacing what the company can ship, which is a strong position heading into a report. Deferred revenue rose to about $6.87 billion from about $4.06 billion last quarter, and non-cancellable purchase commitments stood at $9.7 billion, both signals of locked-in forward demand. For fiscal 2026, Arista raised full-year revenue guidance to $12.6 billion, representing roughly 40% annual growth. That guidance raise came after the record Q2 result, not before it.
The sector rotation context matters too. Capital is leaving semiconductors and rotating toward software and networking, according to fund flow data from StoneCastle Investment Management’s Bruce Campbell. Arista sits at the intersection: it is hardware, but it runs on proprietary software, which is where margins and defensibility actually live. Institutional ownership trends have been constructive, and analyst estimate revisions over the last 90 days have moved higher, not lower.
What Could Go Wrong
The honest answer is valuation. At roughly 53 times trailing earnings and 44 times forward EPS, Arista carried a premium into this selloff. When the stock dropped 13.6% after Q1 despite a 7.7% earnings beat, the market sent a message: this multiple requires flawless execution and strong guidance, not just good numbers. Cisco is catching up in AI networking, closing fiscal 2026 with $9.3 billion in hyperscaler AI infrastructure orders, about 4.5 times the fiscal 2025 level. HPE, with its Juniper acquisition, is also gaining enterprise share. Neither competitor threatens Arista’s core hyperscaler position today, but the competitive landscape is tightening.
Going into Tuesday, the risk-reward is cleaner than the stock price implies. Six consecutive beats, record deferred revenue, 44% expected revenue growth, and a 20% discount to recent highs. The question tomorrow is whether management raises full-year guidance again, and whether the Q4 outlook exceeds the $3.5 billion that would keep the 40%-growth story intact. History says Arista delivers. The stock’s recent behavior says history alone is not enough.