November 2, 2026
Bonus Content: Oil Just Dropped $7 Overnight. Here Is What That Means for Energy Stocks and Inflation.
Silver and gold are posting notable moves, with asymmetric upside now taking shape for well-positioned investors.
The focus: early-stage, small-cap discovery stories that are only beginning to unfold.
The opportunity is taking shape across a historic North American silver-gold district that generated high-grade production at surface for generations, yet was never evaluated as a unified geological system.
The reason had nothing to do with the metals — the land package was highly fragmented and was never assembled under single ownership until now.
That has now changed.
For the first time, this small-cap explorer has consolidated the entire district under one roof — allowing modern geology and drilling to test the system properly from surface to depth across kilometers of previously undrilled mineralization.
The exploration calendar is active.
Phase-2 drilling is under way, with a near-term pipeline of potential results expected to sharpen the discovery picture as the program advances.
And there is additional scope beyond the primary district.
A second nearby district-scale silver-gold asset extends the exploration runway further for this emerging small-cap.
We’ve put together a complimentary online report with full details, including:
✓ A newly consolidated district-scale silver-gold system in North America
✓ What the first drill results are already confirming
✓ Which targets are next in the drill program
✓ How a second district-scale asset expands the discovery profile
✓ Key 2026–27 catalysts as drilling intensifies
The report also includes an in-depth interview with the company’s president & CEO — a firsthand account of where this program is headed and why the current phase of drilling carries significance for the broader district thesis.
Access the complimentary online report here and see why this sub-US$1 silver-gold explorer is drawing attention as an early-stage position ahead of its 2026–27 drilling catalysts.
Oil Just Dropped $7 Overnight. Here Is What That Means for Energy Stocks and Inflation.
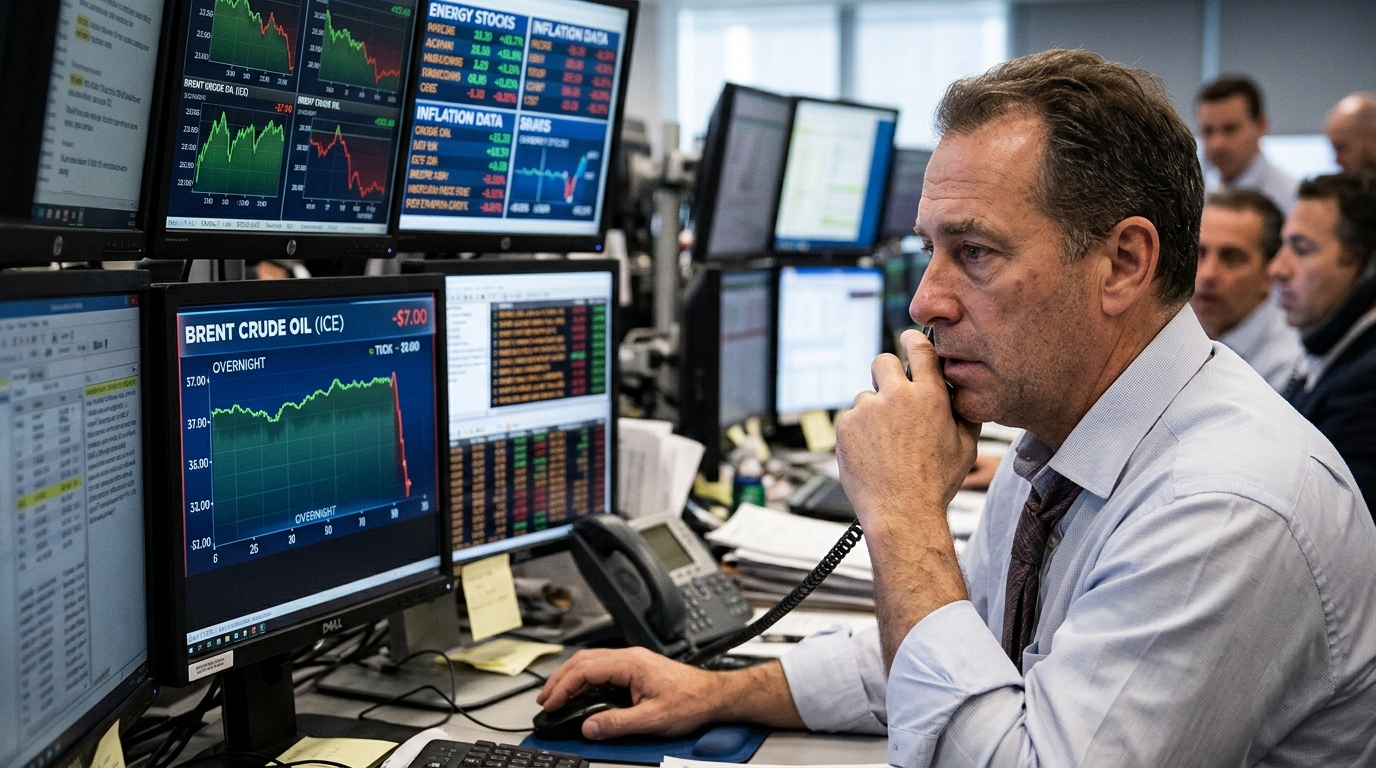
One phone call changed the calculus for every energy position on the board. Overnight into Monday, Brent crude fell more than 3% to roughly $109.75 a barrel and WTI slid to around $100.69, erasing all of Friday’s gains in a single session. The catalyst: a report, first carried by Axios and echoed across other outlets, that President Trump told Israeli Prime Minister Netanyahu he prefers giving Iran more time for diplomacy rather than resuming military strikes immediately after Tuesday’s midterm elections.
The war premium just reset. Markets had spent the final week of October trading a specific dated risk: the Associated Press reported that U.S. officials warned regional allies to prepare for the possibility of strikes shortly after Tuesday’s election. Brent had climbed from the low $110s to a late-October high around $118 on that framing. Today’s move erases that premium in one session. Brent is now down roughly $7 from its recent peak, and UBS, which in mid-October raised its year-end Brent forecast to $100, looks more prescient than it did 48 hours ago.
What It Does to Energy Earnings
For the integrated majors, the directional hit is real but context matters enormously. ExxonMobil reported Q3 adjusted EPS of $4.23 on $113.2 billion in revenue last Thursday, doubling year-over-year GAAP earnings to $15.4 billion. The critical detail: refining, not upstream, drove the beat. XOM’s Energy Products segment earned $9.05 billion in the quarter, with Gulf Coast refineries running at 100% crude unit utilization. A softer crude price actually compresses refining feedstock costs before it compresses crack spreads, so the margin arithmetic is not as straightforwardly negative as the headline move suggests.
Chevron posted Q3 adjusted EPS of $5.28, also ahead of the $4.89 consensus, with its downstream business recording its strongest quarterly earnings in at least six years. Both stocks touched all-time highs on October 30. The question now is whether that multiple can hold at sub-$110 Brent. XOM traded at roughly 19 times trailing earnings at $187.25, a valuation that embeds crisis-level refining margins persisting. Diamondback Energy reports Q3 results today after the close, with consensus near $4.92 in EPS on about $4.29 billion in revenue. That number was modeled at oil prices materially above where WTI sits this morning.
Airlines: A Rare Beneficiary
The airline sector has been absorbing pain since late February. Jet fuel sat at $4.44 per gallon as of October 27, up roughly 90% since the Iran war began, according to the Argus US Jet Fuel Index. Delta’s CEO had guided to a $6 billion full-year increase in fuel costs. American Airlines reported a Q3 loss it attributed almost entirely to $1.9 billion in incremental fuel expense, nearly 70% more than the prior-year period. A sustained return toward $100 Brent, if today’s diplomatic signal holds, begins to claw back meaningful margin for Q4 and into 2027 planning cycles.
The gap between carriers matters as much as the sector move itself. Delta and American face the same jet-fuel shock but carry very different structural capacity to absorb it.
The Inflation Angle
This is where the Fed watches closely. The Iran war’s energy shock has been estimated to add 1.5 to 2 percentage points to cumulative inflation across 2026 and 2027. The Dallas Fed’s structural VAR modeling showed one-year inflation expectations pushed up by as much as 0.5 percentage points in Q3 alone. A durable de-escalation at $110 Brent, rather than the feared resumption of strikes driving prices back toward the recent $118 high, meaningfully softens that forward path. Crucially, long-run inflation expectations have remained anchored throughout the conflict, giving the Fed room to treat the energy pass-through as transitory if the geopolitical ceiling on crude holds.
The valuation question runs alongside the inflation question. Energy equities have already priced a sustained high-crude environment, which changes the risk-reward math if the geopolitical ceiling holds.
Scenario Modeling
Bull Case: Qatar-mediated talks produce a framework agreement within two weeks. Brent retreats toward $100, airlines recover materially in Q4, and refining names consolidate gains rather than collapse. XOM and CVX hold near recent highs on strong cash generation.
Base Case: Diplomacy extends through November without a deal or resumed strikes. Brent ranges $105 to $115, war premium remains partially embedded, and FANG’s Q3 print tonight sets the tone for pure-play Permian names through year-end.
Bear Case: Negotiations collapse post-midterms and strikes resume by November 10. Brent re-tests $118 and potentially probes the $125 level some sell-side desks have outlined in escalation scenarios. Airlines face another leg lower, and the Fed faces renewed pressure to hold rates higher for longer into 2027.
Trader Framework
The $110 level in Brent is now both a technical and a narrative fulcrum. A close below it today confirms the premium has fully cleared; a reversal back above it signals traders are skeptical the diplomatic window survives past Tuesday’s vote. For energy equities, watch whether XOM and CVX open lower and stabilize or continue sliding, which would indicate the market is resetting forward earnings assumptions rather than just reacting to the headline. FANG’s report tonight carries extra weight: a Permian pure-play that guided above $4.92 EPS into a $100 WTI environment reads very differently than one that guided assuming $108.
Volatility in crude is not a reason to abandon positioning; it is a reason to size it against defined levels. The overnight move removed one specific risk but introduced another: diplomatic outcomes are binary and their timing is unpredictable. Preparation, not prediction, is the edge here.