Silver and gold are obliterating all previous profit records with next-level gains now on-deck for well-timed investors.
We’re talking early-stage, small-cap discovery stories that are only just beginning to unfold.
The early-stage opportunity is taking shape across a historic North American silver-gold district that helped build early fortunes but was never explored as a unified system.
For generations, the district produced high-grade metals at surface.
Yet, the deeper story was never told – not because the metals weren’t there but because the land package was highly fragmented and never explored as a single system.
That has now changed.
For the first time ever, this exceptionally well-run small-cap explorer has brought the entire district under one roof – enabling modern geology and drilling to finally test the system properly from surface to depth across kilometers of previously untouched mineralization.
And the timing couldn’t be better.
Phase-2 drilling is accelerating as you read this… setting up a near-term flow of potential needle-moving results as the discovery picture sharpens.
And that’s not all.
Add in a second nearby district-scale silver-gold asset… and the exploration runway expands even further for this emerging small-cap.
We’ve put together a FREE online report with all the details, including:
✔ A newly unified district-scale silver-gold system in North America
✔ What the first drill results are already confirming
✔ Which targets will see drilling next
✔ How a second district-scale asset expands the discovery upside
✔ Key 2026-27 catalysts as drilling intensifies
Inside, you’ll also find our exclusive, in-depth interview with the company’s president & CEO who brings a true firsthand look at where this discovery is headed next and why the timing is so critical.
Click here to access our FREE online report and see why this Sub-US$1 silver-gold stock is setting up to be one of the most compelling early-stage opportunities of 2026-27.
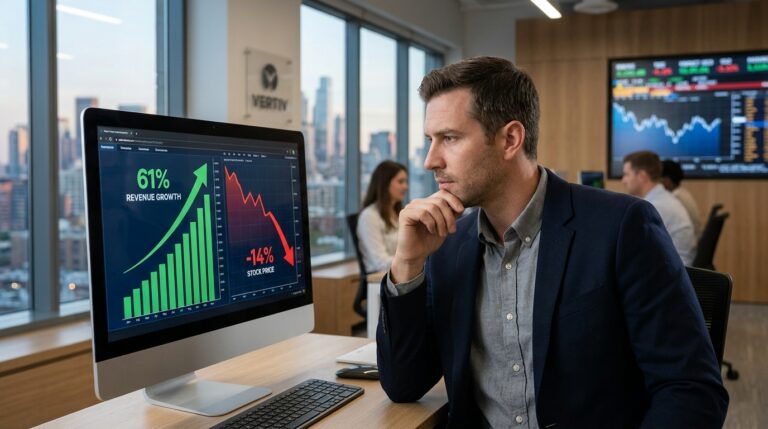
AppLovin Just Posted 55% Revenue Growth. The New Model Isn’t Fully Live Yet.
AppLovin’s Q3 results landed Wednesday after the close and the stock answered Thursday morning with a 31% surge, closing near $356. The move is rational on the numbers. What is worth examining now is whether the market has priced the finished engine or just the first half of it.
What the Quarter Actually Said
Net income grew 72% year-over-year to $1.44 billion on record revenue of $2.18 billion, up 55%, with a 66% net income margin and an 84% adjusted EBITDA margin. Both metrics beat the high end of management’s guidance by about $100 million. Free cash flow was $1.4 billion for the quarter.
Gaming revenue grew nearly 50% year-over-year, driven by partial rollout of next-generation model architecture, while consumer advertiser spend increased triple digits year-over-year and double digits sequentially. The consumer vertical remains a small portion of the mix, which is exactly the point for forward modeling.
The Model Rollout Is the Variable
The Q3 beat did not come from a completed system. CEO Adam Foroughi confirmed the company only partially rolled out a new generation of advertising models during the quarter. J.P. Morgan analysts believe the new architecture provides greater room to improve advertising performance than the existing one, and better advertiser results could encourage existing customers to increase spending while attracting new ones. The full rollout remains pending, and management did not commit to a specific timeline.
AppLovin guided Q4 2026 revenue to $2.365 billion to $2.395 billion and adjusted EBITDA of $1.995 billion to $2.025 billion. That represents 43% to 44% year-over-year growth, above analyst consensus of roughly $2.25 billion. However, the implied 8% to 10% sequential growth decelerates from Q3’s 14% sequential step-up.
Technical Framework
APP’s 52-week range runs $225.19 to $738.01, and Thursday’s close near $356 sits in the lower third of that band. The post-earnings gap reclaims the 50-day moving average region. Key resistance sits in the $420 to $450 zone, which aligns with the consensus analyst target of about $448, implying roughly 26% further upside from current levels. RBC raised its target to $520, keeping an Outperform rating. Support on a pullback sits near $310 to $325, the pre-earnings base. Volume on the gap day ran well above average, a constructive sign for follow-through.
The programmatic ad market that APP is expanding into has its own fault lines. The Trade Desk’s collapse from $91 to roughly $17 shows how quickly advertiser confidence can reprice a platform’s multiple.
Scenario Modeling
Bull case ($500+): Full deployment of next-generation models accelerates gaming revenue beyond the current 50% growth pace while the consumer vertical crosses 15% of total revenue. EBITDA margins hold above 84%, and the $3.6 billion buyback authorization provides a floor.
Base case ($380 to $450): Management’s stated long-term target of roughly 20% to 30% annual growth holds, with model improvements arriving unevenly by quarter. Consumer advertising grows from a still-small base, keeping the growth rate elevated without a step-change acceleration.
Bear case (below $300): Self-serve onboarding dilutes ad spend quality as the platform scales beyond its core gaming audience. Any miss on Q4’s $2.38 billion midpoint, against already-elevated expectations, risks reversing the gap.
Active Trader Framework
The asymmetry here sits in the incomplete model rollout. A platform delivering 55% revenue growth and 84% EBITDA margins with its next-generation architecture still partially deployed carries a different risk profile than one running at full capacity. Traders should monitor whether Q4 consumer vertical spend sustains its triple-digit year-over-year pace. A deceleration there is the leading indicator of multiple compression, not gaming. Position sizing matters: APP carries a beta of 2.50, meaning it amplifies broader market moves in both directions.
Preparation beats prediction here. The model completion timeline is unknown. The revenue potential, once it arrives, is not.