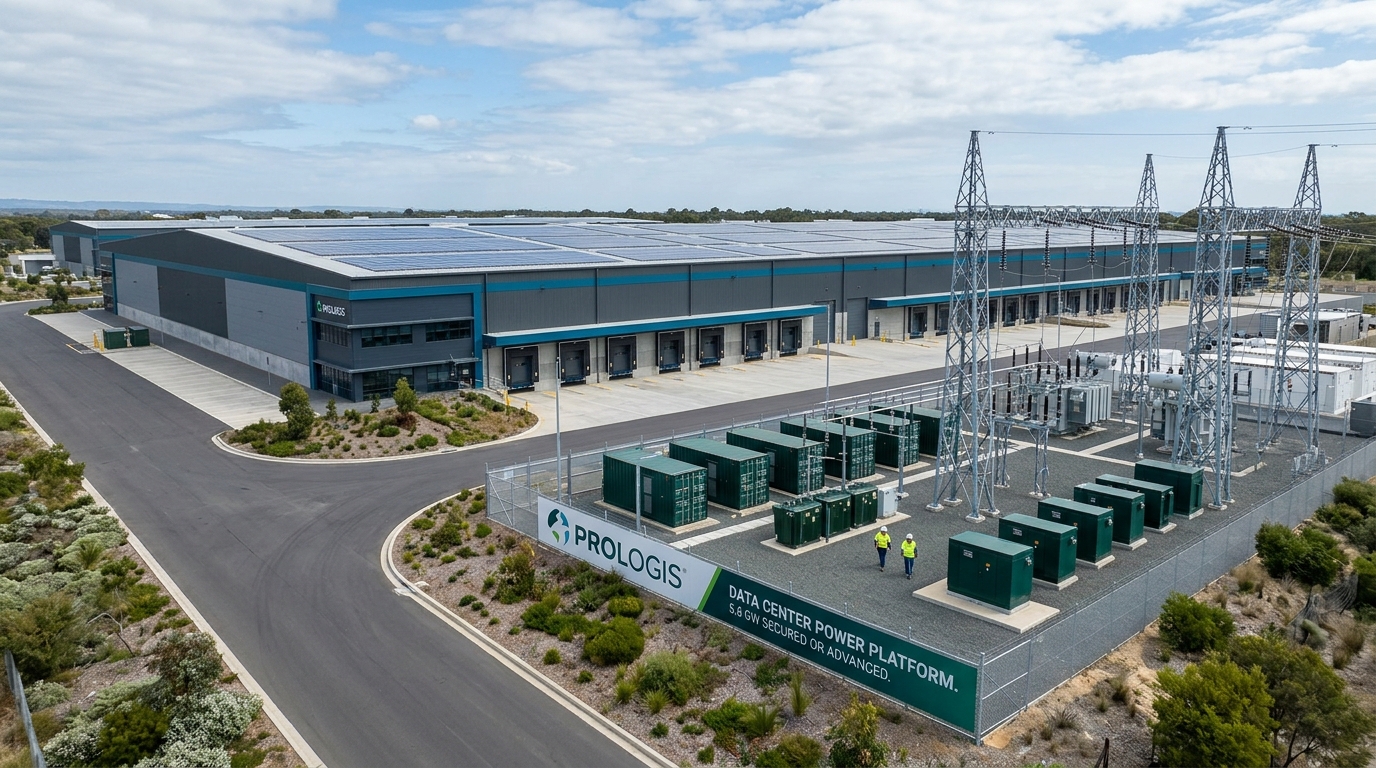
Prologis is no longer purely an industrial REIT. The numbers make that plain. As of Q3 2026, the company disclosed a data center power pipeline of 5.8 gigawatts secured or at an advanced stage, comprising 1.7 GW of secured power, including 680 megawatts already under development, and 4.1 GW at advanced stage. That is not a pilot program. That is a utility-scale infrastructure platform housed inside a logistics company.
The underlying operating business is healthy by any measure. Prologis reported Q3 2026 Core FFO of $1.60 per share, with 95.6% occupancy and a 38% rent change on rollover. Total revenue rose about 8% year over year to roughly $2.39 billion. Full-year Core FFO guidance now stands at $6.25 to $6.29 per share.
The Energy Angle the Market Is Still Underweighting
The conventional framing treats PLD’s data center conversion as a real estate story. It is actually an energy access story. A key enabler of these conversions is Prologis’s energy procurement strategy: by leveraging scale and relationships with utilities and energy providers, the company is securing power access that enhances its land portfolio and enables conversion of select logistics sites into energy-ready data center developments.
Management has said it began investing more aggressively in energy several years ago and has surpassed 1 gigawatt of installed solar generation supported by storage across its owned and managed properties. That installed base gives Prologis a head start competitors cannot replicate quickly: a 1.3 billion square foot global footprint already wired into the grid.
Data centers are projected to comprise about 40% of the company’s $4 to $5 billion estimated 2026 development starts. Prologis has also pointed to thousands of acres in its land bank as potential data center sites, depending on power availability and permitting.
Scenario Modeling
Bull Case: The SEGRO combination closes on schedule, expanding the European portfolio to about 368 million square feet and adding prime land near dense European population centers. Data center build-to-suit announcements accelerate. PLD re-rates toward $160 as the market ascribes a higher multiple to the infrastructure segment.
Base Case: Core FFO lands near the top of the $6.25 to $6.29 guidance range. Embedded lease mark-to-market remains positive and provides a durable organic growth floor. PLD holds the $125 to $140 band as rates stay elevated and capital deployment stays disciplined.
Bear Case: If rate pressure persists and hyperscaler capex slows into 2027, Prologis’s balance sheet and funding costs become the dominant conversation. Support at $115.
Trading Framework
PLD’s MACD turned positive in late October. Market conditions still show a meaningful gap between replacement cost rents and current market levels, which can limit downside on the logistics book even if the data center premium compresses. Traders should watch $129 as near-term support and the Q4 development starts figure as the catalyst that confirms or questions whether the 5.8 GW pipeline is translating into revenue-generating assets. Position sizing should account for interest rate sensitivity: PLD carries meaningful duration risk alongside its infrastructure optionality.
Power access is only one constraint on the 5.8 GW pipeline. Switchgear and transformer lead times now stretching beyond four years are the physical bottleneck that can delay even fully funded data center projects.
Disciplined traders do not need to predict the SEGRO close or the next rate decision. The levels are defined. The pipeline is documented. Preparation is the edge.