September 15, 2026
Bonus Content: Wall Street Is Split on Apple at $326
Some market shifts are simply too large for investors to ignore.
The global drone industry was valued at $83.8 billion in 2025. By 2033, it is projected to reach $182.4 billion.
That is nearly 118% growth in eight years.
And this is no longer just a commercial technology story.
Washington is treating drones as a national priority. The Pentagon reportedly wants around 300,000 of them, while the government pushes to expand domestic manufacturing and secure American supply chains.
For investors, rapid market growth and government demand can be a powerful combination.
One overlooked Nasdaq company has spent more than 25 years developing professional drone systems.
It does not just build aircraft. Its platform brings together software, AI and advanced sensors, backed by professional services and real-world deployments.
Yet its shares are still trading around $5.
Markets projected to more than double rarely keep the same winners forever. If America leads this buildout, this quiet Nasdaq could become much harder for Wall Street to overlook.
Wall Street Is Split on Apple at $326
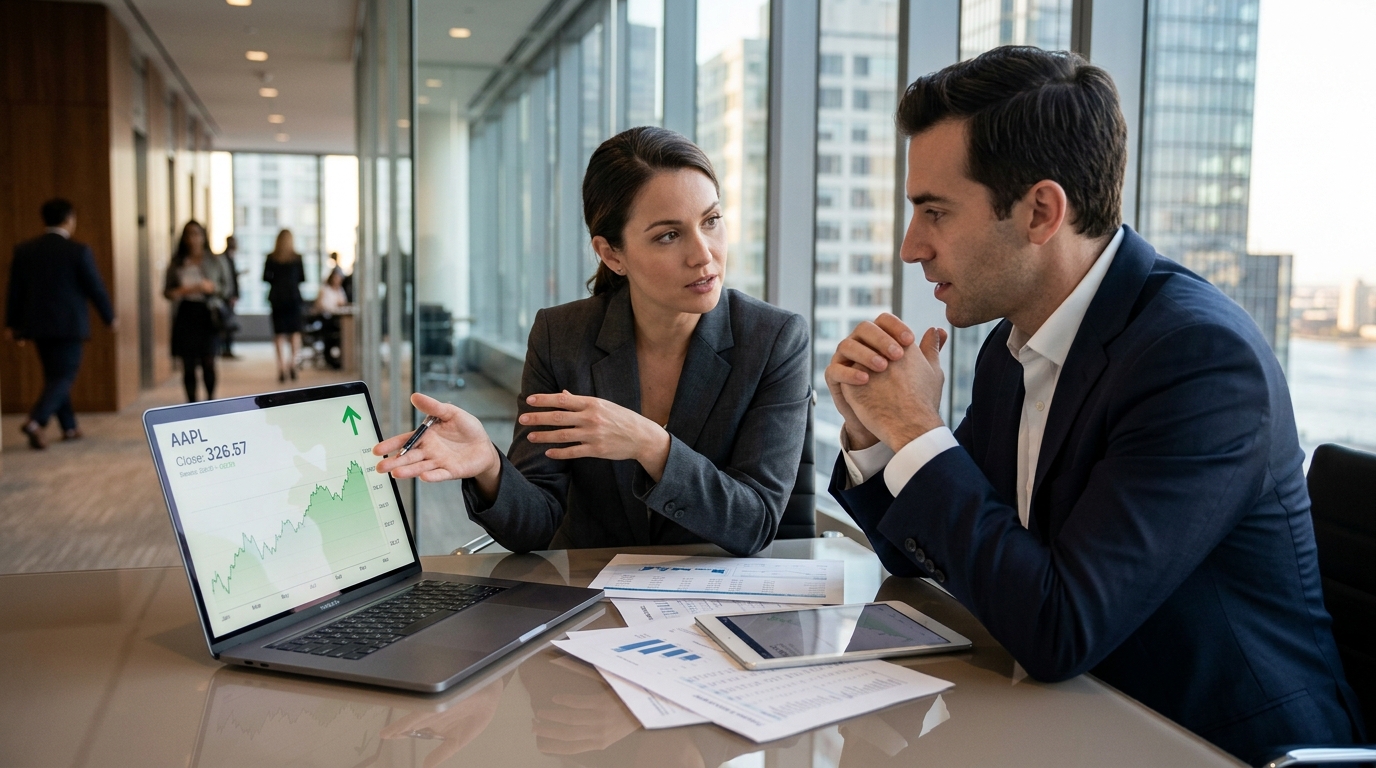
Apple closed at $326.57 on September 10, up 3.56% on the session, outperforming a broadly weaker market the day after its fall event. That move was tidy. The analyst reaction behind it was anything but.
Bullet Summary
- AAPL gained 3.56% on September 10, closing at $326.57.
- TD Cowen leads the bull camp with a $400 target, implying roughly 22.5% upside from the September 10 close.
- Citi maintains Buy at $365; Morgan Stanley holds Overweight at $360; Bank of America Buy but cut to $370 from $380.
- Barclays sits at the opposite extreme: Sell-rated with a $245 target, implying a roughly 25% drawdown.
- The iPhone Duo starts at $1,999, with pre-orders opening October 16 ahead of an October 23 retail date; iPhone 18 Pro pre-orders opened September 12 ahead of a September 18 retail date.
- Apple’s fiscal Q3 revenue rose 16% year over year; management guided for slower September-quarter revenue growth, creating the valuation tension traders are navigating now.
- On September 10, AAPL’s intraday high was $326.74 and the intraday low was $316.51. The high-low spread from $245 to $400 across major price targets is unusually wide for a post-event coverage reset.
The Margin Problem Behind the Upgrade Cycle Story
Bank of America’s Wamsi Mohan reiterated a Buy but cut his price objective to $370 from $380, with the new iPhones pricing below his model assumptions and elevated memory component costs putting pressure on gross margin. That is a meaningful tell. When a bullish analyst lowers a target on the day of a major launch, the subtext is that the volume story has to compensate for a thinner per-unit take.
Mohan called the iPhone Duo the show-stealer, arguing the foldable display brings iPad-like productivity to a phone and opens a broader addressable market that could become more mainstream over time. That long-cycle framing matters. It says the upgrade thesis is a 2027 and 2028 story, not a September quarter event.
Citi went further, describing the iPhone Duo as “Apple’s biggest new hardware category since the watch and AirPods.” At $365, Citi is pricing in that category expansion. Barclays’ Tim Long took the opposing view, rating AAPL a Sell with a $245 target, the starkest bearish call of the post-event coverage wave.
What the Siri Angle Adds
Siri AI is moving closer to being a functional part of daily life rather than a keynote promise, with Apple pushing deeper into personalized, context-aware intelligence across its product lineup. The upgrade cycle math depends heavily on whether that lands. Analysts flagging upside point to iPhone Duo excitement and Siri AI driving upgrade intent, while the key risk is that Duo demand disappoints and Siri features fail to move upgrade behavior, forcing price cuts that compress margins further.
Technical Framework and Scenario Modeling
AAPL’s technical condition remains moderately bullish, with shares above the 200-day moving average; a break above $329.10 could put the prior highs at $343.50 to $345.14 back in focus.
Three scenarios frame the trade. Bull case: iPhone Duo pre-orders surprise to the upside before the October 23 ship date, early iOS 27 adoption supports the upgrade pull-forward, and AAPL reclaims $343. Base case: the stock consolidates between $315 and $329 as the market waits for Apple’s fiscal Q4 results later in October and early Duo sell-through data. Bear case: margin pressure from component costs widens, Duo volumes underwhelm at $1,999, and the stock revisits $295 support.
Positioning Considerations
The five-to-four Buy-to-Neutral split among the ten major post-event notes is not a green light. It is a framework for sizing. Traders leaning long have a defined technical level at $329.10 to key off. Those hedging margin risk have BofA’s own model revision as a data point. Neither camp should treat the analyst divide as noise. It is the trade.
Preparation here means watching the October 16 Duo pre-order open and Apple’s late-October earnings call for gross margin guidance, not the stock price on any single session.