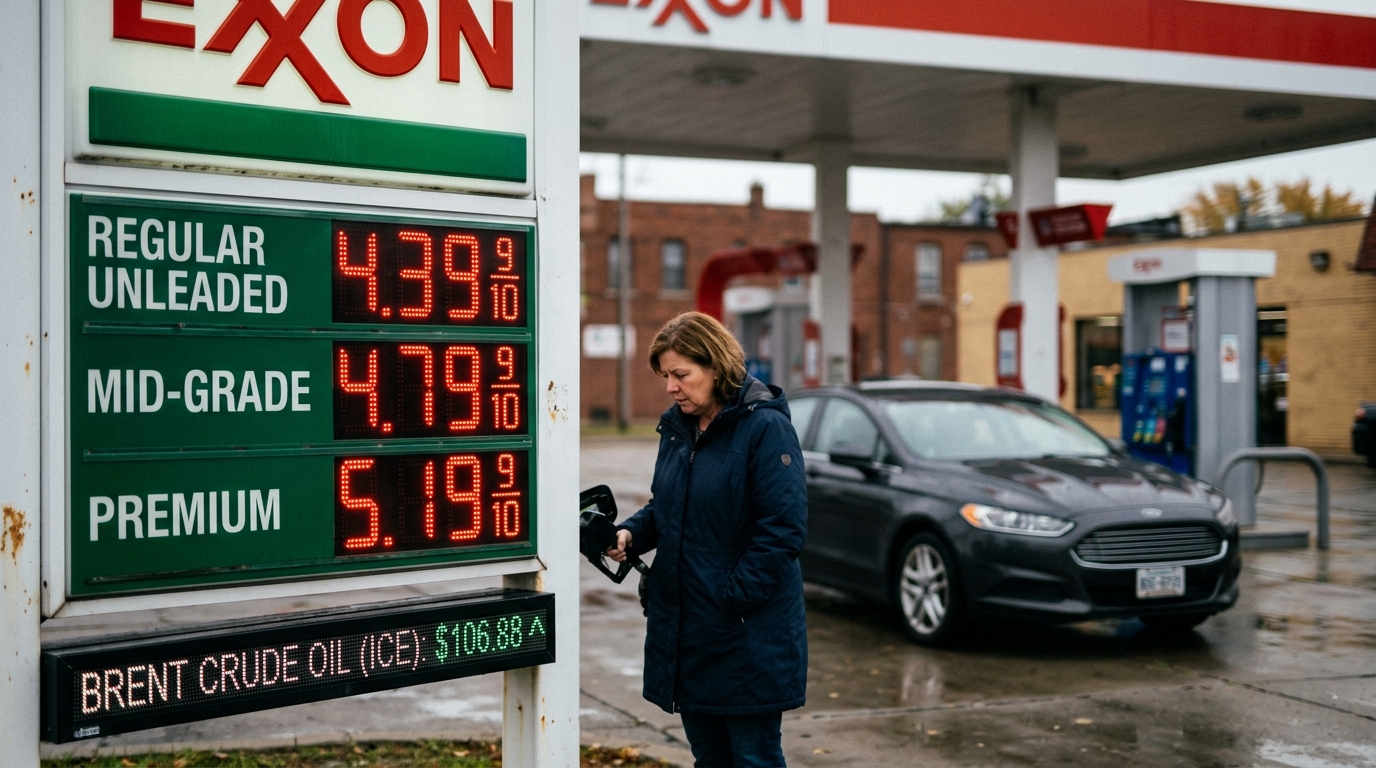
At 10:00am ET this morning the University of Michigan publishes the preliminary October consumer sentiment reading, and the stakes for rate markets are unusually high. The index sat at 48.1 in its September final, the second-lowest reading in the survey’s 74-year history. Consensus is 47.5-47.6. The all-time low, set in May when the Iran conflict sent Brent above $100 and Hormuz tanker traffic collapsed, was 44.8. The gap between today’s expected number and that floor is smaller than most people realize: 2.8 points.
That proximity matters for a specific reason. This release is not just a barometer of household mood. It arrives alongside year-ahead inflation expectations, which jumped to 4.6% in September, the highest since June. The Federal Reserve’s most recent meeting minutes flagged survey-based short-term inflation expectations as elevated. So whatever the headline does, the inflation expectations component will receive equal scrutiny at the Eccles Building.
The fuel backdrop feeding into October’s survey window is worse than September’s. The AAA national average hit $4.36 per gallon this week, a record for this time of year. Brent has surged above $105 this morning, up more than 5% in a single session, as Hormuz tanker traffic hit a two-month low. Gas prices were the loudest driver of May’s all-time low, cited by roughly one-third of respondents at the time. They remain the most direct transmission mechanism from geopolitics to household psychology.
What Each Outcome Does to December
December is the meeting that matters. Markets are pricing roughly an 82% probability that the Fed holds at its October 27-28 meeting. December, though, is a live question. Multiple sources tracking Fed funds futures put the probability of a December hike in a wide range, with a minority case for a hold. The Fed’s September minutes showed that all participants supported the most recent rate increase, with many officials saying another hike would likely be appropriate before year-end.
A sentiment print that breaches 46 and accompanies a spike in year-ahead inflation expectations above 5% complicates the Fed’s calculus in a specific way. Higher expectations, if sustained, push the Fed toward tightening further to prevent the psychology from becoming self-reinforcing. That would harden December hike pricing. A headline below 46 accompanied by unchanged or falling inflation expectations is the more ambiguous outcome: it signals demand destruction severe enough to argue against more tightening, but without confirmation that expectations are re-anchoring, the Fed may still lean hawkish.
A result that holds near 47-48 and shows steady or declining inflation expectations is the outcome most likely to keep December hike odds where they sit. That is the market’s base case.
Where It Shows Up
XRT, the equal-weighted retail ETF, is the cleanest real-economy lever here. It tracks the broad spectrum of consumer-facing names, and extended weakness in Michigan sentiment has historically preceded margin compression across specialty and discretionary retailers. The fund closed near $82.63 recently after a difficult stretch in which the internal composition has shown severe dispersion between discount operators and higher-ticket segments.
Within that dispersion, Walmart and Target read differently. Walmart’s traffic has remained resilient, with consumers described as value-seeking and fuel-sensitive. Target, which reported management caution even as Q1 showed some consumer strength, is more exposed if sentiment deteriorates further. A print near or below 46 would reinforce the trade-down dynamic that has separated these two names most of this year.
Risks and Counterpoints
The strongest bear case for the sentiment reading is also the strongest bull case for rate markets: if today’s number bounces toward 50, it would suggest the consumer is proving more durable than the headline trend implies. On Polymarket, traders have the final October figure with meaningful weight in the 49-51.9 range, suggesting the prediction market crowd thinks a modest rebound is plausible. Households with equity exposure have reported substantially stronger sentiment than those without, and equity markets have not confirmed the distress the Michigan index is signaling.
The bull case for sentiment, in other words, is that the index has been measuring geopolitical anxiety rather than real spending impairment. The retail sales data, which has not collapsed even as the index has, would support that interpretation.
What to Watch Next
Beyond the headline, track the year-ahead inflation expectations figure and whether it holds at 4.6% or moves materially in either direction. The September CPI report arrives October 14, the next significant piece of data before the October Fed meeting. Brent’s behavior into the close today, given this morning’s sharp move, will also tell you something about whether energy anxiety is fading or building into the survey window.