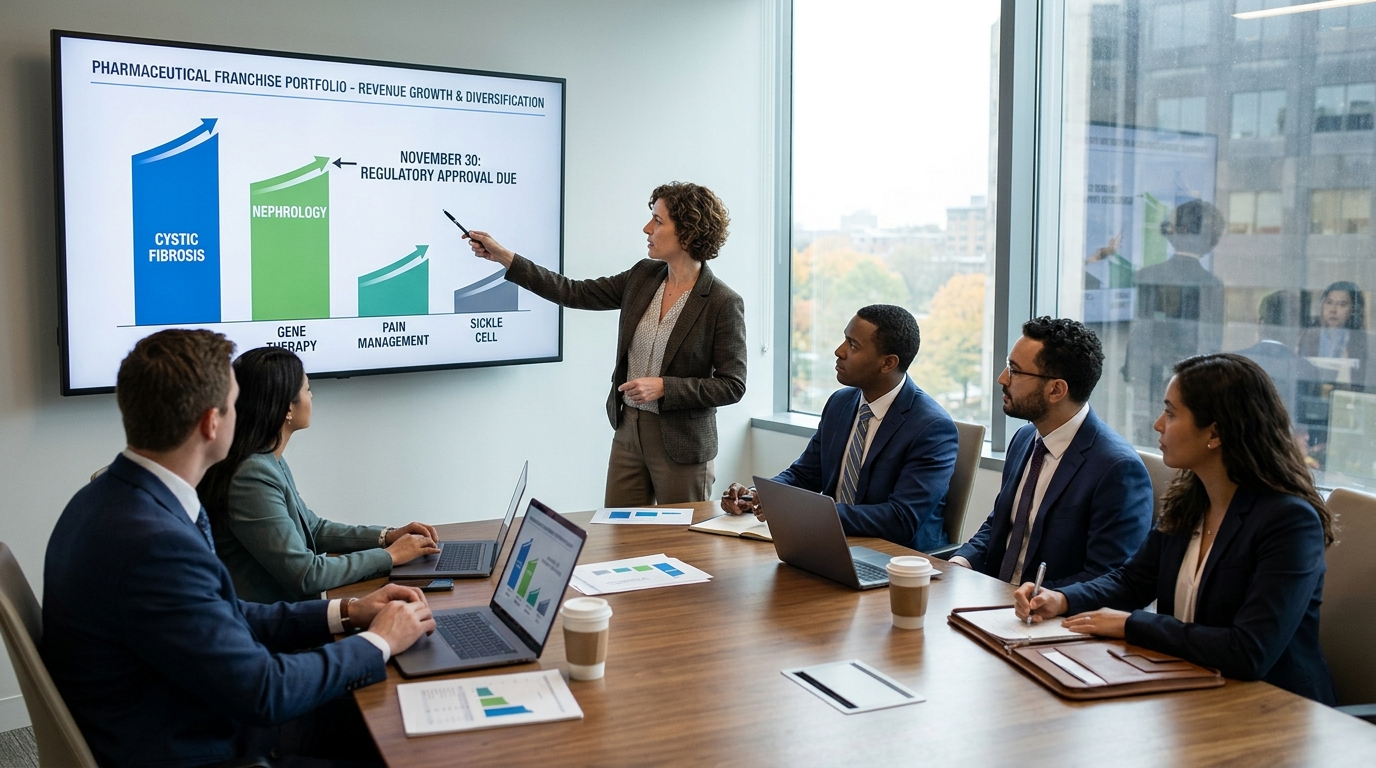
Vertex Pharmaceuticals reported Q3 results three days ago and immediately raised full-year guidance again. The numbers are becoming a pattern: consistent, non-cyclical, and bigger each quarter. What traders need to focus on now is not the CF base that everyone already understands. It is what happens on November 30.
The Franchise Map
CF remains the anchor. Total CF product revenue in Q3 hit $3.273 billion, with TRIKAFTA/KAFTRIO contributing $2.437 billion and ALYFTREK adding $706 million. That is 8% year-over-year CF growth.
Vertex raised full-year 2026 total revenue guidance to $13.15 billion to $13.25 billion. The CF machine is funding everything else.
The November 30 Event
This is the catalyst the market is pricing now. The BLA submission for accelerated approval of povetacicept in IgAN is under priority review by the FDA, with an assigned PDUFA target action date of November 30, 2026.
The Phase 3 RAINIER data are hard to dismiss. The interim analysis showed povetacicept delivered a statistically significant 49.8% UPCR reduction versus placebo at week 36, with a percent change from baseline of -52.0% in the treatment group versus -4.3% for placebo. Povetacicept has pipeline-in-a-product potential and represents a potentially best-in-class approach to control B cell activity in IgAN, primary membranous nephropathy, and generalized myasthenia gravis. One drug, three addressable markets.
JOURNAVX: The Prescription Inflection
The pain franchise is moving faster than the revenue line suggests. In Q3, JOURNAVX prescriptions totaled over 750,000, up more than 40% quarter-over-quarter. JOURNAVX revenue was $58 million in Q3, up 18% quarter-over-quarter and nearly tripling the $20 million reported in Q3 2025.
The disconnect between prescription velocity and revenue is intentional: a patient support program is subsidizing gross-to-net while payer coverage broadens. Management has said it plans to keep the patient support program in place into 2027 and sunset it by mid-2027, with gross-to-net expected to stabilize around 50% to 60% thereafter. Traders watching JOURNAVX need to track the gross-to-net normalization, not just the top-line number.
Balance Sheet as Strategic Weapon
Vertex completed its acquisition of Crinetics Pharmaceuticals on September 1, 2026. Guidance now embeds $40 million to $50 million in PALSONIFY revenue from that transaction.
Vertex is not the only large-cap pharma using acquisition capital to build a post-single-franchise identity. AbbVie’s Skyrizi and Rinvoq have already surpassed Humira revenue, showing how quickly a replacement portfolio can invert the old dependency math.
Scenario Framework
Bull case: Povetacicept earns accelerated FDA approval November 30, launching nephrology as pillar five. JOURNAVX gross-to-net normalizes after the PSP is sunset by mid-2027, converting prescription momentum into more direct revenue flow. CF stays at high-single-digit growth.
Base case: Approval comes on the PDUFA date with a standard label. JOURNAVX revenue grows but gross-to-net normalization is delayed until after the PSP sunset by mid-2027. Full-year 2026 revenue lands near the $13.2 billion guidance midpoint.
Bear case: FDA requests an advisory committee or issues a complete response letter on povetacicept, pushing nephrology launch to late 2027. JOURNAVX payer coverage gaps persist into 2027, leaving the $500 million or more non-CF revenue ambition for CASGEVY and JOURNAVX combined underpowered. CF growth decelerates below 5% as ALYFTREK switches mature.
Trader Framework
The November 30 PDUFA date is a binary event that the options market is likely already pricing. Traders should map their exposure to that date specifically: approval compresses the CF-concentration discount in the multiple; a setback resets the nephrology timeline by 12 to 18 months. Beyond that event, the JOURNAVX gross-to-net inflection and the expected PSP sunset by mid-2027 are the operational signals to track. What remains is execution risk on two commercial ramps simultaneously.