Dear reader,
This stock trades for under $5 today.
Dr. Mark Skousen believes it could hit $50 by January 1st.
Why?
It’s one of the top stocks Elon Musk is targeting.
He’s revealing the key details in his latest briefing.
Click here for the story before it’s too late to take advantage.
Good investing,
Rachel Gearhart
Publisher, The Oxford Club
Target Reports in 12 Days. The Valuation Gap Is the Trade.
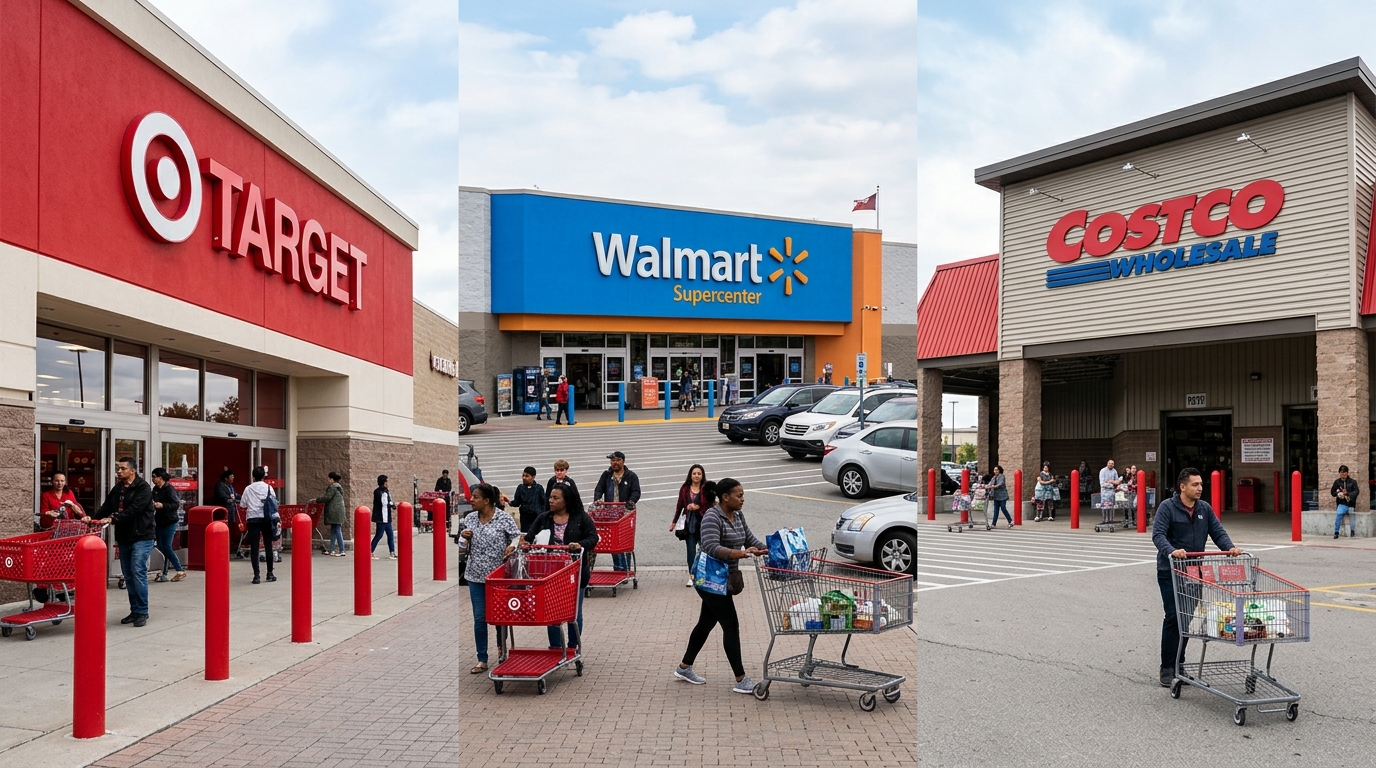
Target Corporation trades at a forward price-to-earnings multiple in the mid-to-high teens. Walmart and Costco trade at materially higher forward multiples. That spread rarely resolves through the premium names compressing. It more often resolves through the cheap one rerating higher, or through the cheap one delivering a reason it deserved the discount all along. The November 18 earnings report, twelve days out, is the event that decides which.
Market Context
TGT closed Friday near $157.95, off its 52-week high of $170.75 but far above the $83.44 trough from earlier this cycle. The stock carries a trailing P/E near 16.4x. The forward multiple is in the mid-to-high teens on current consensus. TTM revenue is roughly $108 billion. The ex-dividend date lands November 10, 2026, with a $1.16 quarterly payout attached, putting the forward yield around 3% at current prices. Target’s dividend growth streak is 55 consecutive years, not 57, so that milestone is the one at stake if guidance were ever pressured enough to change dividend policy.
The Roundel Angle Analysts Are Underweighting
Most coverage anchors to merchandise comp sales. The more interesting signal is non-merchandise revenue. In Q2 fiscal 2026, Roundel-related advertising revenue was $279 million versus $217 million a year earlier. For the first six months of fiscal 2026, advertising revenues totaled $525 million. These are higher-margin dollars layered on top of the core merchandising business, and they do not trade at a mid-teens multiple at Amazon or at Walmart’s ad unit. That compression is an inefficiency worth watching.
The Q3 Setup
Q2 consensus was about $2.35; Target delivered $4.11, though $1.65 of that came from $994 million in tariff refunds. Strip the one-time item and the underlying beat was still meaningful: roughly $2.46 versus about $2.33 estimated on an adjusted basis. Q3 consensus now sits near $2.06, against $1.78 a year ago, which is a mid-teens bar. Truist has flagged risk of cautious Q4 holiday guidance because sales momentum slowed after August. That is the bear case in a sentence. Full-year adjusted EPS guidance, excluding the tariff benefit, is $8.25 to $9.25 per share, with net sales growth guided in the range of 5% to 6%.
Technical Framework
TGT is trading beneath its Q2 earnings-day close of $161.32 and has pulled back from the 52-week high set in late October. The $155 level, near the August breakout zone, is the first structural support of consequence. A close below $150 would bring the 200-day moving average into play, historically a decision point for institutional holders. Volume has been elevated on down sessions, which warrants monitoring heading into the report date.
Scenario Modeling
Bull Case ($175+): Q3 comps print above 3%, holiday guidance lands at the high end of the full-year range, and Roundel’s ad revenue growth accelerates. The valuation discount to Walmart and Costco begins to compress. Dividend King status reinforces income buyer demand on any pullback.
Base Case ($158-$168): Q3 EPS near $2.00-$2.10, in-line holiday guidance, and continued digital comp growth around 8%. The stock drifts modestly higher into year-end without a sharp multiple rerate. Roundel carries the incremental margin story into fiscal 2027.
Bear Case (sub-$145): Soft Q3 comps below 1.5%, a cautious Q4 guide citing consumer spending fatigue, and no tariff-refund buffer this time. The mid-teens forward multiple becomes a floor test rather than a valuation opportunity.
Active Trader Framework
The ex-dividend date on November 10, 2026 creates a mechanical flow dynamic before earnings. Traders holding through for the $1.16 dividend need to price that against the binary outcome on November 18. Position sizing matters here: the stock has moved 5-6% in both directions on recent quarterly reports. Defined-risk structures using options allow participation in the Q3 catalyst without open-ended exposure to a holiday guidance miss. The $155 level is the key downside marker; a close above $165 pre-earnings would signal that institutional buyers are front-running a strong earnings report.
Conclusion
Target’s 55-year dividend growth streak is the income story. Roundel, Circle 360, and same-day delivery are the growth story the market has not fully priced. The valuation gap versus large-cap retail peers is real and historically wide. Whether that gap closes on November 18 or widens depends entirely on whether October comp sales held up. Know your levels, size accordingly, and let the data lead.