I’ve spent my career studying gold cycles – and what just happened on February 28th…
It is the most important shift I’ve ever seen.
While the headlines show missiles and war maps…
Iran made a move that’s far more consequential to the money in your bank account…
They installed a toll booth in the Strait of Hormuz – the chokepoint that carries one out of every five barrels of oil on Earth.
Every tanker now pays to pass that Strait – but not in dollars.
In Chinese yuan.
Since then, more than 11.7 million barrels of crude have already moved through this system… completely outside the U.S. dollar clearing network.
That’s not theory.
It’s execution.
For 50 years, oil forced global demand for dollars.
Oil-producing nations recycled those dollars into U.S. Treasuries… and back into markets like the S&P, NASDAQ, and Dow.
That’s how America funded itself.
Now, that engine is breaking down.
Because if oil moves without dollars… Countries don’t need dollars.
And if they don’t hold dollars… They won’t buy Treasuries.
You’re already seeing it:
Foreign central bank holdings just hit their lowest level since 2012… with $82 billion dumped in three weeks. Even worse…
Central banks now hold more gold than Treasuries for the first time in 30 years.
So, what’s coming next?
The U.S. must refinance $9 trillion in debt in the next 12 months.
If buyers don’t show up…
The Fed steps in.
Which means more money printing… a lot more.
Historically, this ends one way:
And here’s where most investors will go wrong…
Most investors will look to buy physical gold. Wrong move.
Because the real leverage is in miners – miners still priced for $1,800 gold… not $4,800.
Go here to see my top four picks before this repricing accelerates.
To your wealth,
Garrett Goggin, CFA, CMT
P.S. Oil just moved outside the dollar system – and $9T in debt is coming due with fewer buyers. That forces money printing… and gold higher. Go here to see the four miners positioned to make early investors a generational fortune as gold accelerates to the upside.
P&C Profits Are at Historic Highs. Here’s What Traders Need to Know.
The U.S. property/casualty sector just produced one of its strongest six-month underwriting results on record, and most equity market participants are not paying attention. That is where the positioning opportunity lives.
Bullet Summary
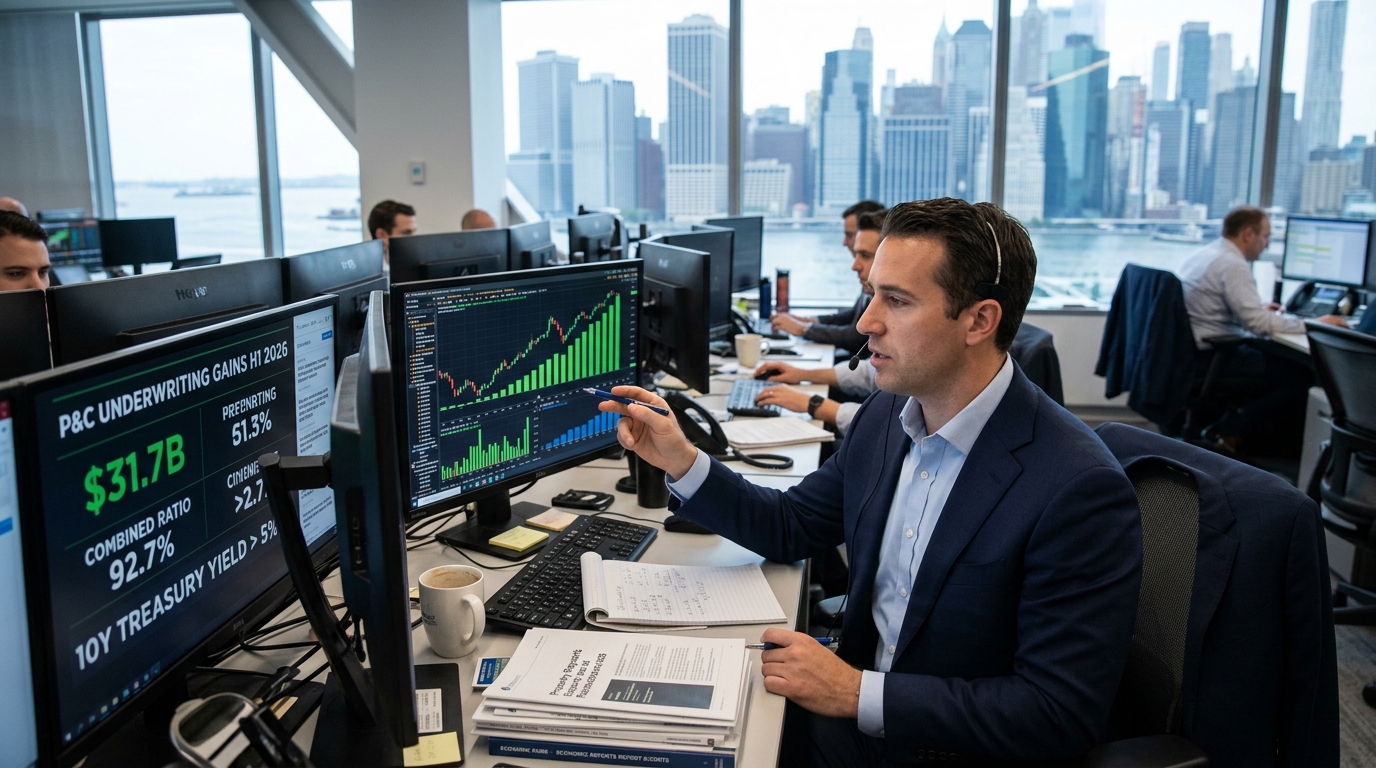
- U.S. P&C net underwriting gain reached $31.7 billion in H1 2026, up from $11.6 billion in H1 2025, per Verisk and APCIA.
- Industry combined ratio improved to 92.7% from 96.5% year-over-year; AM Best pegs it at 92.5% after catastrophe losses fell to 6.2 points from 10.8 points.
- Net income after taxes surged 53% to $77.8 billion; net written premium growth slowed sharply to 2.1% from 5.2%.
- Chubb posted a Q2 P&C combined ratio of 83.8% and pre-tax net investment income of $1.76 billion, up 12.3%.
- Travelers reported a Q2 combined ratio of 83.6% with net investment income of $2.078 billion pre-tax ($1.716 billion after-tax), up 11%.
- Policyholders’ surplus rose to $1.30 trillion, up from $1.13 trillion at midyear 2025.
- Nuclear verdict median hit $51 million in 2024, up from $44 million in 2023, with 135 cases totaling $31.3 billion.
Market Context Analysis
The macro backdrop is doing real work for insurers right now. The 10-year Treasury yield closed at 5.17% on September 25, 2026, near a 19-year high, after the Fed raised rates at its September 16, 2026 meeting. Swaps markets are pricing additional quarter-point increases over the next year. For carriers holding large fixed-income float portfolios, that is not a headwind. It is a compounding engine.
Catastrophe losses provided additional clarity in H1. The absence of a repeat of the January 2025 Los Angeles-area wildfires cut catastrophe loss points on the combined ratio from 10.8 to 6.2, per AM Best. That swing alone accounts for a large share of the underwriting improvement. Traders should model for the possibility that H2 2026 CAT activity normalizes upward, which is a standard risk in any active hurricane season.
Sector Breakdown
Commercial P&C pricing is softening. Net written premium growth decelerated to 2.1% in H1 2026 from 5.2% in H1 2025, with net earned premiums growing 3.3% versus 7.3% a year earlier. The carriers best positioned are those with sufficient scale and underwriting discipline to selectively exit business that no longer meets margin requirements rather than chasing volume.
Property reinsurance is softening faster than primary, which creates a bifurcated picture. Casualty lines, including commercial auto, excess liability, and umbrella, remain under sustained pressure from claim severity, rising medical costs, and nuclear verdicts. Bodily injury and commercial liability losses continued to worsen in H1, per APCIA. That divergence between property relief and casualty stress is the central risk management variable for the back half of 2026.
Stock-Specific Financial Breakdown
Chubb is the clearest illustration of disciplined execution in a transitioning cycle. Its Q2 P&C combined ratio of 83.8% ran nearly 9 points below the U.S. industry average, even as it deliberately reduced North America commercial P&C net premiums written by 2.3% to $5.59 billion, including a 9% decline in major accounts and E&S wholesale property. Pre-tax net investment income hit $1.76 billion, up 12.3%, against a total invested asset base of $175 billion. Core operating income came in at $2.84 billion, or $7.26 per share.
Travelers reported Q2 net income of $2.208 billion, with a combined ratio of 83.6%, improved from 90.3% in Q2 2025. Net investment income rose 11% to $2.078 billion pre-tax ($1.716 billion after-tax), driven by higher yields and growth in average invested assets. Net written premiums held at $11.529 billion. Return on equity reached 27.1%.
Technical / Trading Framework
Insurance sector ETFs and individual names have lagged broader financial sector momentum in September, creating a potential relative-strength reversion opportunity. Watch the 50-day and 200-day moving averages on both CB and TRV for confirmation of any rotation. Volume patterns during earnings releases were constructive in July, with both names holding above pre-announcement support levels after initial selling on premium growth deceleration headlines. VWAP from the Q2 earnings date serves as a near-term anchor for both names.
Scenario Modeling
Bull Case: The 10-year yield stays above 5% through year-end, investment income continues compounding at double-digit rates, and the Atlantic hurricane season produces below-average insured losses. Combined ratios hold below 90% industry-wide, and capital rotation into defensive yield-generating equities accelerates as equity volatility picks up. CB and TRV test new 52-week highs.
Base Case: A moderate CAT quarter in Q3, continued casualty loss deterioration in commercial auto and umbrella, and modest premium deceleration produce full-year combined ratios in the 91-94% range. Investment income growth remains the primary earnings driver. Both names maintain current valuation multiples with dividend growth intact.
Bear Case: A major hurricane event in Q3 adds 8-12 points to the combined ratio. Casualty reserve deterioration accelerates beyond what headline results currently reflect, particularly in excess and umbrella lines where nuclear verdict frequency rose 52% in 2024. Premium softening deepens, removing pricing support. Names give back 10-15% from current levels before technical support at the 200-day moving average.
Active Trader Strategy Framework
Position sizing should account for CAT season tail risk through October. Traders with existing long exposure may consider defined-risk structures to limit downside on a major storm event while preserving upside from the investment income compounding thesis. Monitor reserve development disclosures closely: casualty lines with elevated social inflation exposure can produce reserve charges that lag the headline combined ratio by multiple quarters. Key levels to watch: policyholders’ surplus at $1.30 trillion provides a capital buffer, but a bad CAT quarter can shift sentiment faster than fundamentals justify.
Conclusion
This is not a momentum trade. It is a disciplined capital allocation decision grounded in two durable data points: a sector running near-record underwriting profitability and a fixed-income yield environment that continues to reward carriers with large float portfolios. The risk is real, concentrated in casualty lines and CAT exposure. Preparation means knowing which carriers have the balance sheet and the underwriting culture to absorb that risk without compromising the compounding math. The numbers, as of Q2, favor Chubb and Travelers by a wide margin over the industry average. Track what happens to that gap in Q3.