The argument about whether the Fed has done enough rarely gets settled in committee rooms or on trading desks. It gets settled in the housing market. Right now, housing is making the case that policy is already tight, and it is doing so with a kind of blunt, consistent force that forward guidance cannot easily dismiss.
The Numbers Are Not Ambiguous
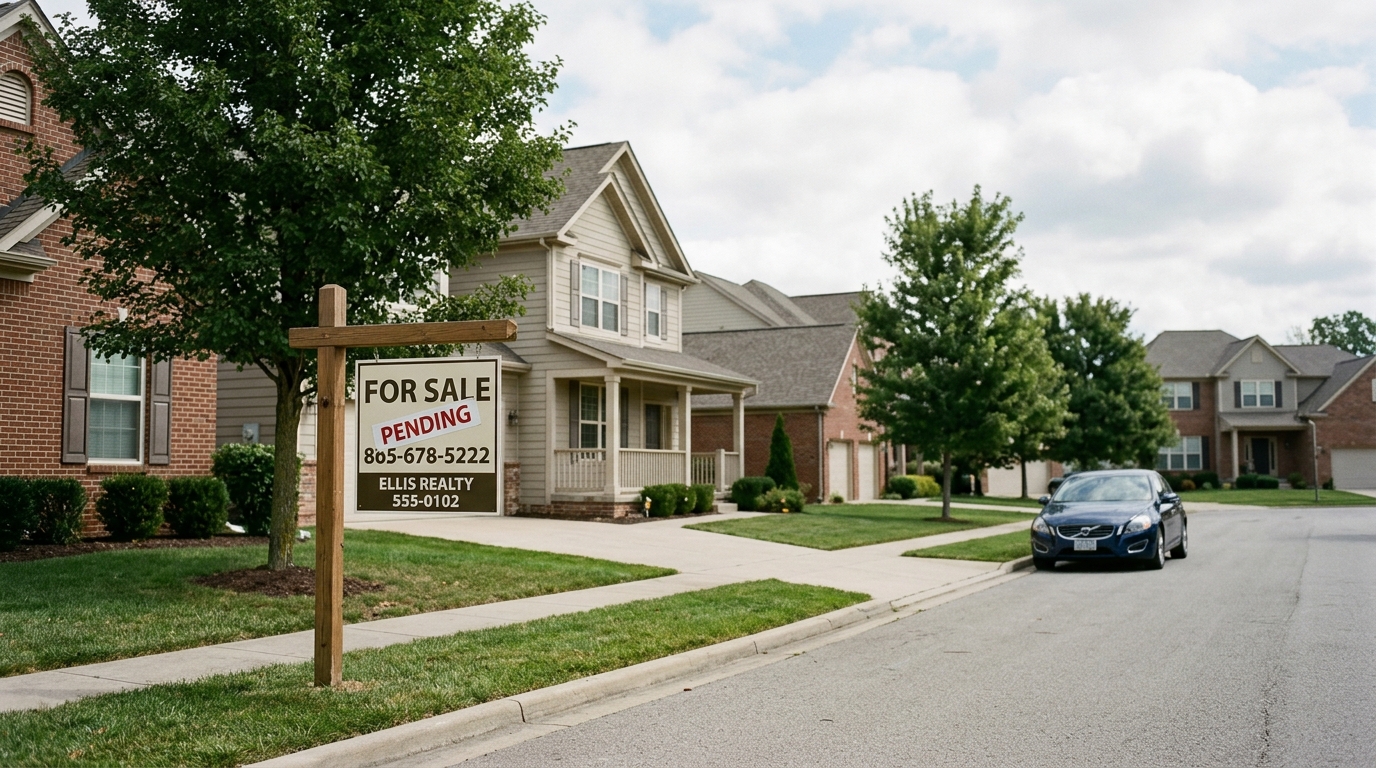
Pending home sales declined 1.9% from the prior week to the lowest level in Redfin records dating back to 2021, with weekly average mortgage rates holding at 7.4%. That is not a regional story or a seasonal quirk. For the second consecutive week, pending sales fell in all 50 of the most populous U.S. metro areas. Behind that broad retreat is a payment problem: the median monthly housing payment jumped to the second-highest level on record in Redfin data, at $2,796.
The existing-sales data tells the same story with a longer time horizon. NAR chief economist Lawrence Yun noted that August and September marked the two slowest months for home sales this year, adding that further increases in mortgage rates mean fewer buyers can qualify. Inventory reached its highest level since November 2019, yet buyers are not showing up to absorb it. Supply is rising not because new households are listing confidently, but because the pool of qualified buyers has shrunk faster than sellers have pulled back.
Why the 10-Year Is the Real Fed Funds Rate for Housing
Here is the institutional debate worth having before Wednesday’s Fed decision. The policy rate is not what is strangling housing. The 10-year Treasury is. The benchmark 10-year yield finished last Friday at 5.00%, down from its peak of 5.31% on October 5, its highest close since 2002, but still at a level that keeps mortgage costs elevated. The 10-year is not the only input into mortgage pricing, but it is a key benchmark for long rates. As long as it stays near 5%, monthly financing costs stay high and affordability stays under pressure.
Professional investors who want to argue the Fed should cut need to reckon with that spread. The spread between the 10-year Treasury and the 30-year fixed mortgage rate has remained elevated versus pre-pandemic norms that were often closer to roughly 1.5% to 2.0%. Until that spread normalizes, even a modest Fed cut does little to move the monthly payment on a new purchase.
The Policy Lever That Bulls Were Pricing Has Been Removed
The one policy development that housing investors had been quietly discounting was a faster Fannie Mae and Freddie Mac conservatorship exit, which bulls argued could eventually compress the mortgage spread and ease financing costs. That lever was removed last week. Treasury Secretary Scott Bessent said the Trump administration would not be loosening its grip on the mortgage giants soon, suggesting the ownership structure would not be tackled until 2027 or 2028.
Mizuho had already downgraded Fannie Mae and Freddie Mac to Neutral and cut both price targets, citing diminished prospects for a fast conservatorship exit by 2028. The stocks are sharply lower this year as investors grow impatient for an exit from government control. Bill Ackman, one of the most prominent advocates for an exit, called it “absolutely politically critical” for Fannie and Freddie to be released before the end of the Trump administration, but Bessent has made clear that affordability protection comes before shareholder returns.
What Investors Are Missing
The overlooked implication runs through the builders. New construction is slowing, with housing starts falling 5.2% in September to an annual rate of 1.221 million, 7.4% below a year earlier, while builder confidence fell to 29 in October, its lowest level since June 2012. Incentive costs are rising to compensate. PulteGroup reported a home sale gross margin of 24.8% in Q3, down 140 basis points from a year earlier, with incentives equal to 10.4% of home sales revenue compared with 8.9% in the prior-year quarter.
Over the past year, the homebuilder ETF ITB returned about negative 15%, while earnings of the companies in the fund fell approximately 22%, making the fund more expensive even as its price fell. Wall Street’s forward multiples embed an earnings recovery that requires rates to cooperate. ITB’s forward price-to-earnings ratio has been cited around 12.8x, implying analysts expect earnings to rise over the next year. With mortgage rates above 7%, that recovery is the part of the price most at risk.
Stocks to Watch
- D.R. Horton (DHI): Reports fiscal fourth-quarter earnings October 29 into a difficult backdrop, with analysts expecting lower earnings and revenue as mortgage rates around 7.4% have weakened demand and pressured incentives. The read on cancellation rates and community-level traffic will be the most honest current measure of demand destruction.
- PulteGroup (PHM): First-time and move-up buyers were hit hardest in Q3, with orders down 9% and 14% respectively. Its active-adult segment is the partial offset, but the volume trend is deteriorating at the cohorts that actually need financing.
- Lennar (LEN): Remains down roughly 25% for the year. The company’s asset-light pivot reduces land risk but cannot insulate margins if incentives keep climbing to move spec inventory.
- Fannie Mae (FNMA) / Freddie Mac (FMCC): With Bessent signaling a 2027 to 2028 timeline, the gap between Ackman’s push for a near-term release and the Treasury secretary’s deferral helps explain both the long slide and the headline-driven pops. These are political timing trades, not fundamental ones.
- XHB: The broader homebuilder ETF carries exposure beyond the pure builders. Pending sales falling in every major metro for two straight weeks is a leading indicator for the entire supply chain. Wednesday’s Fed decision changes nothing structurally unless it comes with explicit guidance on long-end yield management, which no one expects.